Scar Treatment Market (2026-2036)
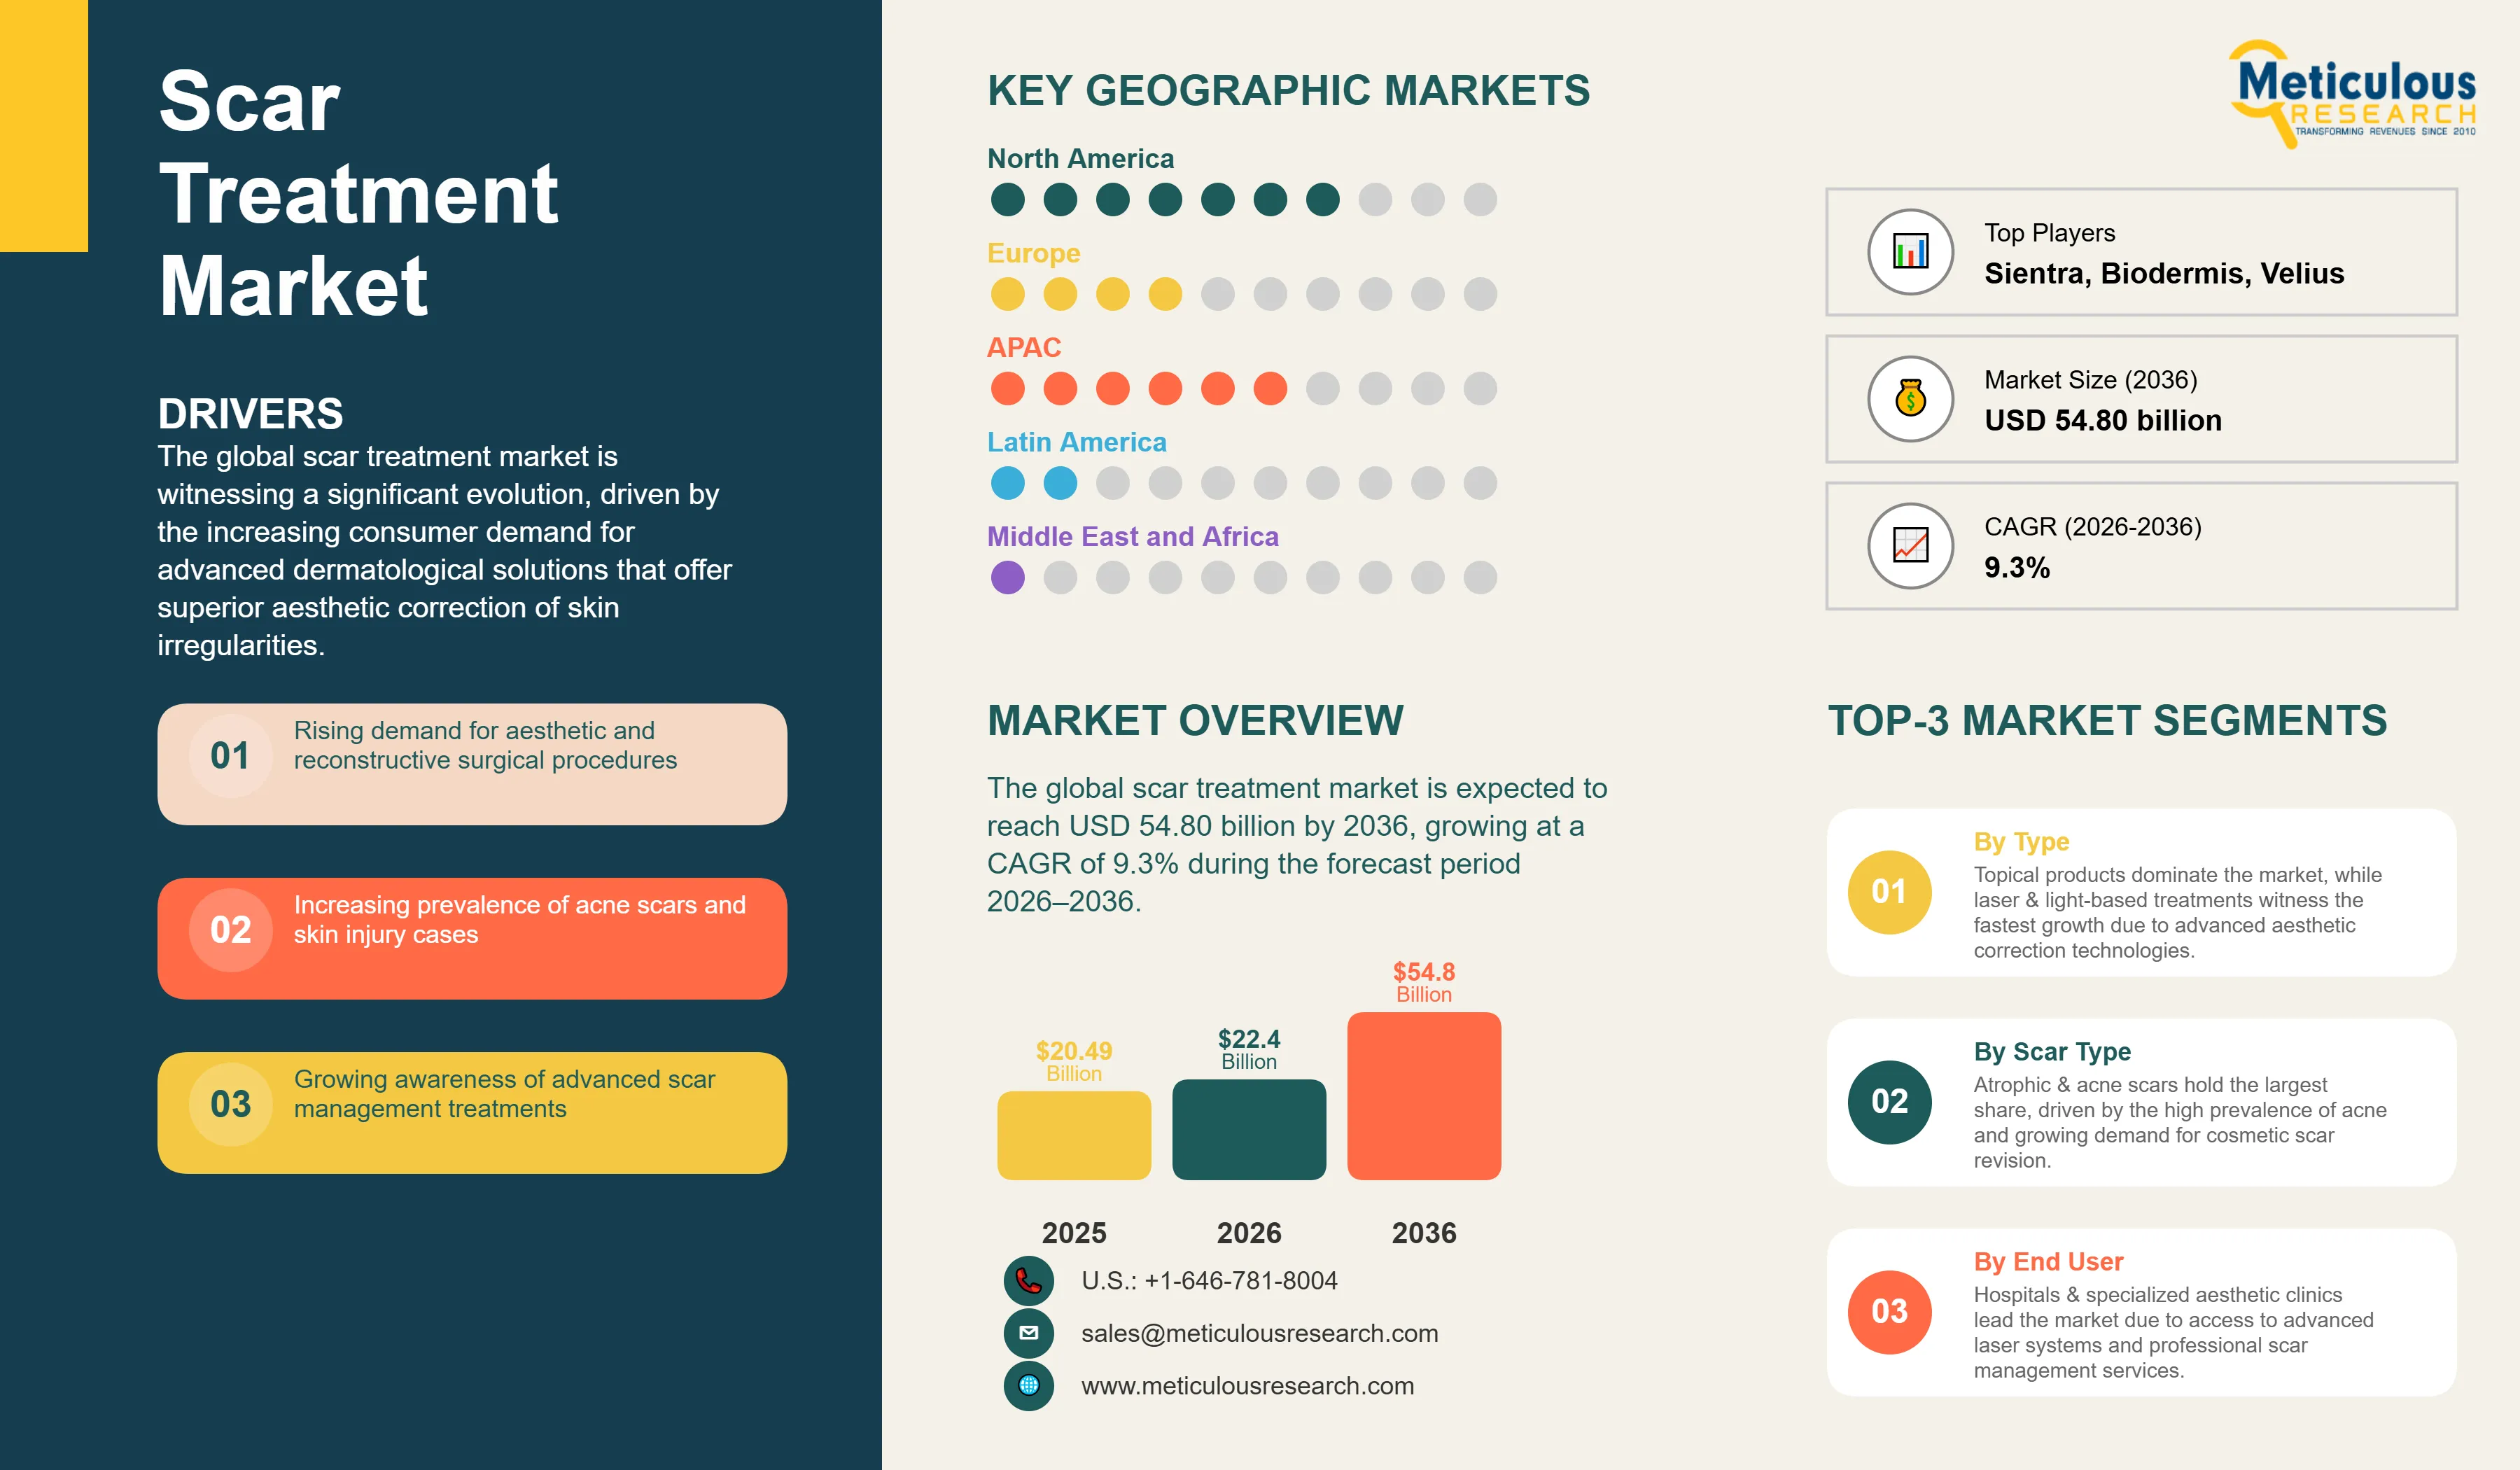
The global scar treatment market is estimated to be USD 22.40 billion in 2026. This market is expected to reach USD 54.80 billion by 2036, growing at a CAGR of 9.3% during the forecast period 2026–2036.
- Published
- Jun 2026
- Pages
- 278
- Format
- PDF + Excel
- Report ID
- MRHC - 1042074
- Base year
- 2025
- 2026 · ESTIMATED
- $22.40B
- 2036
- $54.80B
- CAGR 2026–2036
- 9.3%
2025 baseline · 2026–2036 forecast at 9.3% CAGR · hover a bar for the value
Key highlights
The global scar treatment market is projected to reach USD 54.80 billion by 2036, growing at a CAGR of 9.3% during the forecast period 2026–2036.
North America is expected to dominate the global market in 2026, supported by an advanced aesthetic medicine infrastructure and high consumer spending on personal care.
Asia-Pacific is projected to witness the fastest growth, fueled by the rapidly expanding aesthetic medicine market and rising disposable income.
By product type, the topical products segment is expected to hold the largest share in 2026, as the primary first-line treatment for post-surgical scarring.
By product type, the laser & light-based treatments segment is projected to be the fastest-growing, driven by rapid technological advancements in aesthetic correction.
By scar type, the atrophic & acne scars segment is expected to hold the largest share in 2026, due to the high global prevalence of acne vulgaris.
By end user, the hospitals & specialized aesthetic clinics segment is expected to hold the largest share in 2026, providing advanced surgical and laser-based revisions.
Key players operating in the global market include Smith & Nephew plc, Bausch Health Companies Inc., and Lumenis Be Ltd.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 22.40 billion |
| Market Size (2036) | USD 54.80 billion |
| CAGR (2026–2036) | 9.3% |
| Format | PDF, Excel & Cloud Portal · 278 pages |
| Segments Covered | By Product Type · By Scar Type · By End User |
| Key Companies | Smith & Nephew plc (UK), Bausch Health Companies Inc., Lumenis Be Ltd., Mölnlycke Health Care AB, Perrigo Company plc, Hologic, Inc. (Cynosure) (US), Suneva Medical, Inc. (US), Encore Dermatology, Inc. (US), Alliance Pharma plc (UK), Sonoma Pharmaceuticals, Inc. (US), Sientra, Inc. (US), Candela Corporation (US), Merz Pharma GmbH & Co. KGaA, Scarguard Labs LLC (US), Revitol Corporation (US), Quantum Health (US), Pacific World Corporation (US), Biodermis (US), Velius, LLC (US), AVITA Medical (US) |
Report overview
Segments covered: product type, scar type, end user.
The global scar treatment market is witnessing a significant evolution, driven by the increasing consumer demand for advanced dermatological solutions that offer superior aesthetic correction of skin irregularities. As a critical component of post-procedural and corrective skincare, scar treatment involves the use of specialized topical, injectable, and light-based therapies to minimize the appearance of atrophic, hypertrophic, and keloid scars. The market is primarily propelled by the rising global volume of surgical procedures and the increasing prevalence of acne-related scarring among younger demographics. Furthermore, the growing social emphasis on aesthetic perfection and the rising availability of specialized aesthetic clinics are broadening the clinical application of these treatments beyond traditional medical necessity. Technological advancements, such as fractional CO2 lasers and high-efficacy silicone-based topical gels, are significantly improving patient outcomes and reducing treatment durations. Clinical guidelines from the American Academy of Dermatology (AAD) and the International Society of Aesthetic Plastic Surgery (ISAPS) continue to emphasize the importance of early and multi-modal scar management protocols. As the industry focuses on developing non-invasive, user-friendly, and cost-effective solutions for home-based and clinical use, the market is expected to witness sustained growth, particularly in emerging economies where the aesthetic medicine infrastructure is rapidly modernizing, ensuring consistent market expansion through 2036.
Report infographic
Market dynamics
8 factors across 4 forcesRising Global Volume of Aesthetic and General Surgical Procedures
A major driver for the market is the rising global volume of both aesthetic and general surgical procedures. According to International Society of Aesthetic Plastic Surgery, more than 34.9 million aesthetic procedures were performed globally in 2023, including approximately 15.8 million surgical procedures and 19.1 million non-surgical procedures, reflecting the continued growth of the cosmetic treatment market. Furthermore, the World Health Organization estimates that approximately 1.19 million people die annually from road traffic accidents, while tens of millions sustain non-fatal injuries, many of which require surgical intervention and subsequent scar management. Every surgical procedure, whether performed for medical or aesthetic purposes, carries the risk of post-procedural scarring, creating sustained demand for scar prevention and treatment solutions. The increasing popularity of elective cosmetic procedures, combined with the growing number of trauma-related and general surgeries, is driving demand for topical scar therapies, silicone-based products, injectables, and laser-based treatments. This trend is particularly evident in developed healthcare markets and rapidly expanding healthcare systems across emerging economies.
Growing Social Stigma Associated with Facial Scarring and the Resulting High Demand for Aesthetic Correction
The market is significantly driven by the growing social stigma associated with facial scarring, particularly atrophic and acne scars, which affects a large segment of the adolescent and young adult population. The high psychological impact of visible scarring is encouraging individuals to seek effective aesthetic corrections through both over-the-counter topical solutions and specialized clinical treatments. This patient-driven demand is further bolstered by the increasing influence of social media and the growing availability of specialized aesthetic clinics that offer fractional laser and chemical peel treatments. This focus on aesthetic perfection is making scar treatment a priority for consumers, reinforcing its position as a high-growth segment within the broader dermatological market.
Table of contents
12 chapters · 110 sections · 278 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Topical products | Laser & light-based treatments |
| By Scar Type | Atrophic & acne scars | Keloid scars |
| By End User | Hospitals & specialized aesthetic clinics | Home care settings |
By Product Type
- The topical products segment is expected to hold the largest share of the global scar treatment market in 2026.
- This leadership is substantiated by its status as the primary first-line treatment recommended by clinical guidelines for post-surgical and minor wound scarring.
- The high availability of silicone gels and sheets as over-the-counter solutions ensures its dominant market position.
- However, the laser & light-based treatments segment is projected to register the highest CAGR during the forecast period.
- The rapid technological advancements in fractional CO2 lasers and the increasing consumer focus on achieving superior aesthetic outcomes for complex scars are driving the rapid adoption of these clinical interventions.
By Scar Type
- The atrophic & acne scars segment is expected to hold the largest share in 2026, due to the high global prevalence of acne vulgaris and the resulting high patient demand for aesthetic correction.
- However, the keloid scars segment is projected to register the highest CAGR during the forecast period.
- The increasing clinical emphasis on managing these difficult-to-treat lesions through multi-modal therapies and growing awareness of specialized keloid management techniques are significantly boosting demand in this segment.
By End User
- The hospitals & specialized aesthetic clinics segment is expected to hold the largest share in 2026, as they provide advanced surgical and laser-based revisions that require professional expertise and specialized equipment.
- However, the home care settings segment is projected to register the highest CAGR during the forecast period.
- The increasing adoption of professional-grade topical silicone treatments and the growing availability of high-efficacy OTC scar treatment kits are facilitating rapid growth in this segment.
Geographic analysis
North America
Largest shareNorth America is expected to dominate the global scar treatment market in 2026. This leading position is attributed to its advanced aesthetic medicine infrastructure, high consumer spending on personal care, and the presence of major industry players. Data from the ASPS and AAD indicates a high level of consumer awareness regarding scar revision and high adoption rates of both topical and laser-based therapies in the U.S., which is a major factor driving the high regional market valuation and the consistent demand for premium dermatological products in the U.S. and Canada. Largest Share: North America
Asia-Pacific
Fastest growthThe Asia-Pacific region is projected to witness the fastest growth in the global scar treatment market, with a CAGR of 10-12% during the forecast period. This rapid expansion is driven by the rapidly expanding aesthetic medicine market, improving healthcare access, and rising disposable income. Reports from the ISAPS highlight a significant increase in the volume of aesthetic procedures across APAC, directly translating into higher demand for both post-procedural and corrective scar treatment solutions in countries like China, India, and South Korea. Fastest Growing: Asia-Pacific
Competitive landscape
The global scar treatment market is characterized by a high degree of fragmentation, with a diverse range of pharmaceutical companies and aesthetic device manufacturers competing across the topical and clinical segments. Competition is primarily focused on improving the efficacy, aesthetic outcomes, and patient comfort of treatments to capture a larger share of the growing aesthetic correction market. Key players are investing heavily in R&D to develop advanced fractional laser platforms and high-performance silicone formulations that enhance scar maturation. Strategic developments often involve acquisitions of specialized dermatological firms and partnerships with aesthetic medical societies like ISAPS to validate new multi-modal treatment protocols. Furthermore, there is a growing focus on providing comprehensive scar management kits that combine professional-grade topicals with clinical interventions. Manufacturers are also increasingly focusing on robust clinician training programs and direct-to-consumer marketing to build brand awareness and ensure the successful implementation of their systems in specialized clinics and hospital settings, which is critical for maintaining market leadership in this highly competitive field.
- Smith & Nephew plc (UK)
- Bausch Health Companies Inc. · Canada
- Lumenis Be Ltd. · Israel
- Mölnlycke Health Care AB · Sweden
- Perrigo Company plc · Ireland
- Hologic, Inc. (Cynosure) (US)
- Suneva Medical, Inc. (US)
- Encore Dermatology, Inc. (US)
- Alliance Pharma plc (UK)
- Sonoma Pharmaceuticals, Inc. (US)
- Sientra, Inc. (US)
- Candela Corporation (US)
- Merz Pharma GmbH & Co. KGaA · Germany
- Scarguard Labs LLC (US)
- Revitol Corporation (US)
- Quantum Health (US)
- Pacific World Corporation (US)
- Biodermis (US)
- Velius, LLC (US)
- AVITA Medical (US)
Frequently asked questions
The global market is estimated at USD 22.40 billion in 2026, with a projected growth to USD 54.80 billion by 2036, at a CAGR of 9.3%.
Cite this report
Meticulous Research. (2026). Scar Treatment Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1042074). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/scar-treatment-market-6757