Recombinant Coagulation Factors Market (2024-2031)
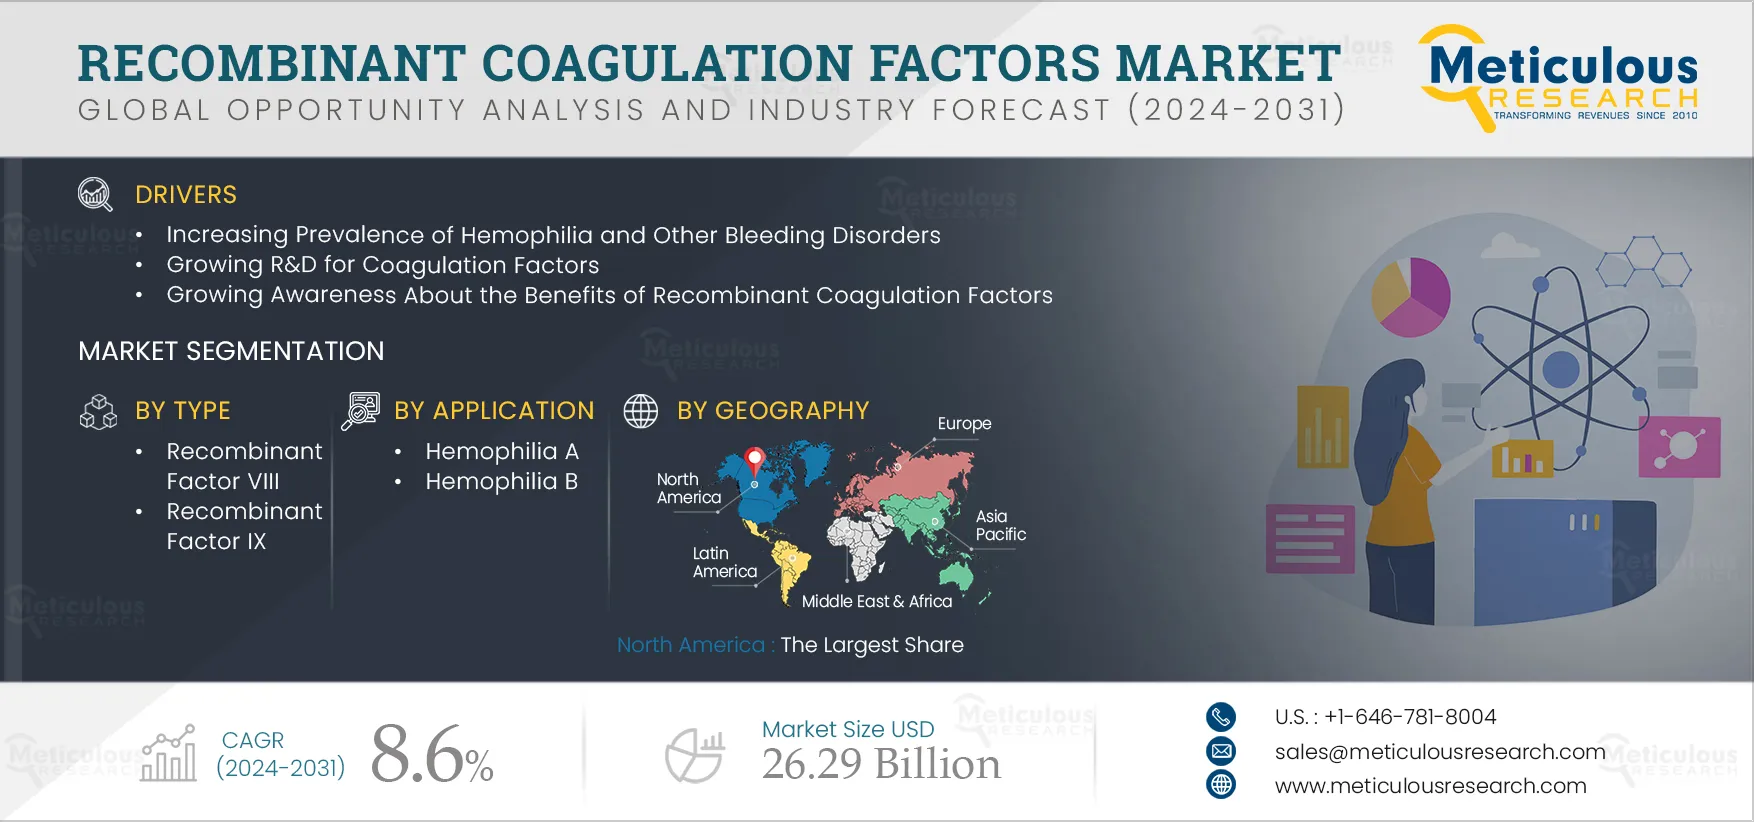
The Recombinant Coagulation Factors Market is projected to reach $26.29 billion by 2031, at a CAGR of 8.6% from 2024 to 2031.
- Published
- Jul 2024
- Pages
- 180
- Format
- PDF + Excel
- Report ID
- MRHC - 104168
- Base year
- 2022
- 2031 · FORECAST
- $26.29B
- 2031
- $26.29B
- CAGR 2024–2031
- 8.6%
2022–2023 baseline · 2024–2031 forecast at 8.6% CAGR · hover a bar for the value
Key highlights
By Type: In 2024, the Recombinant Factor VIII Segment to Dominate the Recombinant Coagulation Factors Market
By Application: In 2024, the Hemophilia A Segment to Dominate the Recombinant Coagulation Factors Market
By End User: In 2024, the Hospitals & Clinics Segment to Dominate the Recombinant Coagulation Factors Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 180 |
| Format | |
| Forecast Period | 2024-2031 |
| Base Year | 2022 |
| CAGR | 8.6% |
| Estimated Market Size (Value) | $26.29 billion by 2031 |
| Segments Covered | By Type · Recombinant Factor VIII · Recombinant Factor IX · Other Types · (Note: Other types include recombinant factor XIII, VIIa, and X) · By Source · Chinese Hamster Ovary (CHO) Cell Line · Human Embryonic Kidney (HEK) Cell Line · Other Sources · (Note: Other sources include the Baby hamster kidney (BHK) cell line and COS cell line) · By Application · Hemophilia A · Hemophilia B · Other Applications · By End User · Hospitals & Clinics · Clinical Research Laboratories |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, France, U.K., Italy, Spain, Netherlands, Sweden, and Rest of Europe), Asia-Pacific (China, Japan, India, Australia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, Rest of Latin America), and Middle East & Africa |
| Key Companies | Baxter International Inc. (U.S.), Grifols, S.A. (Spain), CSL Limited (Australia), Octapharma AG (Switzerland), Novo Nordisk A/S (Denmark), Biogen Inc. (U.S.), Bayer AG (Germany), Kedrion S.p.A. (Italy), Emergent BioSolutions (U.S.), and Pfizer Inc. (U.S.). |
Report overview
Segments covered: type, source, application, end user. Regions: North America, Europe, Asia-Pacific, Latin America.
Recombinant coagulation factors differ from plasma-derived factors as they are produced using recombinant DNA technology. This production method ensures a very low risk of blood-borne transmission of infectious diseases, effectively eliminating the threat of viruses such as hepatitis C and human immunodeficiency virus (HIV). As a result, recombinant coagulation factors are primarily used in treating bleeding disorders such as hemophilia.
The increasing prevalence of hemophilia and other bleeding disorders, growing R&D for coagulation factors, growing awareness about the benefits of the recombinant coagulation factors, and increasing prophylactic treatment for hemophilia across the globe are driving the growth of the recombinant coagulation factors market. However, the high cost of recombinant factors compared to plasma-derived factors and the limited accessibility & availability of recombinant clotting factors in developing & underdeveloped countries are expected to restrain the growth of this market.
Furthermore, untapped markets in emerging economies and rising healthcare expenditure are expected to create market growth opportunities. However, challenges in the production of recombinant coagulation factors, stringent regulatory requirements, lack of reimbursement in some countries, and lack of awareness among patients are some of the challenges impacting the market’s growth.
Report infographic
Market dynamics
4 factors across 3 forcesRising Prevalence of Hemophilia
Hemophilia A and B are the most common severe hereditary hemorrhagic disorders. These disorders are caused due to coagulation factor VIII and factor IX protein deficiency. Patients with these disorders have prolonged bleeding with or without trauma, depending on the factor activity. According to National Center for Biotechnology Information (NCBI) data, in September 2022, the estimated frequency of hemophilia was about 1 in 10,000 live births, and the number of people worldwide living with hemophilia was about 4,00,000. Hemophilia A is more prevalent, about 80-85% of the total hemophilia population. Hemophilia A is present in 1 in 5,000 live male births, whereas hemophilia B is present in 1 in 30,000 live male births.
In order to tackle this disorder, coagulation factors, also known as clotting factors, are gaining popularity. The wide availability of recombinant factor VIII, viral inactivation, and better screening technology make the product and treatment safer. Thus, despite the availability of plasma-derived factor concentrates, about 75% of patients with hemophilia worldwide receive recombinant factor VIII products since they are much safer. Thus, the effectiveness of recombinant clotting factors products supports better treatment for hemophilic patients, driving the growth of this market.
Availability of Reimbursement Policies for Hemophilia
Hemophilia, a treatable yet costly rare disease, receives reimbursement coverage in some countries such as China, the U.S., and European countries. The availability of reimbursement policies for the disease increases the accessibility to recombinant coagulation factors. From 2012, the Chinese Ministry of Health has prioritized 20 high-cost diseases (including hemophilia) to ease patients’ economic burden. Similarly, from 2021 onwards, the Medicaid and NC Health Choice programs in the U.S. began covering [coagulation factor VIIa (recombinant)-jncw] lyophilized powder for solution, for intravenous use (Sevenfact) for use in the Physician Administered Drug Program.
Table of contents
12 chapters · 95 sections · 180 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | Recombinant Factor VIII | — |
| By Application | Hemophilia A | — |
| By End User | Hospitals & Clinics | — |
By Type
- The recombinant factor VIII segment is expected to account for the largest share of 59.5% of this market.
- The large market share of this segment is attributed to advancements in recombinant technology, high demand for recombinant factor VIII due to a large patient pool of individuals with Hemophilia A, rising accessibility of treatment, and growing awareness about the benefits of recombinant coagulation factors.
- Factor VIII plays a crucial role in mitigating chronic damage and preventing fatal bleeding, making it a preferred treatment for bleeding disorders.
- These benefits contribute to the large market share of this segment.
By Application
- The Hemophilia A Segment to Dominate the Recombinant Coagulation Factors Market
- The hemophilia A segment is expected to account for the largest share of 64.3% of the recombinant coagulation factors market.
- This segment’s large market share can be attributed to the larger number of patients with hemophilia A compared to hemophilia B, the increasing global prevalence of hemophilia, and supportive government initiatives aimed at enhancing treatment for hemophilia A.
- For instance, under India's National Health Mission, the government provides financial aid for the treatment of hemophilia A.
- Similarly, in the U.S., the National Hemophilia Program tracks patient data at national and regional levels to assess outcomes and improve care for individuals with hemophilia A.
By End User
- The hospitals & clinics segment is expected to account for the largest share of the recombinant coagulation factors market.
- The large market share of this segment is attributed to the increased adoption of recombinant coagulation factors in hospitals for the treatment of coagulation disorders, rising healthcare expenditure, and rising awareness among healthcare professionals.
- Furthermore, patients have access to reimbursement policies and government schemes designed to support the treatment of bleeding disorders.
- Many hospitals and clinics are forming partnerships with key players or other healthcare facilities to enhance treatment accessibility.
- For instance, in May 2023, the Amrita Hemophilia Treatment Center (India) partnered with the Manchester Hemophilia Treatment Center (U.S.) through a twinning program aimed at improving hemophilia care in India.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of the 43.4% of recombinant coagulation factors market. North America’s significant market share can be attributed to the increasing prevalence of hemophilia and bleeding disorders, rising accessibility and affordability for the treatment, supportive government initiatives aimed at enhancing treatment, the proliferation of treatment & research centers for hemophilia, and the increasing number of awareness programs for hemophilia. According to the Centers for Disease Control and Prevention, the hemophilia program is the largest in the CDC’s Division of Blood Disorders, working towards creating awareness about hemophilia causes, symptoms, and treatment. North America to Dominate the Market
Asia-Pacific
Fastest growthHowever, the market in Asia-Pacific is projected to register the highest CAGR of 10.3% during the forecast period. The growth of this market is driven by the increasing healthcare investments in developing countries like China and India and the rising preference for recombinant technology due to its advantages over traditional methods.
Competitive landscape
- April 2024
Pfizer Inc. (U.S.) received approval for BEQVEZ (fidanacogene elaparvovec-dzkt) from the U.S. FDA for the treatment of adults with moderate to severe hemophilia B who currently use factor IX (FIX).
- August 2023
Novo Nordisk (Denmark) received approval for Alhemo (concizumab injection) from Health Canada for the treatment of hemophilia A patients over the age of 12 years or older who test positive for factor VIII inhibitors.
- February 2023
Sanofi S.A. (France) received approval from the U.S. FDA for ALTUVIIIO [Antihemophilic Factor (Recombinant), Fc-VWF-XTEN Fusion Protein-ehtl]. The approved factor is a new class of factor VIII therapy for hemophilia A.
- Baxter International Inc. (U.S.)
- Grifols, S.A. · Spain
- CSL Limited · Australia
- Octapharma AG · Switzerland
- Novo Nordisk A/S · Denmark
- Biogen Inc. (U.S.)
- Bayer AG · Germany
- Kedrion S.p.A · Italy
- Emergent BioSolutions (U.S.)
- Pfizer Inc. (U.S.)
Frequently asked questions
This study offers a detailed assessment of the recombinant coagulation factors market and analyzes the market sizes & forecasts based on type, source, application, and end user. This report also involves the value analysis of various segments and subsegments of the recombinant coagulation factors market at the regional and country levels.
Cite this report
Meticulous Research. (2024). Recombinant Coagulation Factors Market - Global Opportunity Analysis And Industry Forecast (2024- 2031) (Report No. MRHC - 104168). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/recombinant-coagulation-factors-market-1254