Polymer Heat Exchangers Market (2026-2036)
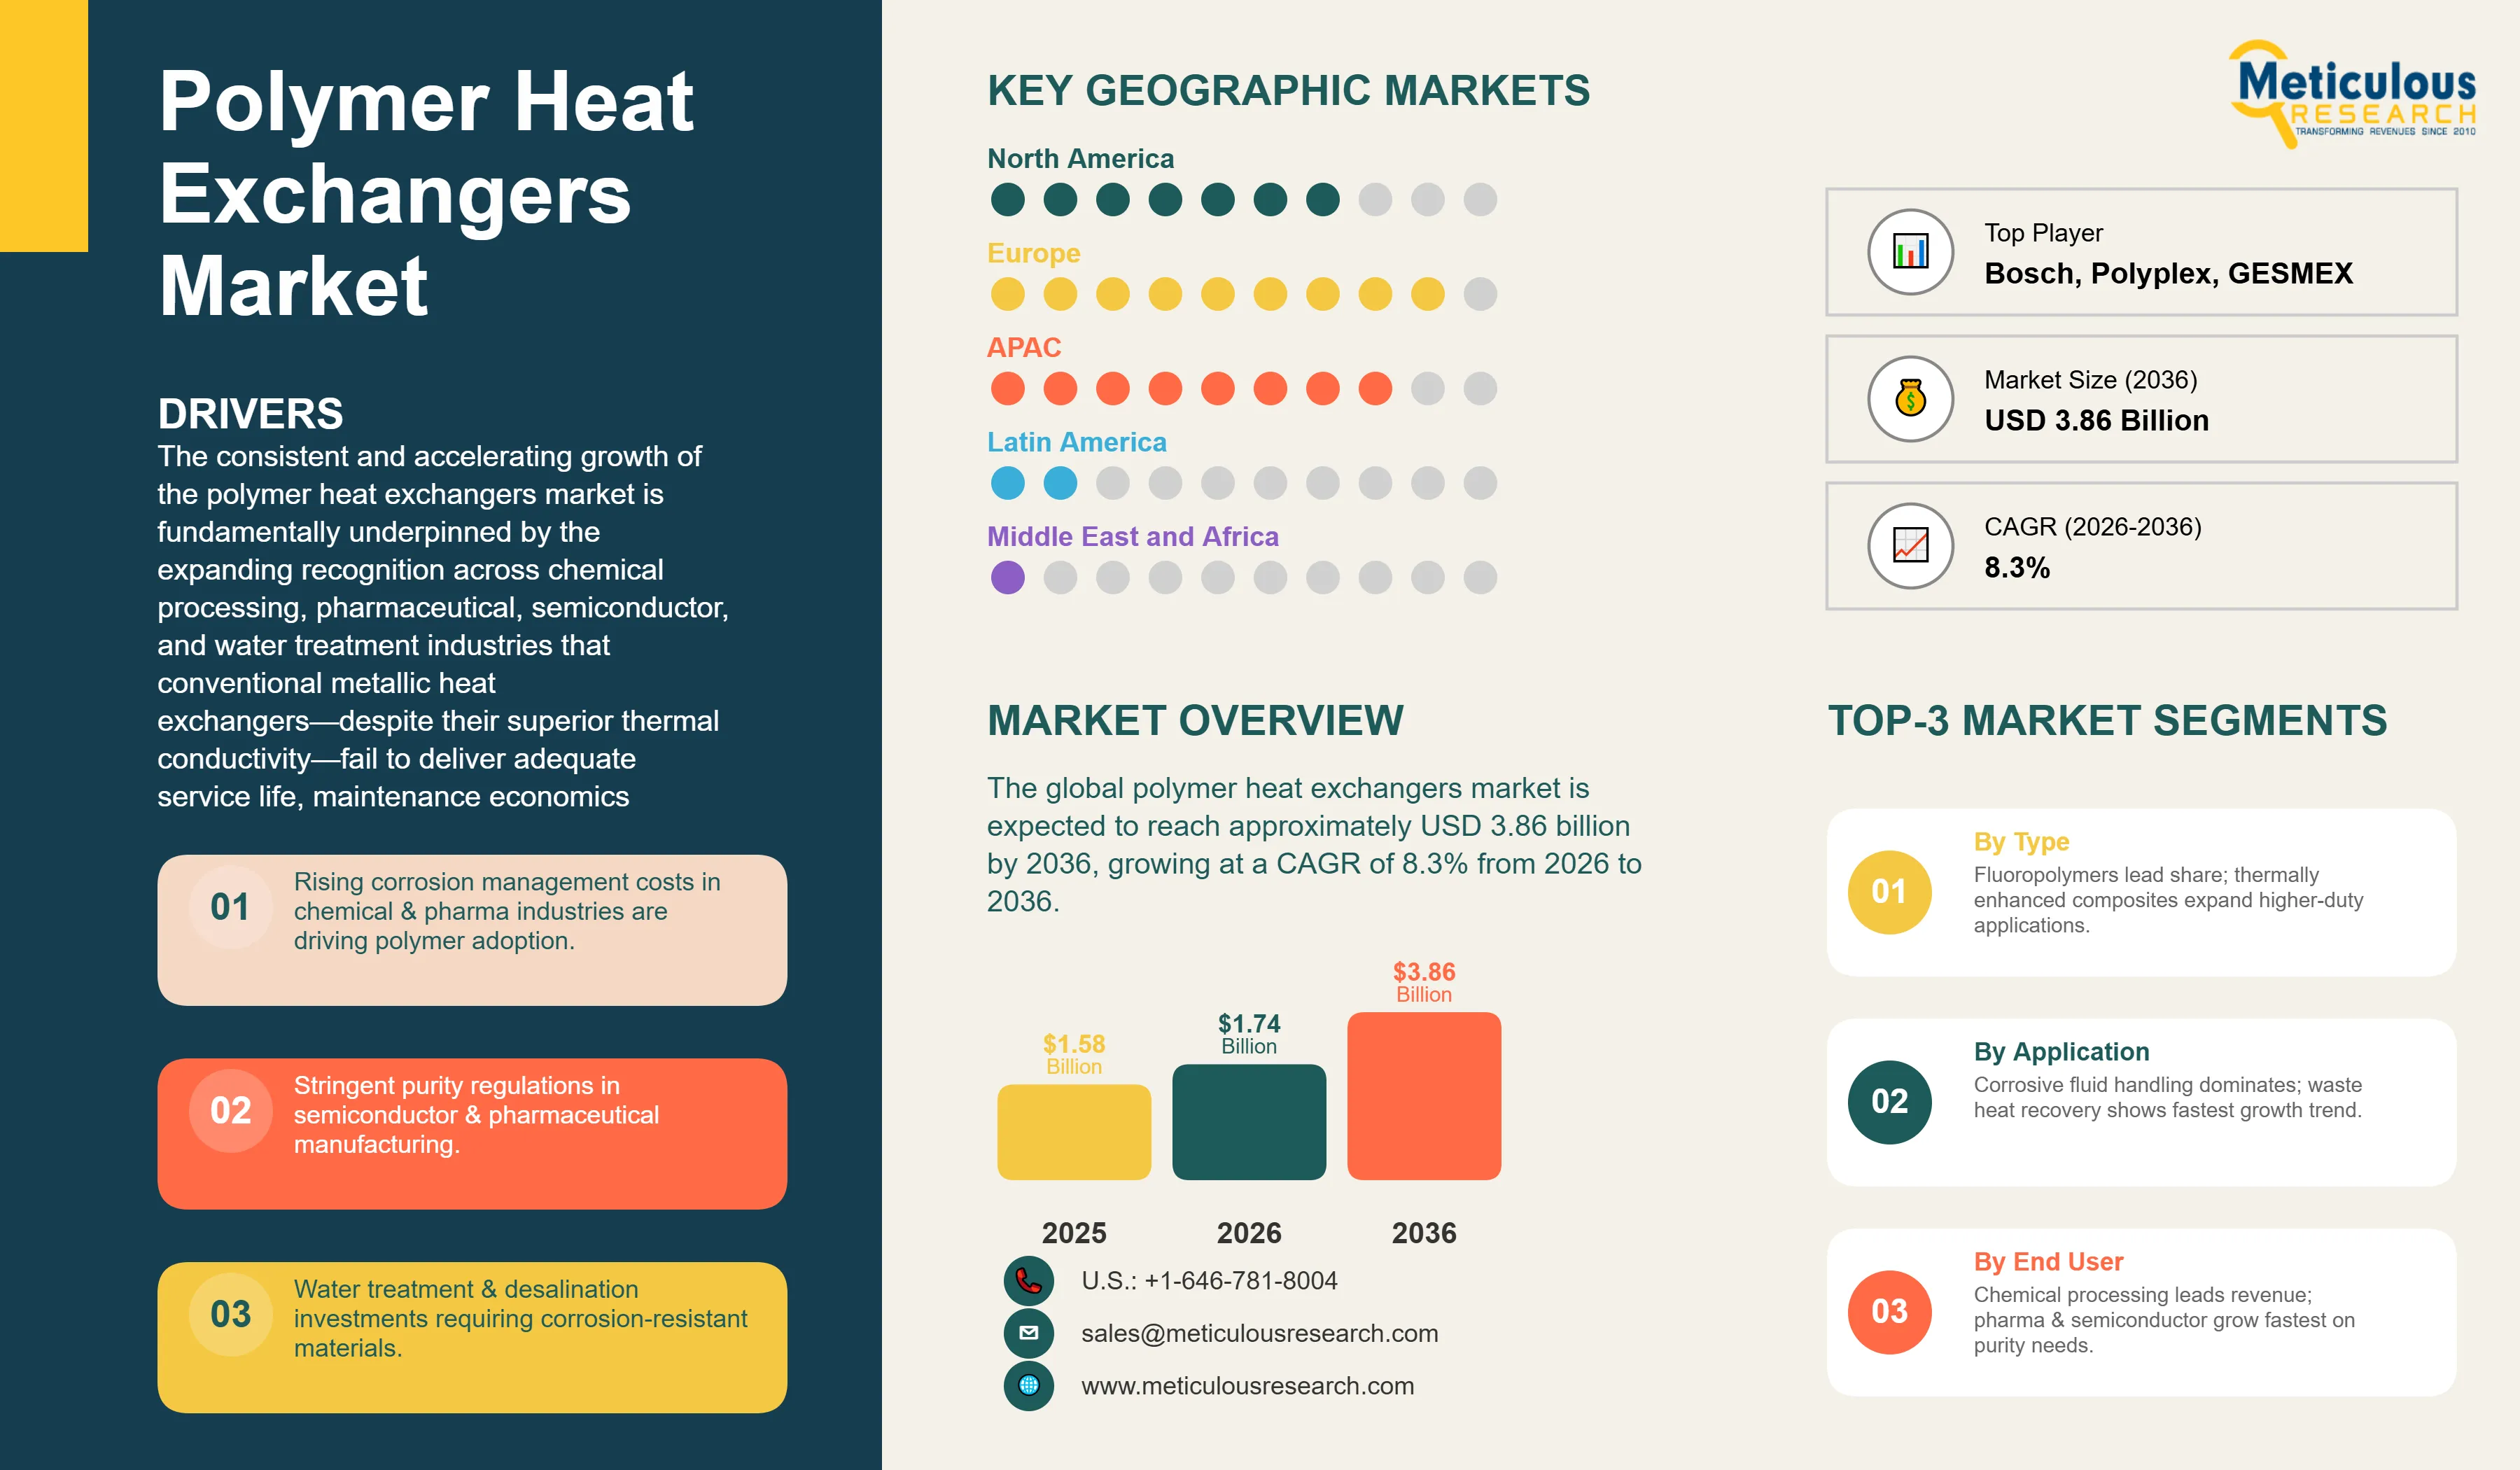
The global polymer heat exchangers market was valued at USD 1.58 billion in 2025. The market is expected to reach approximately USD 3.86 billion by 2036 from USD 1.74 billion in 2026, growing at a CAGR of 8.3% from 2026 to 2036.
- Published
- Mar 2026
- Pages
- 277
- Format
- PDF + Excel
- Report ID
- MRSE - 1041834
- Base year
- 2025
- 2025 · BASELINE
- $1.58B
- 2036
- $3.86B
- CAGR 2026–2036
- 8.3%
2025 baseline · 2026–2036 forecast at 8.3% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global polymer heat exchangers market is projected to reach USD 3.86 billion by 2036.
The market is expected to grow at a CAGR of 8.3% from 2026 to 2036.
Europe dominates the global polymer heat exchangers market with the largest market share in 2026, driven by the continent's concentrated chemical and pharmaceutical manufacturing base, stringent EU environmental regulations mandating closed-loop processing and eliminating heavy metal contamination, and the presence of leading polymer heat exchanger manufacturers including Ametek, GESMEX, and Bosch Thermotechnology with strong European customer relationships.
Asia-Pacific is expected to witness the fastest growth during the forecast period, supported by rapidly expanding semiconductor fabrication capacity requiring ultra-high purity polymer heat exchangers, massive investment in chemical and petrochemical processing infrastructure across China, India, and Southeast Asia creating corrosive fluid handling demand, and growing pharmaceutical manufacturing outsourcing to Asian contract manufacturers adopting international quality standards requiring polymer materials.
By material type, the fluoropolymers segment holds the largest market share in 2026, reflecting PTFE and PVDF's unmatched chemical resistance, broad temperature capability, and established specification position in the most demanding corrosive applications in chemical, semiconductor, and pharmaceutical industries.
By product type, the shell and tube segment holds the largest market share in 2026, benefiting from its familiar engineering design basis enabling direct replacement of conventional metallic shell-and-tube exchangers with polymer alternatives in corrosive service applications.
By application, the corrosive fluid handling segment holds the largest market share in 2026, encompassing the widest range of acid, caustic, and solvent heat transfer applications that represent the primary value proposition of polymer over metallic heat exchangers.
By end-user industry, the chemical processing segment holds the largest share of the overall market in 2026, as chemical plants managing hydrochloric acid, sulfuric acid, hydrofluoric acid, chlorine, and other aggressive process streams represent the most established and voluminous market for polymer heat exchanger technology.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 3.86 Billion |
| Market Size in 2026 | USD 1.74 Billion |
| Market Size in 2025 | USD 1.58 Billion |
| Market Growth Rate (2026-2036) | CAGR of 8.3% |
| Format | PDF, Excel & Cloud Portal · 277 pages |
| Dominating Region | Europe |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Material Type, Product Type, Application, End-User Industry, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: material type, product type, application, end-user industry.
The consistent and accelerating growth of the polymer heat exchangers market is fundamentally underpinned by the expanding recognition across chemical processing, pharmaceutical, semiconductor, and water treatment industries that conventional metallic heat exchangers — despite their superior thermal conductivity — fail to deliver adequate service life, maintenance economics, or product purity requirements in applications involving highly corrosive process fluids, ultra-pure water systems, and aggressive cleaning regimes. Polymer heat exchangers, engineered from fluoropolymers including polytetrafluoroethylene and polyvinylidene fluoride, polypropylene, polyether ether ketone, and advanced high-performance thermoplastics, deliver exceptional chemical resistance spanning virtually the entire pH spectrum from concentrated acids to strong caustics, inherent non-fouling surfaces minimizing cleaning frequency and downtime, and elimination of metallic ion contamination that compromises product quality in pharmaceutical and semiconductor applications. The convergence of advancing polymer processing technologies enabling fabrication of increasingly complex heat exchanger geometries, growing regulatory scrutiny of metallic contamination in food, pharmaceutical, and electronics manufacturing, and escalating operational cost pressures driving demand for longer-life, lower-maintenance thermal management solutions is creating powerful and sustained market growth momentum across multiple high-value industrial segments globally.
Polymer heat exchangers are thermal management devices constructed from engineering plastics and high-performance polymers rather than conventional metals, designed to transfer heat between fluid streams in process applications where metallic materials are unsuitable due to corrosion, contamination, fouling, weight, or cost constraints. The fundamental thermal engineering challenge of polymer heat exchangers — that most polymers exhibit thermal conductivities one to two orders of magnitude lower than metals (0.1-0.5 W/m.K for polymers versus 10-400 W/m.K for metals) — is addressed through design strategies including extremely thin wall thicknesses in hollow fiber and film configurations maximizing heat transfer area per unit volume, use of thermally enhanced polymer compounds incorporating graphite, boron nitride, or carbon fiber fillers increasing effective thermal conductivity to 1-5 W/m.K, and geometric innovations including corrugated plate designs and turbulence-promoting surface features maximizing convective heat transfer coefficients to compensate for lower material thermal conductivity. Contemporary polymer heat exchanger designs achieve heat transfer performance approaching or matching metallic alternatives in many application contexts while delivering the chemical resistance, non-fouling, weight reduction, and contamination prevention benefits that justify their application in demanding industrial environments.
The polymer heat exchanger market is segmented across distinct material platforms addressing different performance envelopes. Fluoropolymers — particularly PTFE, PVDF, PFA, and ETFE — represent the premium performance segment offering resistance to virtually all industrial chemicals including concentrated hydrofluoric acid, hot sulfuric acid, chlorine, and powerful oxidizing agents at service temperatures up to 200-260 degrees Celsius depending on specific material and pressure requirements. Polypropylene heat exchangers serve the largest volume segment of moderately corrosive applications including dilute acids, caustic solutions, and many organic solvents at temperatures below 90 degrees Celsius, offering substantially lower material costs than fluoropolymers while providing adequate chemical resistance for the majority of industrial corrosive heat transfer applications. PEEK heat exchangers address demanding applications requiring both chemical resistance and elevated temperature capability approaching 250 degrees Celsius combined with superior mechanical strength enabling higher operating pressures than other polymer alternatives. High-performance polysulfone, polyphenylene sulfide, and glass-filled specialty thermoplastic composites occupy intermediate performance positions combining moderate chemical resistance with enhanced mechanical and thermal properties enabling applications where standard polypropylene is inadequate but full fluoropolymer specifications are unnecessary.
The competitive landscape of the polymer heat exchanger market encompasses dedicated polymer heat exchanger specialists competing with thermal engineering companies that have developed polymer product lines to complement metallic exchanger portfolios. Ametek Fluoropolymer Products, GESMEX (Germany), Etched Plate Heat Exchangers, Bram-Cor (Italy), and Georg Fischer Piping Systems represent specialist manufacturers with deep application expertise in specific polymer materials and exchanger configurations. Larger thermal management companies including Alfa Laval, API Heat Transfer, and Kelvion have developed polymer heat exchanger offerings targeting crossover applications where customers specify polymer alternatives within broader thermal management procurement programs. The market is experiencing accelerating innovation in polymer composite heat exchangers — combining polymer matrices with thermally conductive fillers — that promise to substantially improve the heat transfer performance limitation that has historically constrained polymer heat exchangers to lower-duty applications, potentially opening substantially larger market segments currently served exclusively by metallic alternatives.
Report infographic
Market dynamics
4 factors across 3 forcesChemical Industry Expansion and Corrosion Management Imperatives
The primary market driver for polymer heat exchangers is the persistent and growing challenge of corrosion management in chemical processing, pharmaceutical manufacturing, and water treatment operations that consume enormous financial resources through equipment replacement, maintenance labor, production downtime, and contamination incidents attributable to metallic material degradation. The National Association of Corrosion Engineers estimates global corrosion costs at approximately USD 2.5 trillion annually — representing approximately 3.4% of global GDP — with process industry heat exchangers representing a significant proportion of corrosion-related maintenance and replacement expenditure. Polymer heat exchangers address this challenge by eliminating corrosion as a failure mode entirely in chemical resistance-limited applications, with properly specified fluoropolymer heat exchangers routinely achieving 15-20 year service lives in concentrated acid applications where metallic alternatives require replacement every 2-5 years — delivering total cost of ownership advantages that justify polymer heat exchangers' higher initial capital cost across multi-decade plant operating lifetimes. The global chemical industry's sustained capital investment in capacity expansion — particularly in Asia where large-scale chemical complexes are being constructed across China, India, and Southeast Asia — creates growing demand for polymer heat exchangers in applications including hydrochloric acid production and handling, chlor-alkali processing, fluorochemicals manufacturing, and specialty chemical synthesis where process fluid corrosivity mandates non-metallic heat transfer solutions.
Table of contents
11 chapters · 126 sections · 277 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Material Type | Fluoropolymers | — |
| By Product Type | Shell & Tube Maintain Market | Hollow fiber heat exchangers |
| By Application | Corrosive Fluid Handling | — |
| By End-User Industry | Chemical Processing | Pharmaceutical and biotechnology end-user |
By Material Type
- Fluoropolymers command approximately 45-50% of total polymer heat exchanger market revenue in 2026, reflecting their unrivaled chemical resistance profile spanning the complete spectrum of industrial acids, bases, oxidizing agents, and organic solvents, combined with broad temperature capability and the critical non-stick, non-contaminating surface properties required in pharmaceutical, semiconductor, and food processing applications.
- PTFE — the flagship fluoropolymer with service temperatures to 260 degrees Celsius and resistance to virtually all chemicals except molten alkali metals and elemental fluorine — serves the most demanding chemical processing heat transfer applications as both primary construction material for heat exchanger tubes and as lining material for metallic shell components providing composite constructions combining fluoropolymer chemical resistance with metallic structural integrity.
- PVDF offers a cost-effective alternative to PTFE for applications not requiring full fluoropolymer resistance, with superior weldability enabling more complex fabrication geometries and better mechanical properties at moderate temperatures, while PFA and ETFE address specific application requirements where PTFE's processing limitations restrict geometric complexity.
- The polypropylene segment represents the largest volume material category by number of installed units, serving the broad middle ground of moderately corrosive applications where fluoropolymer performance is not required but metallic corrosion remains a significant concern — including dilute acid pickling systems, caustic scrubber systems, and swimming pool and aquaculture water treatment applications where polypropylene's cost-performance ratio is highly competitive.
By Product Type
- The shell and tube product type accounts for approximately 38-42% of polymer heat exchanger market revenue in 2026, benefiting from engineers' familiarity with shell-and-tube thermal and hydraulic design methodologies that enable straightforward specification of polymer alternatives as direct replacements for metallic shell-and-tube exchangers in corrosive service upgrades.
- Polymer shell-and-tube heat exchangers retain the fundamental configuration of tube bundles contained within cylindrical shells, with PTFE or polypropylene tubes replacing metallic tubes while shell components may be constructed from polymer, fiber-reinforced plastic, or rubber-lined carbon steel depending on application requirements and economic optimization.
- The plate heat exchanger segment demonstrates strong growth momentum at approximately 10-12% CAGR, driven by advances in polymer plate forming technologies enabling fabrication of corrugated heat transfer plates with geometric complexity approaching metallic plate designs, combined with the inherent compactness and high heat transfer efficiency of plate configurations that are particularly valuable in space-constrained process environments.
- Hollow fiber heat exchangers represent the fastest-growing product type at approximately 13-15% CAGR, driven by semiconductor and pharmaceutical industry demand for ultra-high purity, high-surface-area compact heat exchangers where hollow fiber PTFE and PFA constructions provide unmatched performance across critical specifications including chemical purity, particle generation, and heat transfer density required for advanced manufacturing processes.
By Application
- The corrosive fluid handling application segment represents approximately 42-46% of total polymer heat exchanger market in 2026, encompassing the vast range of chemical processing, metal surface treatment, and industrial manufacturing applications where process fluids including mineral acids, caustic solutions, oxidizing agents, and aggressive organic solvents demand non-metallic heat transfer surfaces for reliable long-term operation.
- Hydrochloric acid heating and cooling represents one of the largest single application categories, with polymer heat exchangers serving steel pickling operations, chlor-alkali production facilities, and HCl synthesis and purification systems where acid concentrations and temperatures create service conditions that defeat even highly alloyed metallic materials at economic maintenance intervals.
- Sulfuric acid heat exchangers in fertilizer production, petroleum refining alkylation units, and battery acid manufacturing represent another major application category where polymer heat exchangers provide compelling lifecycle economics compared to tantalum and exotic alloy alternatives historically specified for concentrated acid service.
- The waste heat recovery application is experiencing significant growth momentum at approximately 11-13% CAGR, driven by industrial energy efficiency imperatives creating demand for polymer heat exchangers capable of recovering low-grade heat from corrosive flue gases, acidic condensates, and contaminated process streams previously vented or cooled without energy recovery due to the unavailability of cost-effective corrosion-resistant heat transfer technology.
By End-User Industry
- The chemical processing end-user segment commands approximately 35-40% of polymer heat exchanger market revenue in 2026, reflecting the chemical industry's position as both the earliest adopter of polymer heat exchanger technology and the end-user sector with the broadest range of corrosive heat transfer applications driving sustained and growing polymer heat exchanger demand.
- Chemical plants managing inorganic acids including hydrochloric, sulfuric, nitric, hydrofluoric, and phosphoric acid across production, purification, storage, and distribution operations require polymer heat exchangers throughout thermal management systems where metallic materials would corrode rapidly creating contamination, safety, and operational reliability concerns.
- The pharmaceutical and biotechnology end-user segment represents the fastest-growing market at approximately 11-13% CAGR, driven by the pharmaceutical industry's strict requirements for materials of construction that prevent metallic ion contamination of drug substance and drug product streams, combined with the aggressive cleaning and sterilization regimes — including CIP/SIP with strong caustic and acidic cleaning agents — that create cyclic corrosive stress exceeding the capability of even high-grade stainless steel in some critical applications.
- The semiconductor and electronics end-user segment commands premium pricing through the stringent purity and particle generation specifications mandated for heat exchangers contacting ultra-pure water, high-purity chemicals, and process gases in advanced semiconductor fabrication, with hollow fiber PTFE and PFA heat exchangers serving as standard equipment in 300mm wafer fab chemical distribution and temperature control systems at leading manufacturers including TSMC, Samsung, and Intel.
Geographic analysis
Europe
Europe holds approximately 32-36% of the global polymer heat exchanger market in 2026, supported by the continent's dense concentration of chemical, pharmaceutical, and specialty materials manufacturing industries that collectively represent the most established and technically sophisticated end-user base for advanced polymer heat exchanger applications globally. Germany, the Netherlands, Belgium, and France host some of the world's largest chemical complexes — BASF's Ludwigshafen Verbund, Shell's Pernis refinery, INEOS's Antwerp operations, and Solvay's multiple European sites — that operate extensive networks of corrosive fluid heat exchangers where polymer alternatives have achieved substantial market penetration over decades of application development. European pharmaceutical manufacturing centers in Switzerland, Germany, Ireland, and Italy apply stringent materials of construction standards mandating polymer heat exchangers in critical contact applications involving drug substances, with GMP compliance requirements creating clear specification frameworks that favor polymer materials over metallic alternatives in contamination-sensitive heat transfer services. The European chemical industry's ongoing transition toward renewable feedstocks, bio-based chemical production, and green chemistry processes frequently introduces new corrosive process streams and cleaning regimes where conventional metallic heat exchanger materials are inadequate, creating continuous demand pull for polymer heat exchanger solutions capable of handling novel chemical environments associated with green chemistry manufacturing.
Asia-Pacific
Asia-Pacific demonstrates the highest regional growth rate at approximately 10-12% CAGR, propelled by the simultaneous expansion of multiple high-value end-user industries that represent core polymer heat exchanger markets across China, South Korea, Taiwan, and India. Taiwan and South Korea's semiconductor industries — home to TSMC, Samsung Foundry, SK Hynix, and Micron's expanding Asian operations — represent the most technically demanding and economically valuable polymer heat exchanger application cluster in the Asia-Pacific region, with next-generation fab construction programs creating consistent demand for hollow fiber PTFE and PFA heat exchangers meeting the most stringent purity specifications in commercial heat exchanger manufacturing. China's massive chemical industry expansion — the largest in the world by output value and continuing to grow rapidly through both capacity expansion and import substitution programs — creates broad-based demand for polymer heat exchangers in acid handling, chlor-alkali processing, and specialty chemical manufacturing applications, with domestic Chinese polymer heat exchanger manufacturers including Zhejiang Jiansheng and related companies developing competitive offerings for the cost-sensitive middle market while international specialists capture premium corrosion-resistant and high-purity segments. India's pharmaceutical industry — the world's largest supplier of generic medicines by volume and increasingly serving regulated markets in North America and Europe with quality requirements demanding GMP-compliant polymer materials — is driving growing polymer heat exchanger adoption in API manufacturing and formulation facilities upgrading to international quality standards.
Competitive landscape
- AMETEK Inc.
- GESMEX GmbH
- Bram-Cor SpA
- Alfa Laval AB
- Kelvion Holding GmbH
- Plastic Heat Exchangers, Exergy LLC
Frequently asked questions
The global polymer heat exchangers market is expected to grow from USD 1.74 billion in 2026 to USD 3.86 billion by 2036.
Cite this report
Meticulous Research. (2026). Polymer Heat Exchangers Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRSE - 1041834). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/polymer-heat-exchangers-market-6517