Polymer Additive Manufacturing Market (2024-2031)
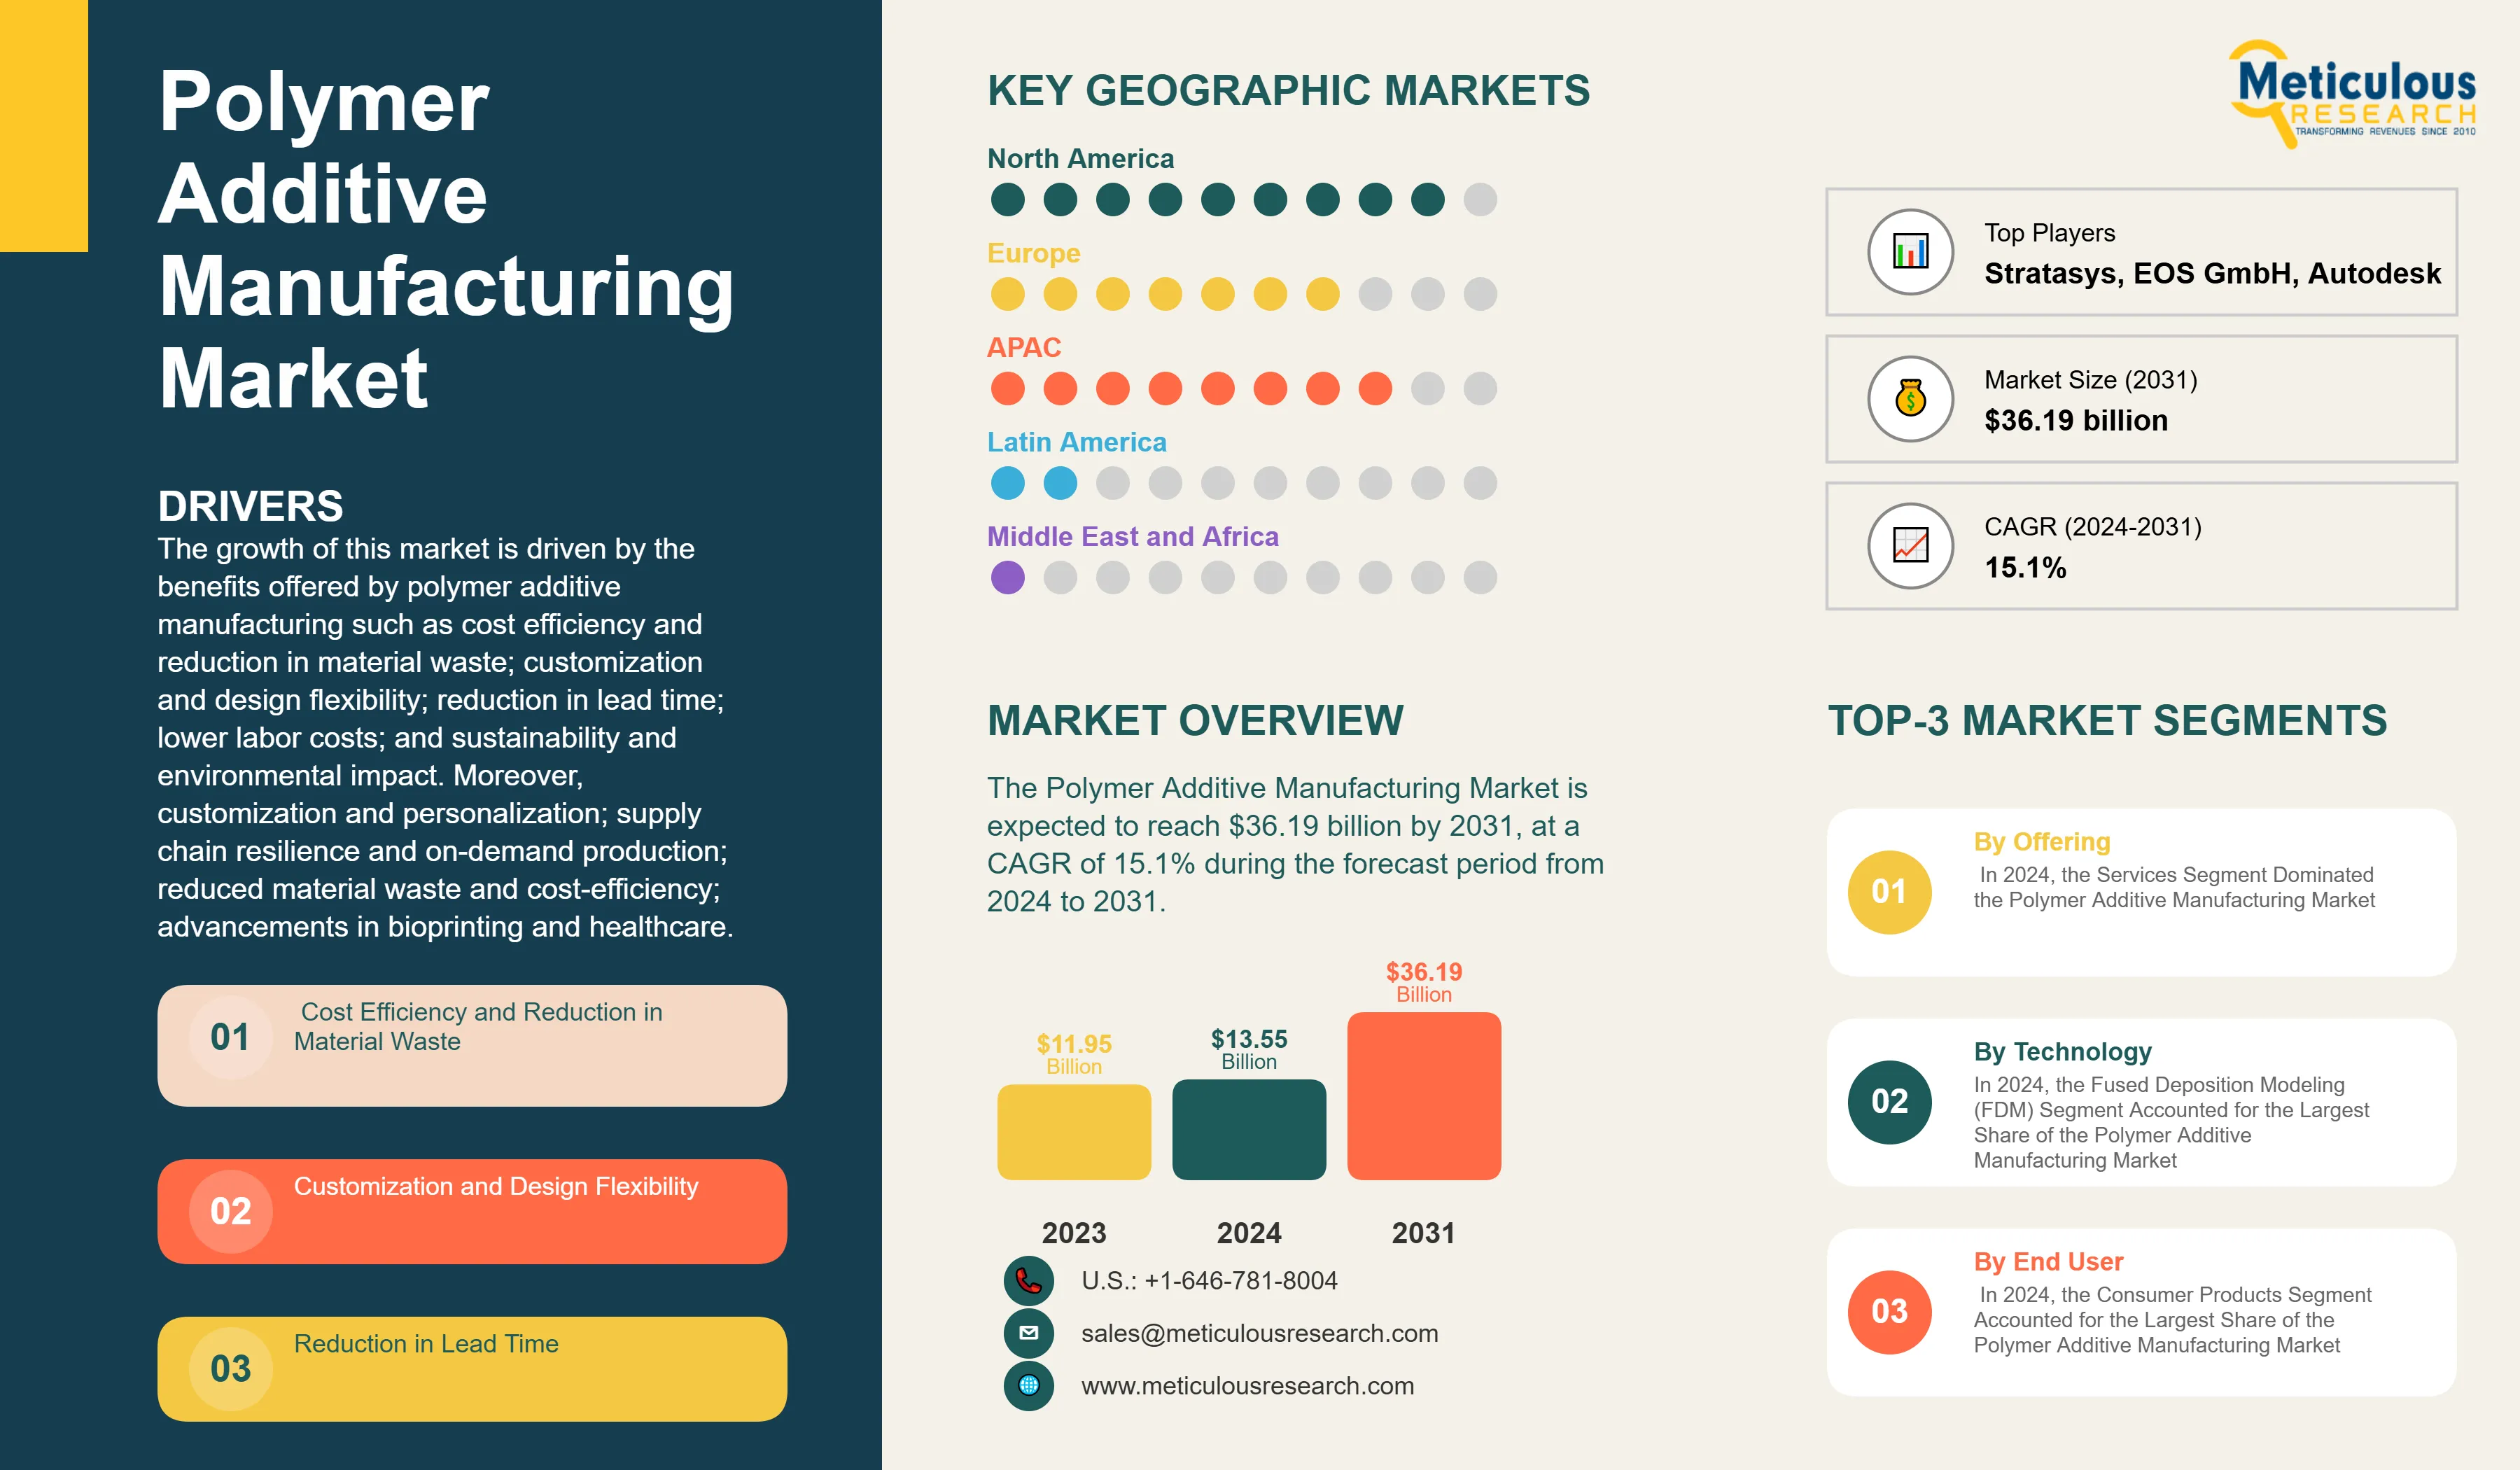
The Polymer Additive Manufacturing Market was valued at $11.95 billion in 2023. This market is expected to reach $36.19 billion by 2031 from an estimated $13.55 billion in 2024, at a CAGR of 15.1% during the forecast period from 2024 to 2031. Polymer Additive Manufacturing Size & Forecast The growth
- Published
- Jan 2025
- Pages
- 199
- Format
- PDF + Excel
- Report ID
- MRSE - 1041445
- Base year
- 2024
- 2023 · HISTORICAL
- $11.95B
- 2031
- $36.19B
- CAGR 2024–2031
- 15.1%
2023 baseline · 2024–2031 forecast at 15.1% CAGR · hover a bar for the value
Key highlights
By Offering: In 2024, the Services Segment Dominated the Polymer Additive Manufacturing Market
By Technology: In 2024, the Fused Deposition Modeling (FDM) Segment Accounted for the Largest Share of the Polymer Additive Manufacturing Market
By End User: In 2024, the Consumer Products Segment Accounted for the Largest Share of the Polymer Additive Manufacturing Market
By Geography: North America Dominated the Polymer Additive Manufacturing Market in 2024
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 199 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2024 |
| CAGR (Value) | 15.1% |
| Market Size in 2024 | USD 13.55 billion |
| Market Size in 2031 | USD 36.19 Billion |
| Segments Covered | by Offering · Services · Hardware · Software · Materials · Photopolymers (Resins) · Polylactic Acid (PLA) · Polyamide (Nylon) · Acrylonitrile Butadiene Styrene (ABS) · Polycarbonate (PC) · Thermoplastic Polyurethane (TPU) · Other Polymers Materials · by Technology · Fused Deposition Modeling (FDM) · Selective Laser Sintering (SLS) · Stereolithography (SLA) · PolyJet · Digital Light Processing (DLP) · Multi Jet Fusion · Binder Jetting · Other Polymer Technologies · by End User · Consumer Products · Healthcare · Automotive · General Manufacturing · Electronics & Semiconductors · Aerospace & Defense · Chemicals & Materials · Energy and Oil & Gas · Other End Users |
| Countries Covered | North America (U.S., Canada), Asia-Pacific (China, Japan, India, and Rest of Asia-Pacific), Europe (Germany, U.K., France, Italy, Spain, and Rest of Europe), the Middle East & Africa, and Latin America. |
| Key Companies | Stratasys, Ltd. (U.S.), 3D Systems Corporation (U.S.), EOS GmbH (Germany), Materialise NV (Belgium), voxeljet AG (Germany), Markforged Holding Corporation (U.S.), Proto Labs, Inc. (U.S.), Autodesk, Inc. (U.S.), 3Dceram (France), Dassault Systemes SE (France), Formlabs Inc. (U.S.), and Shapeways Holdings, Inc. (U.S.). |
Report overview
Segments covered: offering, technology, end user. Regions: North America, Asia-Pacific, Europe.
The growth of this market is driven by the benefits offered by polymer additive manufacturing such as cost efficiency and reduction in material waste; customization and design flexibility; reduction in lead time; lower labor costs; and sustainability and environmental impact. Moreover, customization and personalization; supply chain resilience and on-demand production; reduced material waste and cost-efficiency; advancements in bioprinting and healthcare; and collaborations and industry partnerships are expected to create market growth opportunities.
Report infographic
Market dynamics
3 factors across 3 forcesCost Efficiency and Reduction in Material Waste
One of the most prominent drivers of the polymer additive manufacturing (AM) market is the ability to reduce manufacturing costs and material waste. In traditional manufacturing processes like subtractive manufacturing, the material is cut away from a larger block, often resulting in significant material waste. On the other hand, additive manufacturing builds parts layer by layer from digital files, minimizing waste by only using the exact amount of material required for the object. This not only reduces material costs but also provides cost-effective low-volume production for industries with highly customized parts.
The cost savings are especially apparent when it comes to manufacturing complex geometries. 3D printing technologies allow companies to produce highly intricate designs without requiring expensive molds, tooling, or time-consuming assembly. As a result, even small manufacturers can afford to produce parts previously only feasible for large-scale manufacturers, lowering the barriers to entry for many industries.
A report by Deloitte titled "3D Printing and the Future of Manufacturing" (2020) highlights that companies using additive manufacturing to replace traditional manufacturing techniques have been able to reduce material costs by up to 70% in certain applications. This is especially true in industries like automotive and aerospace, where additive manufacturing allows for the creation of complex parts with optimized material usage, ultimately reducing production costs.
Additionally, polymer additive manufacturing offers considerable savings in terms of tooling costs. A report by Wohlers Associates states that 3D printing technologies have the potential to reduce tooling costs for part production by up to 90% because there is no need for traditional molds or dies.
Table of contents
11 chapters · 117 sections · 199 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Offering | Services | — |
| By End User | Consumer products | Automotive |
By Offering
- The Services Segment Dominated the Polymer Additive Manufacturing Market
- The services segment accounted for the largest share of the polymer additive manufacturing market.
- The large market share of this segment is primarily attributed to the increased need for specialized, customized products in industries like aerospace, healthcare, and automotive, along with the ability to outsource production without significant capital investment.
- Moreover, this segment is also projected to register the highest CAGR during the forecast period of 2024–2031.
- This growth is driven by the rise of end-to-end service providers and increased accessibility of 3D printing technologies.
By End User
- The Automotive Segment to Witness Rapid Growth During the Forecast Period
- The consumer products segment accounted for the largest share of the polymer additive manufacturing market.
- However, the automotive segment is projected to register the highest CAGR of 17.6% during the forecast period of 2024–2031.
- The growth of polymer additive manufacturing in the automotive sector is expanding rapidly, driven by its ability to produce lightweight, cost-effective, and customizable components.
- Polymer-based 3D printing is increasingly utilized in automotive applications, from prototyping and tooling to manufacturing functional parts, owing to advancements in material performance and printing technologies.
- Key growth factors include the industry's focus on lightweighting to improve fuel efficiency and meet regulatory requirements for lower emissions.
- Polymers such as nylon, polycarbonate, and high-performance thermoplastics like PEEK and PEKK offer excellent strength-to-weight ratios, making them ideal for replacing metal components in non-load-bearing applications.
- Customization is another critical driver, as polymer 3D printing enables the production of unique and intricate designs tailored to specific vehicles or customer preferences, enhancing product differentiation and consumer satisfaction.
- The shift toward electric vehicles (EVs) is accelerating the adoption of polymer additive manufacturing.
- Lightweight polymer components contribute to increased battery efficiency and overall vehicle range, which are critical factors in EV performance.
- Additionally, polymer-based AM is cost-effective for low-volume production runs, making it a valuable tool for producing components for limited-edition or prototype EVs.
Geographic analysis
North America
Largest shareIn 2024, North America accounted for the largest share of the global polymer additive manufacturing market. The large share of North America in the polymer additive manufacturing market is primarily attributed to technological innovation, strong infrastructure, significant R&D investments, government support, and growing demand for customization. Key factors include cross-border collaboration, rising adoption in sectors like aerospace and healthcare, and a supportive regulatory environment. North America Dominated the Polymer Additive Manufacturing Market in 2024
Asia-Pacific
Fastest growthHowever, Asia-Pacific is expected to record the highest CAGR during the forecast period due to industrialization, digital transformation, and growing demand for customization and sustainable solutions. Key drivers include government investments, Industry 4.0 initiatives, and adoption in sectors like automotive, aerospace, electronics, and healthcare.
Competitive landscape
- November 2024
Stratasys announced an enhancement of GrabCAD Print and GrabCAD Print Pro software.
- November 2024
EOS launched EOS P3 NEXT, a polymer additive manufacturing 3D printer, for enhancing the productivity and efficiency of polymer printing.
- June 2024
Stratasys partnered with AM Craft (Latvia) for driving growth in 3D part manufacturing for aviation.
- October 2023
3D Systems launched a new printer and wax material for jewelry pattern manufacturing. The products are MJP 300W and VisiJet Wax Jewel Ruby. The printer was made with enhanced productivity and customizable design features.
- June 2023
3D Systems and SWANY Co. Ltd (Japan) collaborated to promote the adoption of large-format pellet extrusion 3D printing in Japan. SWANY is opening a new demo center that will include a 3D Systems EXT 1070 Titan Pellet printer—the first of its kind in Japan.
- Stratasys, Ltd. (U.S.)
- 3D Systems Corporation (U.S.)
- EOS GmbH · Germany
- Materialise NV · Belgium
- Markforged Holding Corporation (U.S.)
- Proto Labs, Inc. (U.S.)
- Autodesk, Inc. (U.S.)
- 3Dceram · France
- Dassault Systemes SE · France
- Formlabs Inc. (U.S.)
- Shapeways Holdings, Inc. (U.S.)
Frequently asked questions
The global polymer additive manufacturing market size was valued at $11.95 billion in 2023.
Cite this report
Meticulous Research. (2025). Polymer Additive Manufacturing Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRSE - 1041445). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/polymer-additive-manufacturing-market-6128