Nuclear Robotics Market
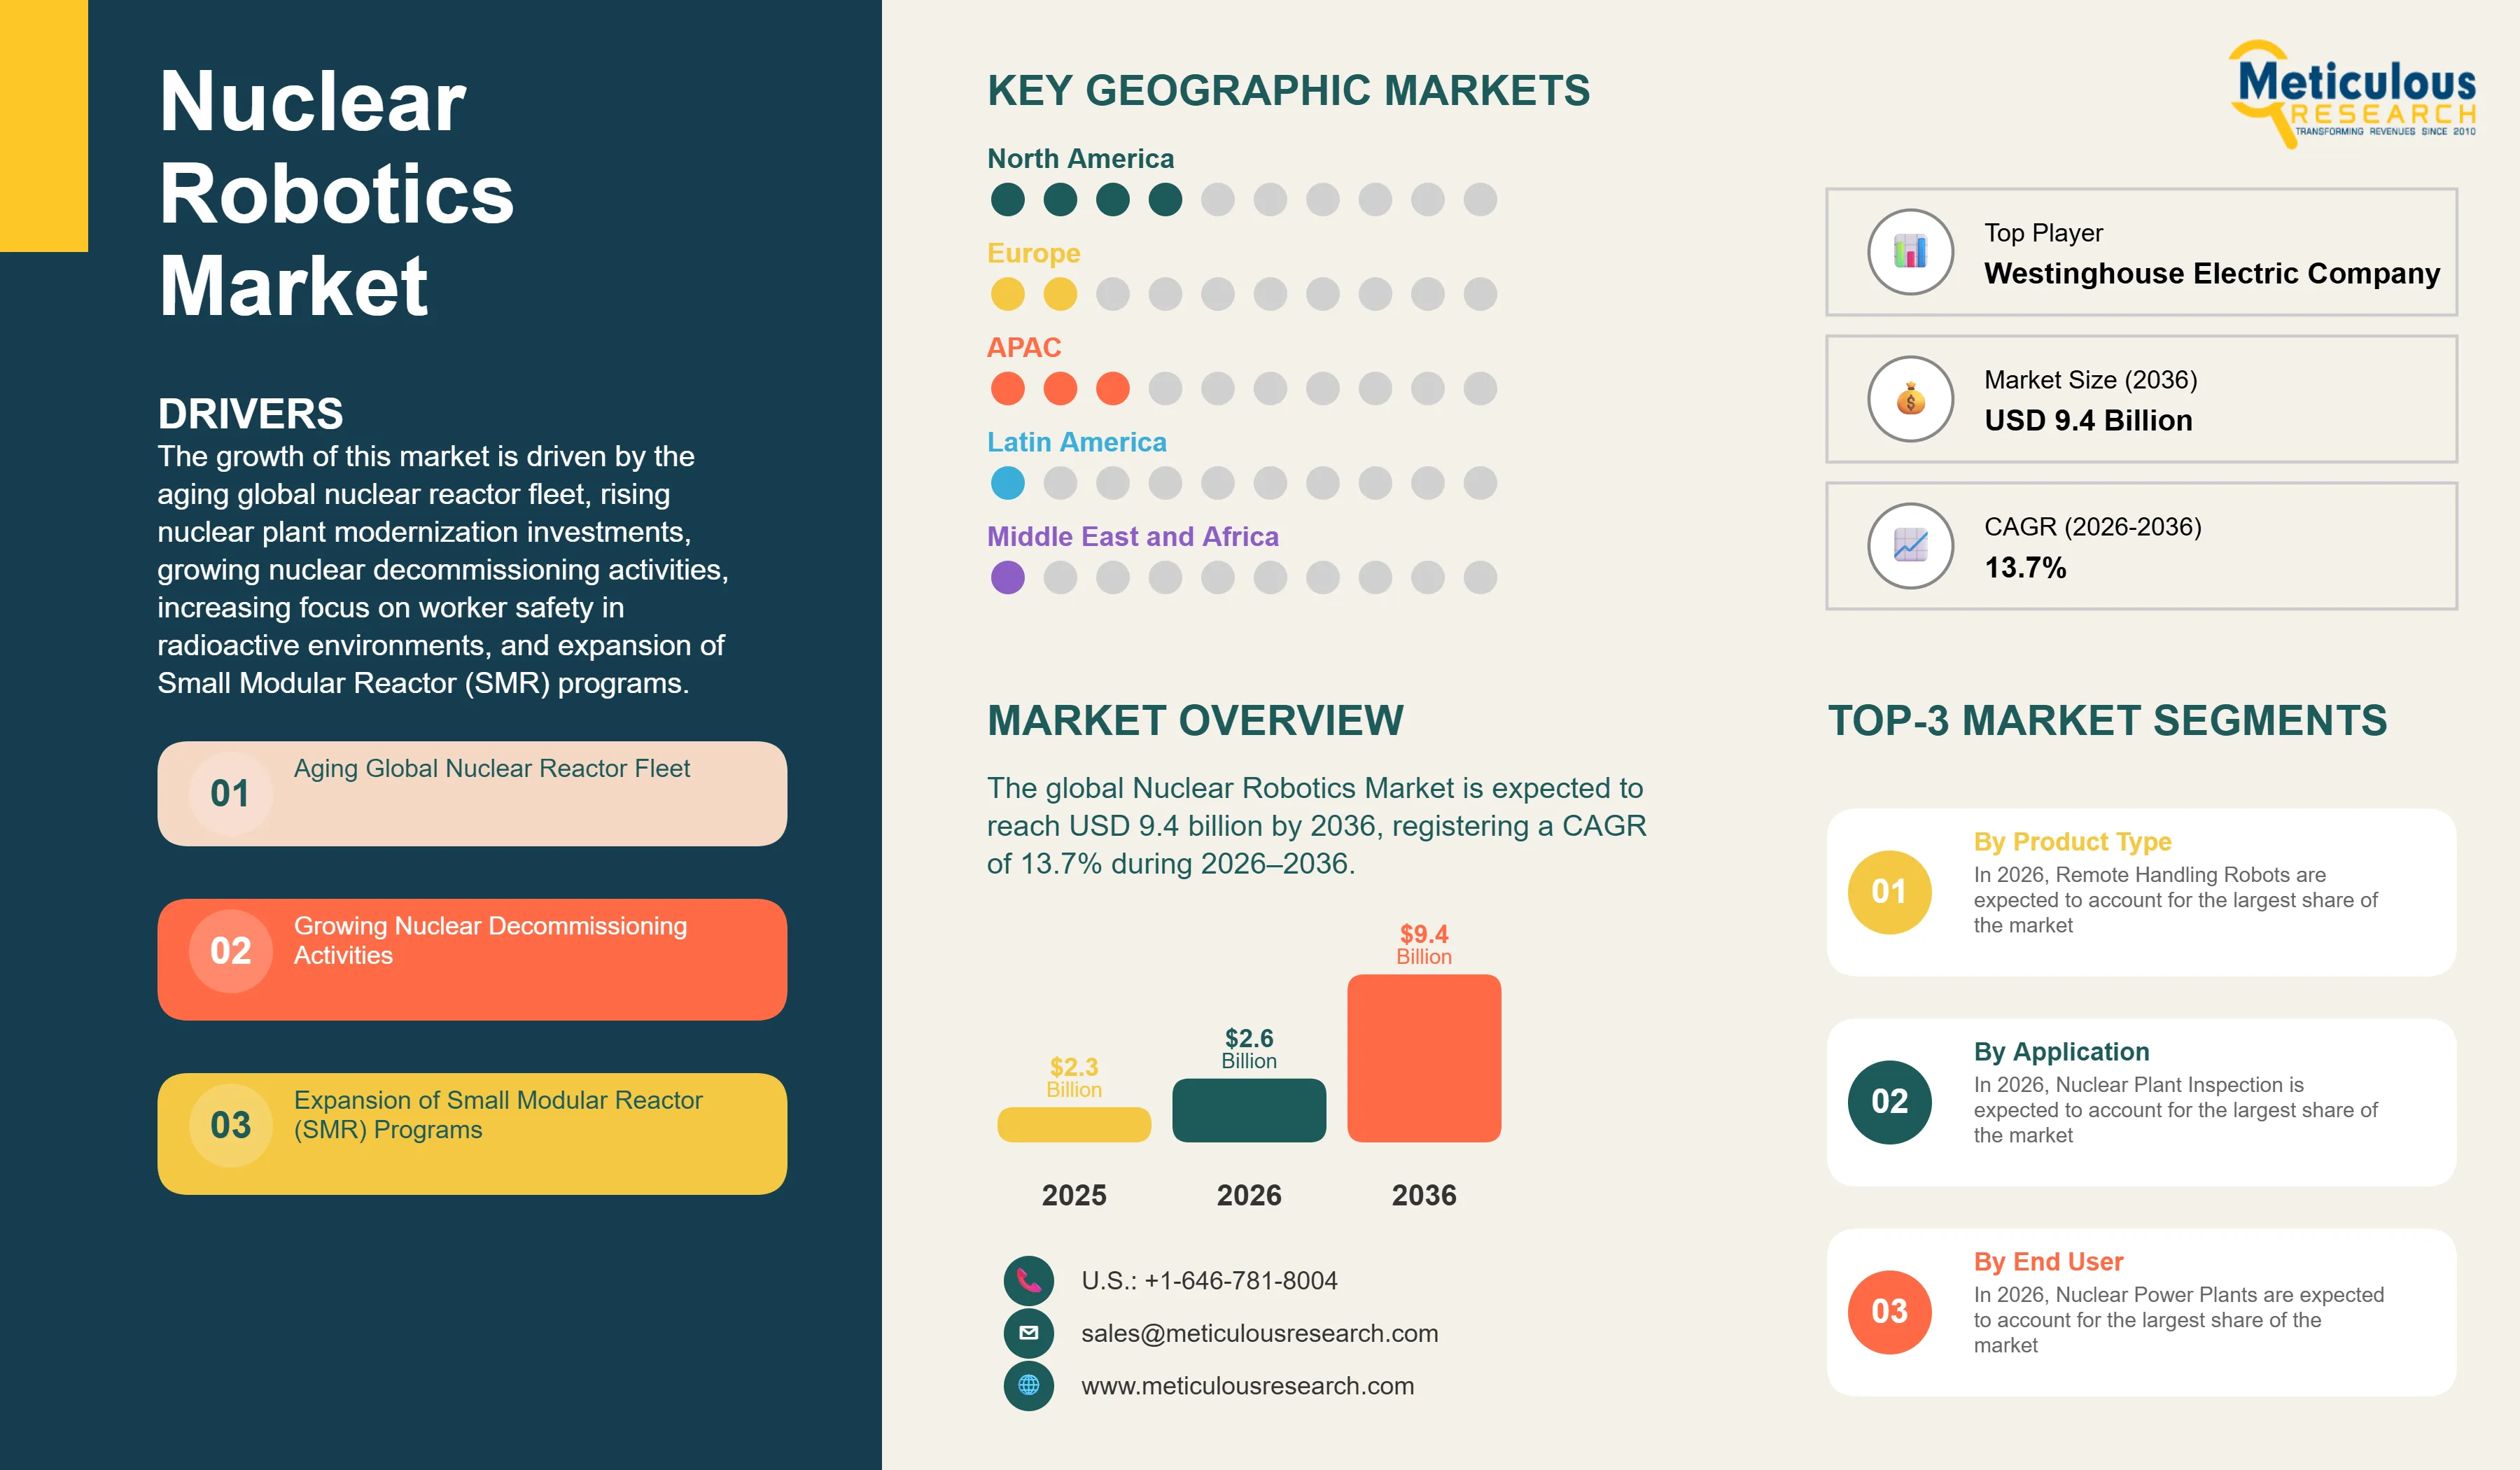
The global Nuclear Robotics Market was valued at USD 2.3 billion in 2025 and is projected to reach USD 2.6 billion in 2026. The market is expected to reach USD 9.4 billion by 2036, registering a CAGR of 13.7% during the forecast period (2026-2036).
- Published
- Aug 2026
- Pages
- 288
- Format
- PDF + Excel
- Report ID
- MR-2128
- Base year
- 2025
- 2023 · HISTORICAL
- $65.00B
- 2036
- $9.40B
- CAGR 2026–2036
- 13.7%
2023–2025 baseline · 2026–2036 forecast at 13.7% CAGR · hover a bar for the value
Key highlights
The global Nuclear Robotics Market is projected to reach USD 9.4 billion by 2036, driven by the aging global nuclear reactor fleet, rising nuclear decommissioning activity, and growing emphasis on worker safety in radioactive environments.
North America is expected to account for the largest market share in 2026, while Asia-Pacific is projected to register the fastest growth during the forecast period.
By product, Remote Handling Robots are expected to account for the largest market share, whereas Inspection Robots are projected to witness the fastest growth through 2036.
By operation mode, Semi-Autonomous Robotics is expected to dominate the market, while Fully Autonomous Robotics is projected to register the highest CAGR during the forecast period.
Growing investment in nuclear plant life extension, decommissioning, and Small Modular Reactor (SMR) programs is increasing demand for radiation-hardened and remotely operated robotic systems.
Rising interest in fusion energy research and AI-enabled autonomous inspection technologies is expected to create significant long-term growth opportunities.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 13.7% |
| Format | PDF, Excel & Cloud Portal · 288 pages |
| Market Size (Value) in 2026 | USD 2.6 Billion |
| Market Size (Value) in 2036 | USD 9.4 Billion |
| Segments Covered | By Product: Inspection Robots, Remote Handling Robots, Mobile Robots, Aerial Robots (UAVs), Underwater Robots, Robotic Arms & Manipulators, Software & Control Platforms, Services. By Operation Mode: Teleoperated Robotics, Semi-Autonomous Robotics, Fully Autonomous Robotics. By Application: Nuclear Plant Inspection, Nuclear Maintenance & Repair, Radioactive Waste Management, Nuclear Decommissioning, Fuel Handling, Emergency Response, Nuclear Research Facilities, Fusion Energy Facilities. By End User: Nuclear Power Plants, Nuclear Fuel Cycle Facilities, Radioactive Waste Management Facilities, Nuclear Research Laboratories, Defense Nuclear Facilities, Fusion Research Facilities. By Reactor Type: Pressurized Water Reactors (PWRs), Boiling Water Reactors (BWRs), Pressurized Heavy Water Reactors (PHWRs), Gas-Cooled Reactors, Fast Reactors, Small Modular Reactors (SMRs), Fusion Reactors. |
| Countries Covered | North America: U.S., Canada. Europe: France, U.K., Germany, Sweden, Finland, Rest of Europe. Asia-Pacific: China, Japan, South Korea, India, Australia, Rest of Asia-Pacific. Latin America: Brazil, Mexico, Argentina, Rest of Latin America. Middle East & Africa: UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa. |
| Key Companies | Westinghouse Electric Company, GE Vernova, Framatome, AtkinsRéalis, Toshiba Energy Systems & Solutions Corporation, Hitachi Ltd., FANUC Corporation, KUKA AG, ABB Ltd., Boston Dynamics, OC Robotics Ltd., QinetiQ Group plc, Veolia Nuclear Solutions, Kurion (Veolia), and Oxford Technologies Ltd. |
Report overview
Segments covered: product, operation mode, application, end user, reactor type.
The Nuclear Robotics Market comprises robotic systems, remote manipulators, and autonomous platforms designed to perform inspection, maintenance, decommissioning, and waste-handling tasks in radioactive and hazardous nuclear environments where direct human access is limited or unsafe. These systems include inspection robots, remote handling robots, mobile robots, aerial robots (UAVs), underwater robots, robotic arms and manipulators, and associated software and control platforms, deployed across nuclear power plants, fuel cycle facilities, waste management sites, research laboratories, and fusion facilities to reduce radiation exposure to personnel and improve operational efficiency.
The market is witnessing steady growth as the global nuclear fleet continues to age. According to the World Nuclear Industry Status Report 2025, the world's 413 operating nuclear reactors have an average age of around 32 years, and IAEA data indicates that more than two-thirds of reactors currently in service are over 30 years old. As reactors approach the end of their operating licenses, utilities are increasingly relying on robotic inspection and remote handling systems to support life-extension programs, in-service inspection, and eventual decommissioning without exposing workers to radiological hazards.
Nuclear decommissioning is emerging as a major growth avenue for the market. As of February 2026, 220 nuclear reactors had been permanently shut down worldwide, and the IAEA projects that between 12% and 25% of 2020-level nuclear generating capacity could be retired by 2030. At the same time, the industry is expanding: 74 reactors were under construction globally as of February 2026, led by China with 37 units, alongside growing momentum behind Small Modular Reactors (SMRs), with the IAEA cataloguing more than 80 active SMR designs and over 125 SMR projects in planning or construction worldwide. Global investment in nuclear energy reached approximately USD 65 billion in 2023, nearly double the level of a decade earlier, according to the IEA, underscoring the scale of capital flowing into new build, modernization, and decommissioning programs that collectively expand the addressable base for nuclear robotics.
Market dynamics
16 factors across 5 forcesAging Global Nuclear Reactor Fleet
The advancing age of the global nuclear reactor fleet is one of the primary factors driving demand for nuclear robotics. With an average reactor age of approximately 32 years and a large share of the fleet exceeding 30 years of service, utilities are increasingly deploying robotic inspection and remote handling systems to assess structural integrity, detect corrosion and material degradation, and support license renewal and life-extension programs without exposing personnel to radiation.
Rising Nuclear Plant Modernization Investments
Growing capital investment in nuclear plant modernization is expanding demand for advanced robotic systems. Global investment in nuclear energy rose to approximately USD 65 billion in 2023, nearly double the level of a decade earlier, according to the IEA, as utilities and governments prioritize upgrading instrumentation, control systems, and safety infrastructure. Robotic platforms are increasingly used for non-intrusive inspection and maintenance activities that minimize plant downtime during modernization projects.
Growing Nuclear Decommissioning Activities
The rising pace of nuclear decommissioning is a significant growth driver for the market. As of February 2026, 220 nuclear reactors had been permanently shut down worldwide, and the IAEA projects that between 12% and 25% of 2020-level nuclear generating capacity could be retired by 2030. Decommissioning work, including dismantling, remote cutting, and decontamination, requires extensive use of remote handling robots and teleoperated systems to safely manage highly radioactive components and waste streams.
Increasing Focus on Worker Safety in Radioactive Environments
Nuclear operators and regulators are placing growing emphasis on minimizing worker exposure to radiation and hazardous conditions. Robotic systems allow inspection, maintenance, and material handling tasks in high-radiation zones to be performed remotely, supporting compliance with occupational radiation exposure limits set by national regulators and the IAEA while improving overall operational safety across nuclear facilities.
Expansion of Small Modular Reactor (SMR) Programs
The rapid global expansion of Small Modular Reactor programs is creating new demand for nuclear robotics. The IAEA catalogues more than 80 active SMR designs under development worldwide, with over 125 SMR projects currently in the planning or construction stage across countries including the United States, Canada, the United Kingdom, China, and Russia. As SMR fleets scale toward commercial deployment, factory-based manufacturing, modular assembly, and distributed operations are expected to increase reliance on standardized robotic inspection and maintenance solutions.
Table of contents
13 chapters · 188 sections · 288 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product | Remote Handling Robots | Inspection Robots |
| By Operation Mode | Semi-Autonomous Robotics | Fully Autonomous Robotics |
| By Application | Nuclear Plant Inspection | Nuclear Decommissioning |
| By End User | Nuclear Power Plants | Fusion Research Facilities |
| By Reactor Type | Pressurized Water Reactors (PWRs) | Small Modular Reactors (SMRs) |
By Product
- The Remote Handling Robots segment is expected to account for the largest share of the global Nuclear Robotics Market, supported by their extensive use in precision handling of radioactive materials and components across maintenance, refueling, and decommissioning operations.
- However, the Inspection Robots segment is projected to register the fastest growth during the forecast period, driven by increasing adoption of AI-enabled autonomous inspection systems for reactor vessels, piping, and containment structures.
By Operation Mode
- Semi-Autonomous Robotics is expected to account for the largest market share, reflecting nuclear operators' preference for combining automated task execution with direct operator oversight for safety-critical operations.
- However, Fully Autonomous Robotics is projected to register the highest CAGR during the forecast period, owing to advances in AI, machine vision, and autonomous navigation technologies that are steadily expanding the scope of unsupervised robotic operation in nuclear environments.
By Application
- Nuclear Plant Inspection is expected to account for the largest market share, driven by routine in-service inspection requirements across the world's operating reactor fleet.
- However, Nuclear Decommissioning is projected to register the highest CAGR during the forecast period, supported by the rising number of reactors reaching end-of-life and the growing global backlog of decommissioning projects.
By End User
- Nuclear Power Plants are expected to account for the largest market share, given the scale of the world's operating and under-construction reactor fleet.
- However, Fusion Research Facilities are projected to register the highest CAGR during the forecast period, driven by rising global investment in public and privately funded fusion energy programs requiring specialized remote handling capabilities.
By Reactor Type
- Pressurized Water Reactors (PWRs) are expected to account for the largest market share, reflecting their position as the most widely deployed reactor technology in the global nuclear fleet.
- However, Small Modular Reactors (SMRs) are projected to register the highest CAGR during the forecast period, supported by the more than 80 active SMR designs under development and the growing number of SMR projects advancing toward construction and commercial deployment worldwide.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global Nuclear Robotics Market. The region's leadership is supported by its long-established nuclear infrastructure, with the U.S. Department of Energy reporting 93 operating nuclear reactors in the United States, alongside an active pipeline of decommissioning projects and growing government investment in nuclear robotics research and worker safety programs. Well-established robotics suppliers headquartered in the region further reinforce North America's position in the market.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is projected to register the highest CAGR during the forecast period. Growth in the region is driven by an expanding pipeline of new reactor construction, with 74 reactors under construction worldwide as of February 2026, of which China alone accounted for 37 units and India for 6, according to IAEA data. India's Shanti Act, passed in 2025, further supports this momentum by targeting an expansion of the country's nuclear capacity to 100 GW by 2047, up from approximately 7.5 GW currently. Rising investment in reactor inspection, maintenance automation, and emerging SMR programs across China, Japan, South Korea, and India is expected to sustain rapid growth in demand for nuclear robotics across the region.
Competitive landscape
The global Nuclear Robotics Market is moderately fragmented, with competition among established industrial robotics manufacturers, specialized nuclear remote handling providers, nuclear equipment OEMs, and engineering, procurement, and construction (EPC) contractors. Companies compete primarily on radiation tolerance, precision handling capability, autonomy, system reliability, regulatory qualification, and integration with digital twin and AI-based control platforms.
Leading market participants are investing in AI-enabled autonomous inspection systems, radiation-hardened robotic platforms, and digital twin integration to support nuclear plant life extension, decommissioning, and emerging SMR and fusion energy applications. Strategic partnerships with nuclear utilities and research organizations, capacity expansion, and continued R&D investment in remote handling and machine vision technologies remain key strategies adopted by major vendors. Companies are also expanding service offerings, including integration, maintenance, and training support, to address the growing complexity of nuclear robotics deployments.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Nuclear Robotics Market. The key players profiled in the report include Westinghouse Electric Company, GE Vernova, Framatome, AtkinsRéalis, Toshiba Energy Systems & Solutions Corporation, Hitachi, Ltd., FANUC Corporation, KUKA AG, ABB Ltd., Boston Dynamics, OC Robotics Ltd., QinetiQ Group plc, Veolia Nuclear Solutions, Kurion (Veolia), and Oxford Technologies Ltd.
- Westinghouse Electric Company
- GE Vernova
- Framatome
- AtkinsRéalis
- Toshiba Energy Systems & Solutions Corporation
- Hitachi Ltd.
- FANUC Corporation
- KUKA AG
- ABB Ltd.
- Boston Dynamics
- OC Robotics Ltd.
- QinetiQ Group plc
- Veolia Nuclear Solutions
- Kurion · Veolia
- Oxford Technologies Ltd
Frequently asked questions
The global Nuclear Robotics Market is estimated at USD 2.6 billion in 2026.
Cite this report
Meticulous Research. (2026). Nuclear Robotics Market - Global Opportunity Analysis and Industry Forecast to 2036 (Report No. MR-2128). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/nuclear-robotics-market-6811