Liquid Biopsy Market (2026-2036)
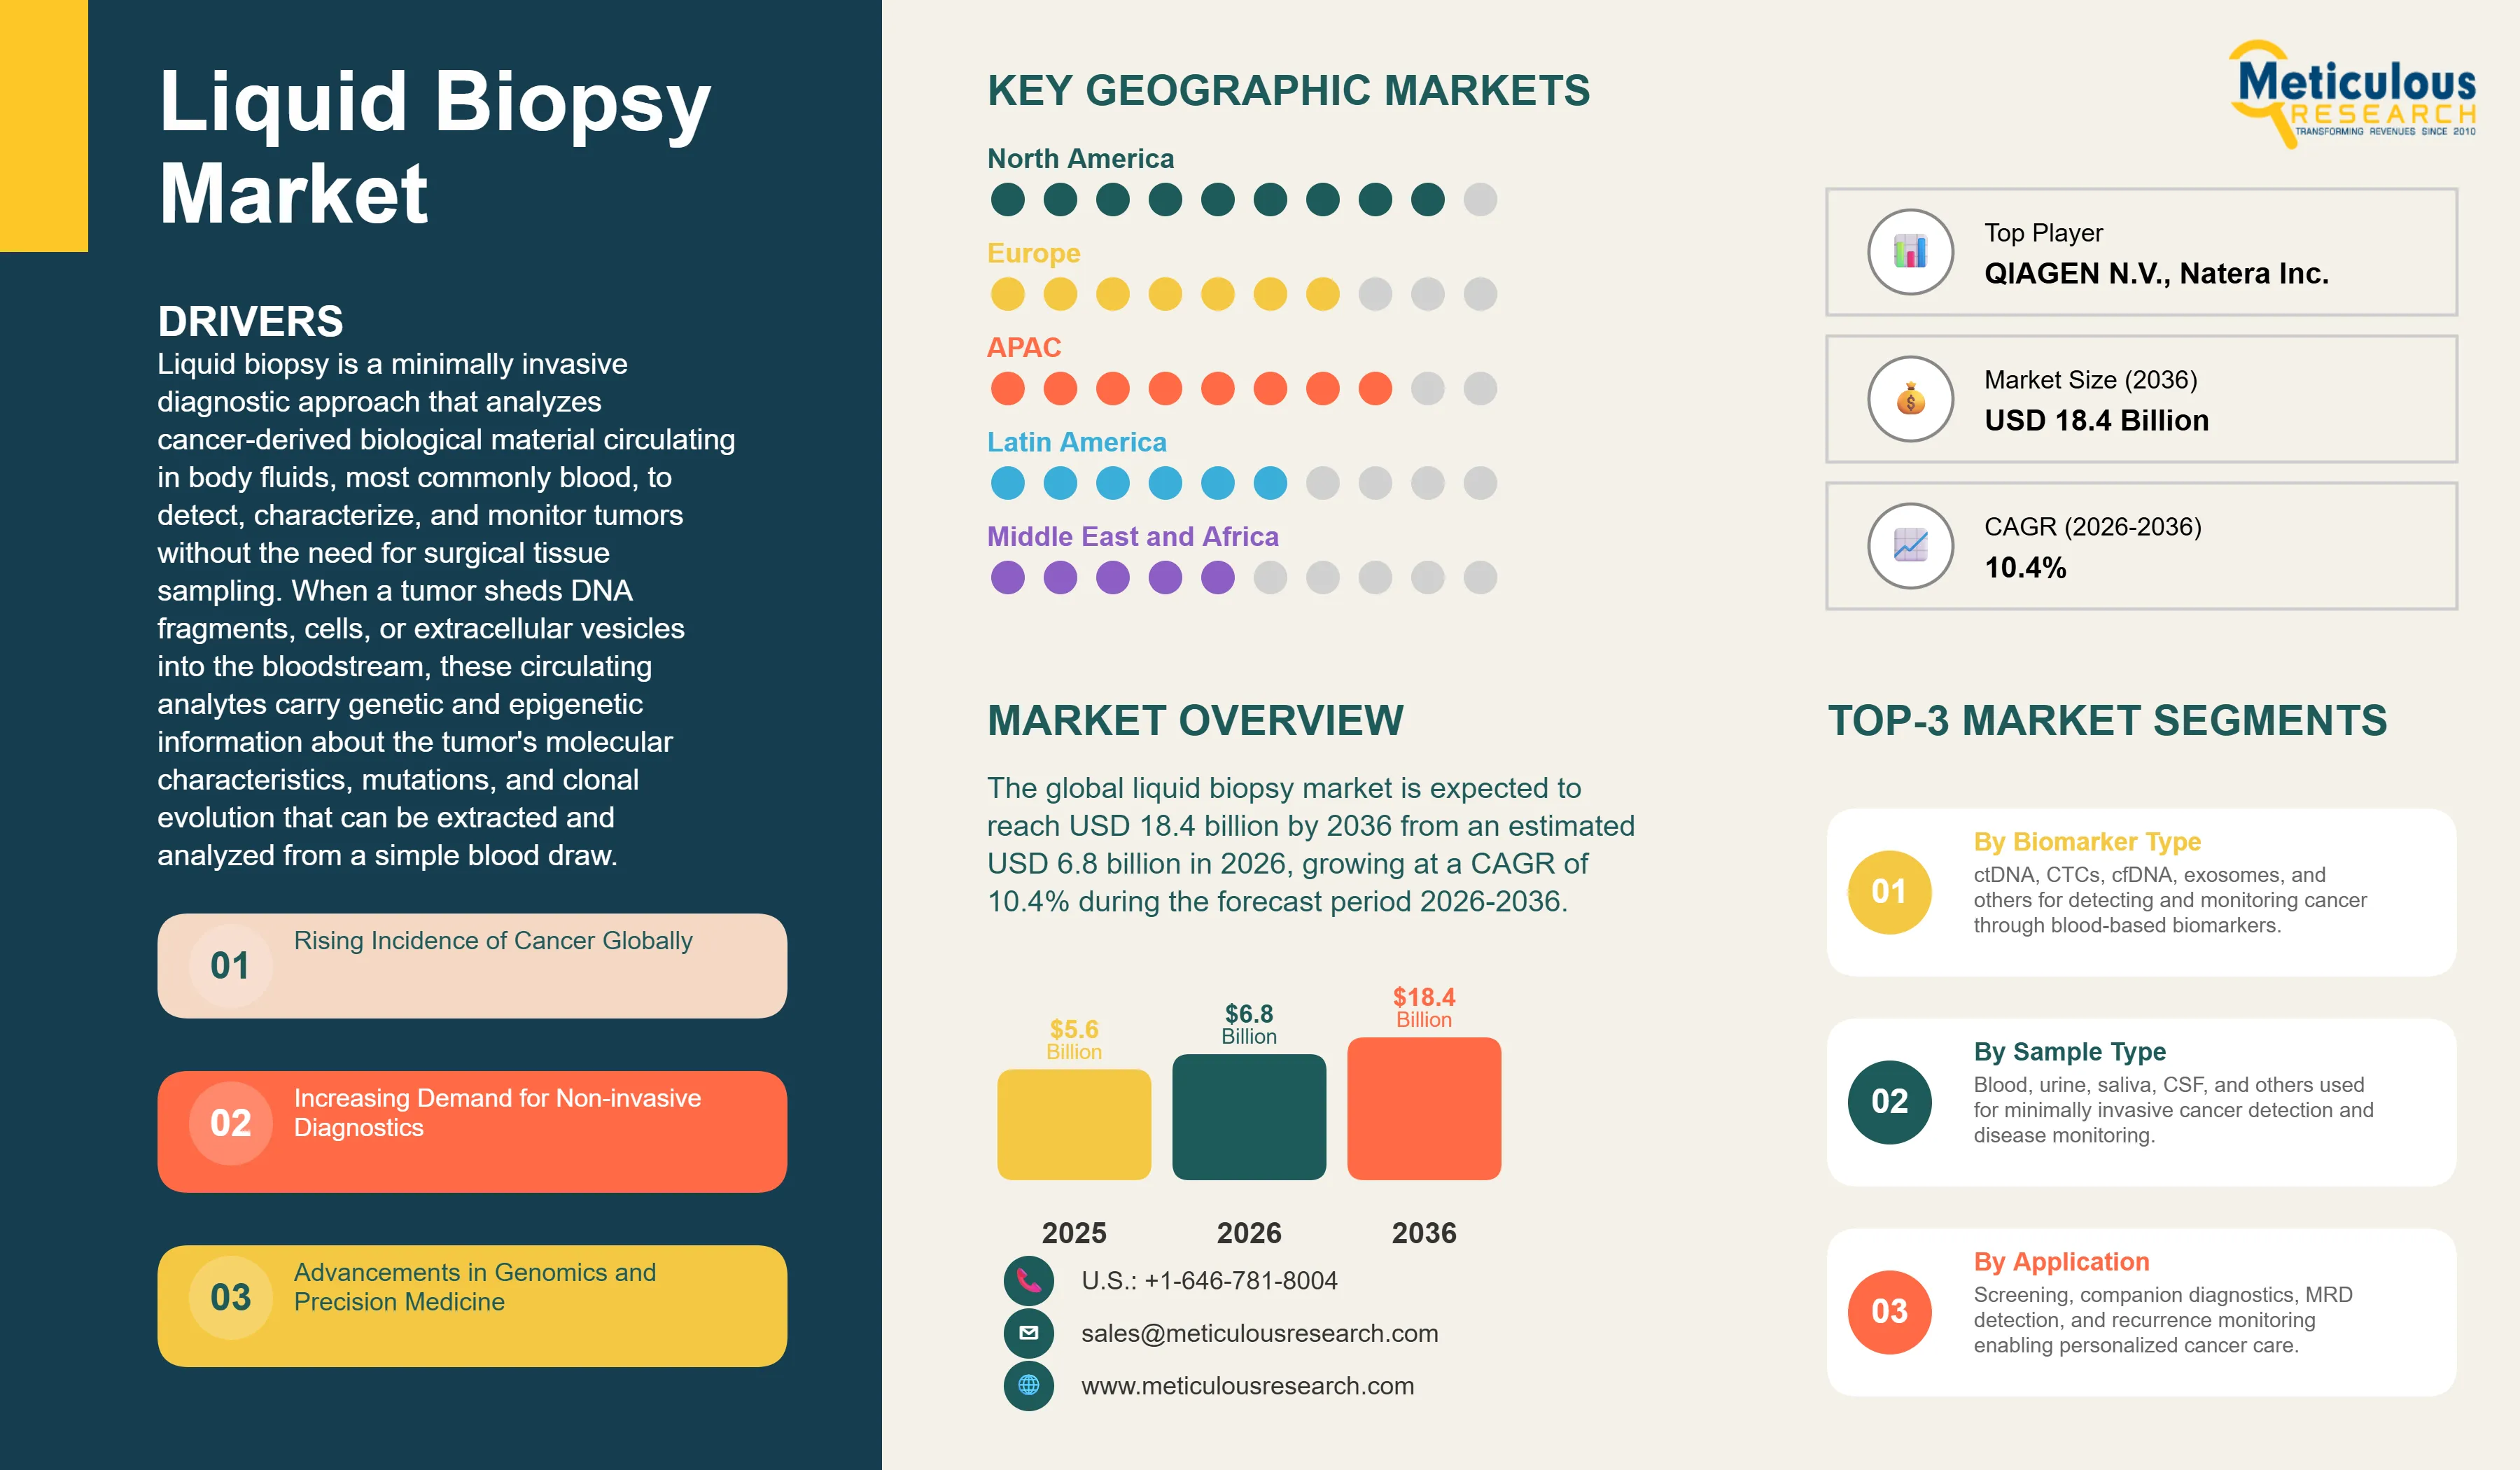
The global liquid biopsy market was valued at USD 5.6 billion in 2025. This market is expected to reach USD 18.4 billion by 2036 from an estimated USD 6.8 billion in 2026, growing at a CAGR of 10.4% during the forecast period 2026-2036.
- Published
- May 2026
- Pages
- 295
- Format
- PDF + Excel
- Report ID
- MRHC - 1041967
- Base year
- 2025
- 2025 · BASELINE
- $5.60B
- 2036
- $18.40B
- CAGR 2026–2036
- 10.4%
2025 baseline · 2026–2036 forecast at 10.4% CAGR · hover a bar for the value
Key highlights
The global liquid biopsy market is projected to reach USD 18.4 billion by 2036.
The market is expected to grow at a CAGR of 10.4% during the forecast period 2026-2036.
The global market for liquid biopsy was valued at USD 5.6 billion in 2025 and is estimated to reach USD 6.8 billion in 2026.
North America is expected to dominate the global liquid biopsy market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By biomarker type, the circulating tumor DNA (ctDNA) segment is expected to hold the largest share of the market in 2026, while the extracellular vesicles (exosomes) segment is projected to register the highest CAGR during the forecast period.
By sample type, the blood (plasma/serum) segment is expected to hold the largest share in 2026, while the urine segment is projected to register the highest CAGR during the forecast period.
By application, the therapy selection and companion diagnostics segment is expected to hold the largest share in 2026, while the cancer screening and early detection segment is projected to register the highest CAGR during the forecast period.
By cancer type, the lung cancer segment is expected to hold the largest share in 2026, while the pancreatic cancer segment is projected to register the highest CAGR during the forecast period.
By end user, the diagnostic laboratories segment is expected to hold the largest share in 2026, while the pharmaceutical and biotechnology companies segment is projected to register the highest CAGR during the forecast period.
By technology, the NGS-based testing segment is expected to hold the largest share in 2026, while the digital PCR segment is projected to register the highest CAGR during the forecast period.
By product type, the assays and kits segment is expected to hold the largest share in 2026, while the software and services segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 18.4 Billion |
| Market Size in 2026 | USD 6.8 Billion |
| Market Size in 2025 | USD 5.6 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 10.4% |
| Format | PDF, Excel & Cloud Portal · 295 pages |
| Dominating Biomarker Type | Circulating Tumor DNA (ctDNA) |
| Fastest Growing Biomarker Type | Extracellular Vesicles (Exosomes) |
| Dominating Sample Type | Blood (Plasma/Serum) |
| Fastest Growing Sample Type | Urine |
| Dominating Application | Therapy Selection/Companion Diagnostics |
| Fastest Growing Application | Cancer Screening & Early Detection (MCED) |
| Dominating Cancer Type | Lung Cancer |
| Fastest Growing Cancer Type | Pancreatic Cancer |
| Dominating End User | Diagnostic Laboratories |
| Fastest Growing End User | Pharmaceutical & Biotechnology Companies |
| Dominating Technology | NGS-based Testing |
| Fastest Growing Technology | Digital PCR (dPCR) |
| Dominating Product Type | Assays & Kits |
| Fastest Growing Product Type | Software & Services |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: biomarker type, sample type, application, cancer type, product type, end user.
According to the World Health Organization's World Cancer Report 2024, cancer is the second leading cause of death globally and accounted for approximately 9.7 million deaths in 2022, with an estimated 20 million new cancer cases diagnosed that year. The burden is projected to rise to 35 million new cases by 2050, a 77% increase from 2022, largely driven by population aging and exposure to risk factors. This growing global cancer burden, combined with the compelling clinical case for earlier and less invasive cancer detection, is the fundamental driver of the liquid biopsy market's sustained and rapid growth.
Liquid biopsy is a minimally invasive diagnostic approach that analyzes cancer-derived biological material circulating in body fluids, most commonly blood, to detect, characterize, and monitor tumors without the need for surgical tissue sampling. When a tumor sheds DNA fragments, cells, or extracellular vesicles into the bloodstream, these circulating analytes carry genetic and epigenetic information about the tumor's molecular characteristics, mutations, and clonal evolution that can be extracted and analyzed from a simple blood draw. Compared with conventional tissue biopsy, liquid biopsy offers the ability to sample the tumor continuously over time, capture tumor heterogeneity across multiple metastatic sites simultaneously, detect minimal residual disease after treatment, and identify emerging resistance mutations that are driving tumor progression.
The market is growing rapidly because liquid biopsy has successfully transitioned from a research tool into a commercially deployed clinical diagnostic with multiple FDA-approved applications. Guardant Health's Guardant360 CDx was FDA-approved as a companion diagnostic for multiple targeted therapies in non-small cell lung cancer and other solid tumors. Foundation Medicine's FoundationOne Liquid CDx received FDA approval as a companion diagnostic across multiple tumor types using ctDNA from plasma. According to the FDA's oncology database, more than 30 companion diagnostic approvals currently reference liquid biopsy-based tests as the recommended testing approach, establishing liquid biopsy as a mainstream clinical workflow in oncology treatment selection. The global oncology diagnostics investment wave documented by the American Cancer Society's 2025 cancer statistics report, which identified approximately 2 million new cancer cases expected in the U.S. in 2025 alone, confirms the scale of the clinical opportunity.
The most transformative near-term growth opportunity is multi-cancer early detection, where a single blood test can simultaneously screen for signals of multiple cancer types years before symptoms appear. Grail's Galleri test, which uses methylation analysis of cell-free DNA to detect signals across more than 50 cancer types with a single blood draw, received FDA Breakthrough Device designation and has been commercially available in the United States since 2021. According to Grail's 2025 clinical update, large prospective studies including the NHS-Galleri trial in the UK, which enrolled approximately 140,000 participants, are generating the real-world evidence needed to support insurance coverage decisions and potential FDA approval. A positive outcome from these pivotal studies would represent the largest single commercial expansion event in the liquid biopsy market's history.
Report infographic
Market dynamics
7 factors across 3 forcesRising Incidence of Cancer Globally
According to the World Health Organization's World Cancer Report 2024, approximately 20 million new cancer cases were diagnosed globally in 2022 and approximately 9.7 million cancer deaths occurred in that year. The WHO projects that the global cancer burden will continue growing, driven by aging populations, rising rates of lifestyle-associated risk factors, and improved cancer detection in previously underdiagnosed populations, with an estimated 35 million new cases projected annually by 2050. The American Cancer Society's Cancer Facts and Figures 2025 report estimates approximately 2 million new cancer cases and approximately 611,000 cancer deaths in the United States in 2025, sustaining the United States as the world's largest individual market for oncology diagnostics including liquid biopsy tests. Each new cancer diagnosis in principle represents a clinical need for liquid biopsy testing across multiple phases from initial genomic profiling for treatment selection through treatment monitoring and post-treatment MRD surveillance.
Advancements in Genomics and Precision Medicine
The commercial deployment of FDA-approved liquid biopsy companion diagnostics for an expanding portfolio of targeted therapies has created a self-reinforcing cycle of market growth: each new targeted therapy approval creates a companion diagnostic testing requirement, which generates commercial volume that funds further assay development, which supports additional clinical validation studies, which leads to further therapy approvals. According to the Pharmaceutical Research and Manufacturers of America's 2025 annual report, the oncology pipeline contains over 1,600 medicines/treatments in clinical development in the United States alone, a very large proportion of which are targeted therapies requiring molecular testing for patient selection. The progressive shift of oncology treatment from cytotoxic chemotherapy toward molecularly targeted agents and immunotherapies requiring biomarker selection is the fundamental commercial engine driving the companion diagnostic segment of the liquid biopsy market.
Table of contents
15 chapters · 159 sections · 295 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Biomarker Type | CtDNA | Extracellular vesicles (exosomes) |
| By Application | Therapy Selection / Companion Diagnostics | Cancer screening and early detection |
| By Cancer Type | Lung Cancer | Pancreatic cancer |
By Biomarker Type
- CtDNA to Hold the Largest Share
- The circulating tumor DNA segment is expected to account for the largest share of the global liquid biopsy market. ctDNA analysis forms the technical foundation of the most commercially successful and FDA-approved liquid biopsy products, including Guardant360 CDx and Foundation One Liquid CDx for companion diagnostics and Natera's Signatera for MRD monitoring.
- The ctDNA segment benefits from the most extensive clinical validation evidence base, the largest number of FDA-approved companion diagnostic applications, and the most mature NGS and dPCR technology platforms for ctDNA analysis.
- Guardant Health's approximately USD 687 million in 2024 revenues, principally from ctDNA-based liquid biopsy, illustrates the commercial scale of the ctDNA market.
- However, the extracellular vesicles (exosomes) segment is projected to register the highest CAGR during the forecast period.
- Exosomes carry RNA, proteins, and lipids in addition to DNA fragments, providing a richer biological information content than naked cfDNA, and their surface proteins may enable tissue-specific identification and earlier cancer detection than DNA-based approaches alone.
- While the exosome analysis field is earlier in clinical development than ctDNA, the growing research pipeline and commercial investment in exosome diagnostics platform companies is expected to drive above-average market growth as clinical evidence accumulates.
By Application
- Therapy Selection / Companion Diagnostics to Hold the Largest Share
- The therapy selection and companion diagnostics segment is expected to account for the largest share of the global liquid biopsy market.
- This application represents the most commercially mature and reimbursed segment of the liquid biopsy market, with over 30 FDA-approved companion diagnostic designations currently referencing liquid biopsy testing according to FDA's oncology database.
- Every patient with advanced non-small cell lung cancer, for example, requires molecular profiling including for EGFR, ALK, ROS1, KRAS G12C, and other targetable alterations, and liquid biopsy ctDNA testing is the clinically preferred approach when tissue is unavailable or insufficient for comprehensive molecular testing.
- However, the cancer screening and early detection segment, particularly MCED, is projected to register the highest CAGR during the forecast period.
- The potential commercial impact of successful MCED regulatory approval and insurance coverage for population-level screening would be transformative for this segment, creating a total addressable market far larger than the treatment-setting applications that currently dominate the market.
- According to IQVIA's 2025 Oncology Trends report, multi-cancer screening is identified as the highest-priority growth vector in oncology diagnostics investment.
By Cancer Type
- Lung Cancer to Hold the Largest Share
- The lung cancer segment is expected to account for the largest share of the global liquid biopsy market.
- Lung cancer has the most extensive and clinically validated liquid biopsy companion diagnostic ecosystem of any cancer type, with multiple FDA-approved targeted therapies specifying ctDNA or tissue NGS as the required companion diagnostic approach for patient selection.
- According to the American Cancer Society's 2025 Cancer Facts and Figures, lung and bronchus cancer remains the leading cause of cancer death in the United States, with approximately 125,000 deaths estimated in 2025, sustaining its position as the highest-priority cancer type for advanced molecular diagnostics including liquid biopsy.
- However, the pancreatic cancer segment is projected to register the highest CAGR during the forecast period.
- Pancreatic cancer has the lowest five-year survival rate of any major cancer type, at approximately 13% according to the American Cancer Society's 2025 data, largely because the vast majority of cases are diagnosed at advanced stages when curative treatment is no longer possible.
- The clinical urgency for early detection tools in pancreatic cancer is extreme, and liquid biopsy early detection research programs specifically targeting pancreatic cancer biomarkers are among the most intensively funded areas of the liquid biopsy research pipeline.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global liquid biopsy market. The United States is the world's most advanced liquid biopsy market by regulatory approvals, clinical adoption, and commercial revenue. According to the American Cancer Society's 2025 Cancer Facts and Figures, approximately 2 million new cancer cases were expected in the U.S. in 2025, providing the patient population foundation for the world's largest oncology diagnostics market. The FDA's oncology diagnostic approval process has produced more liquid biopsy companion diagnostic approvals than any other regulatory authority, with Guardant Health and Foundation Medicine's Roche having between them the largest number of approved companion diagnostic indications globally. Guardant Health reported revenues of approximately USD 687 million in 2024 per its annual report, with above-average revenue growth in its precision oncology segment driven by companion diagnostic volume expansion. The Centers for Medicare and Medicaid Services provides Medicare coverage for several liquid biopsy tests in oncology including the Foundation One Liquid CDx for patients with solid tumors and Natera's Signatera for colorectal cancer MRD monitoring, and this reimbursement coverage is a critical enabler of commercial adoption at scale.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific liquid biopsy market is expected to grow at the fastest CAGR during the forecast period. Asia-Pacific carries a very large share of the global cancer burden: according to the WHO's World Cancer Report 2024, Asia accounts for approximately 49% of global cancer cases and approximately 56% of global cancer deaths, driven by the region's large population and elevated rates of specific cancer types including liver, stomach, esophageal, and cervical cancer. China has the world's largest absolute cancer incidence and is experiencing rapid adoption of precision oncology diagnostics driven by growing clinical oncology infrastructure, favorable government policies for innovative diagnostics, and the commercial activities of domestic liquid biopsy companies including Berry Genomics and Burning Rock Biotech alongside global players including Roche, Illumina, and Thermo Fisher Scientific. According to Burning Rock Biotech's 2025 investor communications, the Chinese liquid biopsy market is growing rapidly as oncology treatment guidelines increasingly incorporate molecular testing requirements. Japan's well-developed oncology diagnostics infrastructure and high awareness of cancer screening, South Korea's advanced healthcare IT ecosystem, and Singapore's position as an Asia-Pacific clinical research hub all contribute to regional growth momentum.
Competitive landscape
- Guardant Health Inc. (U.S.)
- Illumina Inc. (U.S.)
- Roche Diagnostics · Switzerland
- Thermo Fisher Scientific Inc. (U.S.)
- Bio-Rad Laboratories Inc. (U.S.)
- QIAGEN N.V. · Netherlands
- Exact Sciences Corporation (U.S.)
- Foundation Medicine/Roche (U.S.)
- NeoGenomics Laboratories (U.S.)
- Natera Inc. (U.S.)
- Freenome Holdings Inc. (U.S.)
- Grail Inc. (U.S.)
- Myriad Genetics Inc. (U.S.)
- Sysmex Corporation · Japan
- Menarini Silicon Biosystems · Italy
Frequently asked questions
The global liquid biopsy market is expected to reach USD 18.4 billion by 2036 from an estimated USD 6.8 billion in 2026, at a CAGR of 10.4% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Liquid Biopsy Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1041967). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/liquid-biopsy-market-6650