Hypersonic Weapons Market (2025-2035)
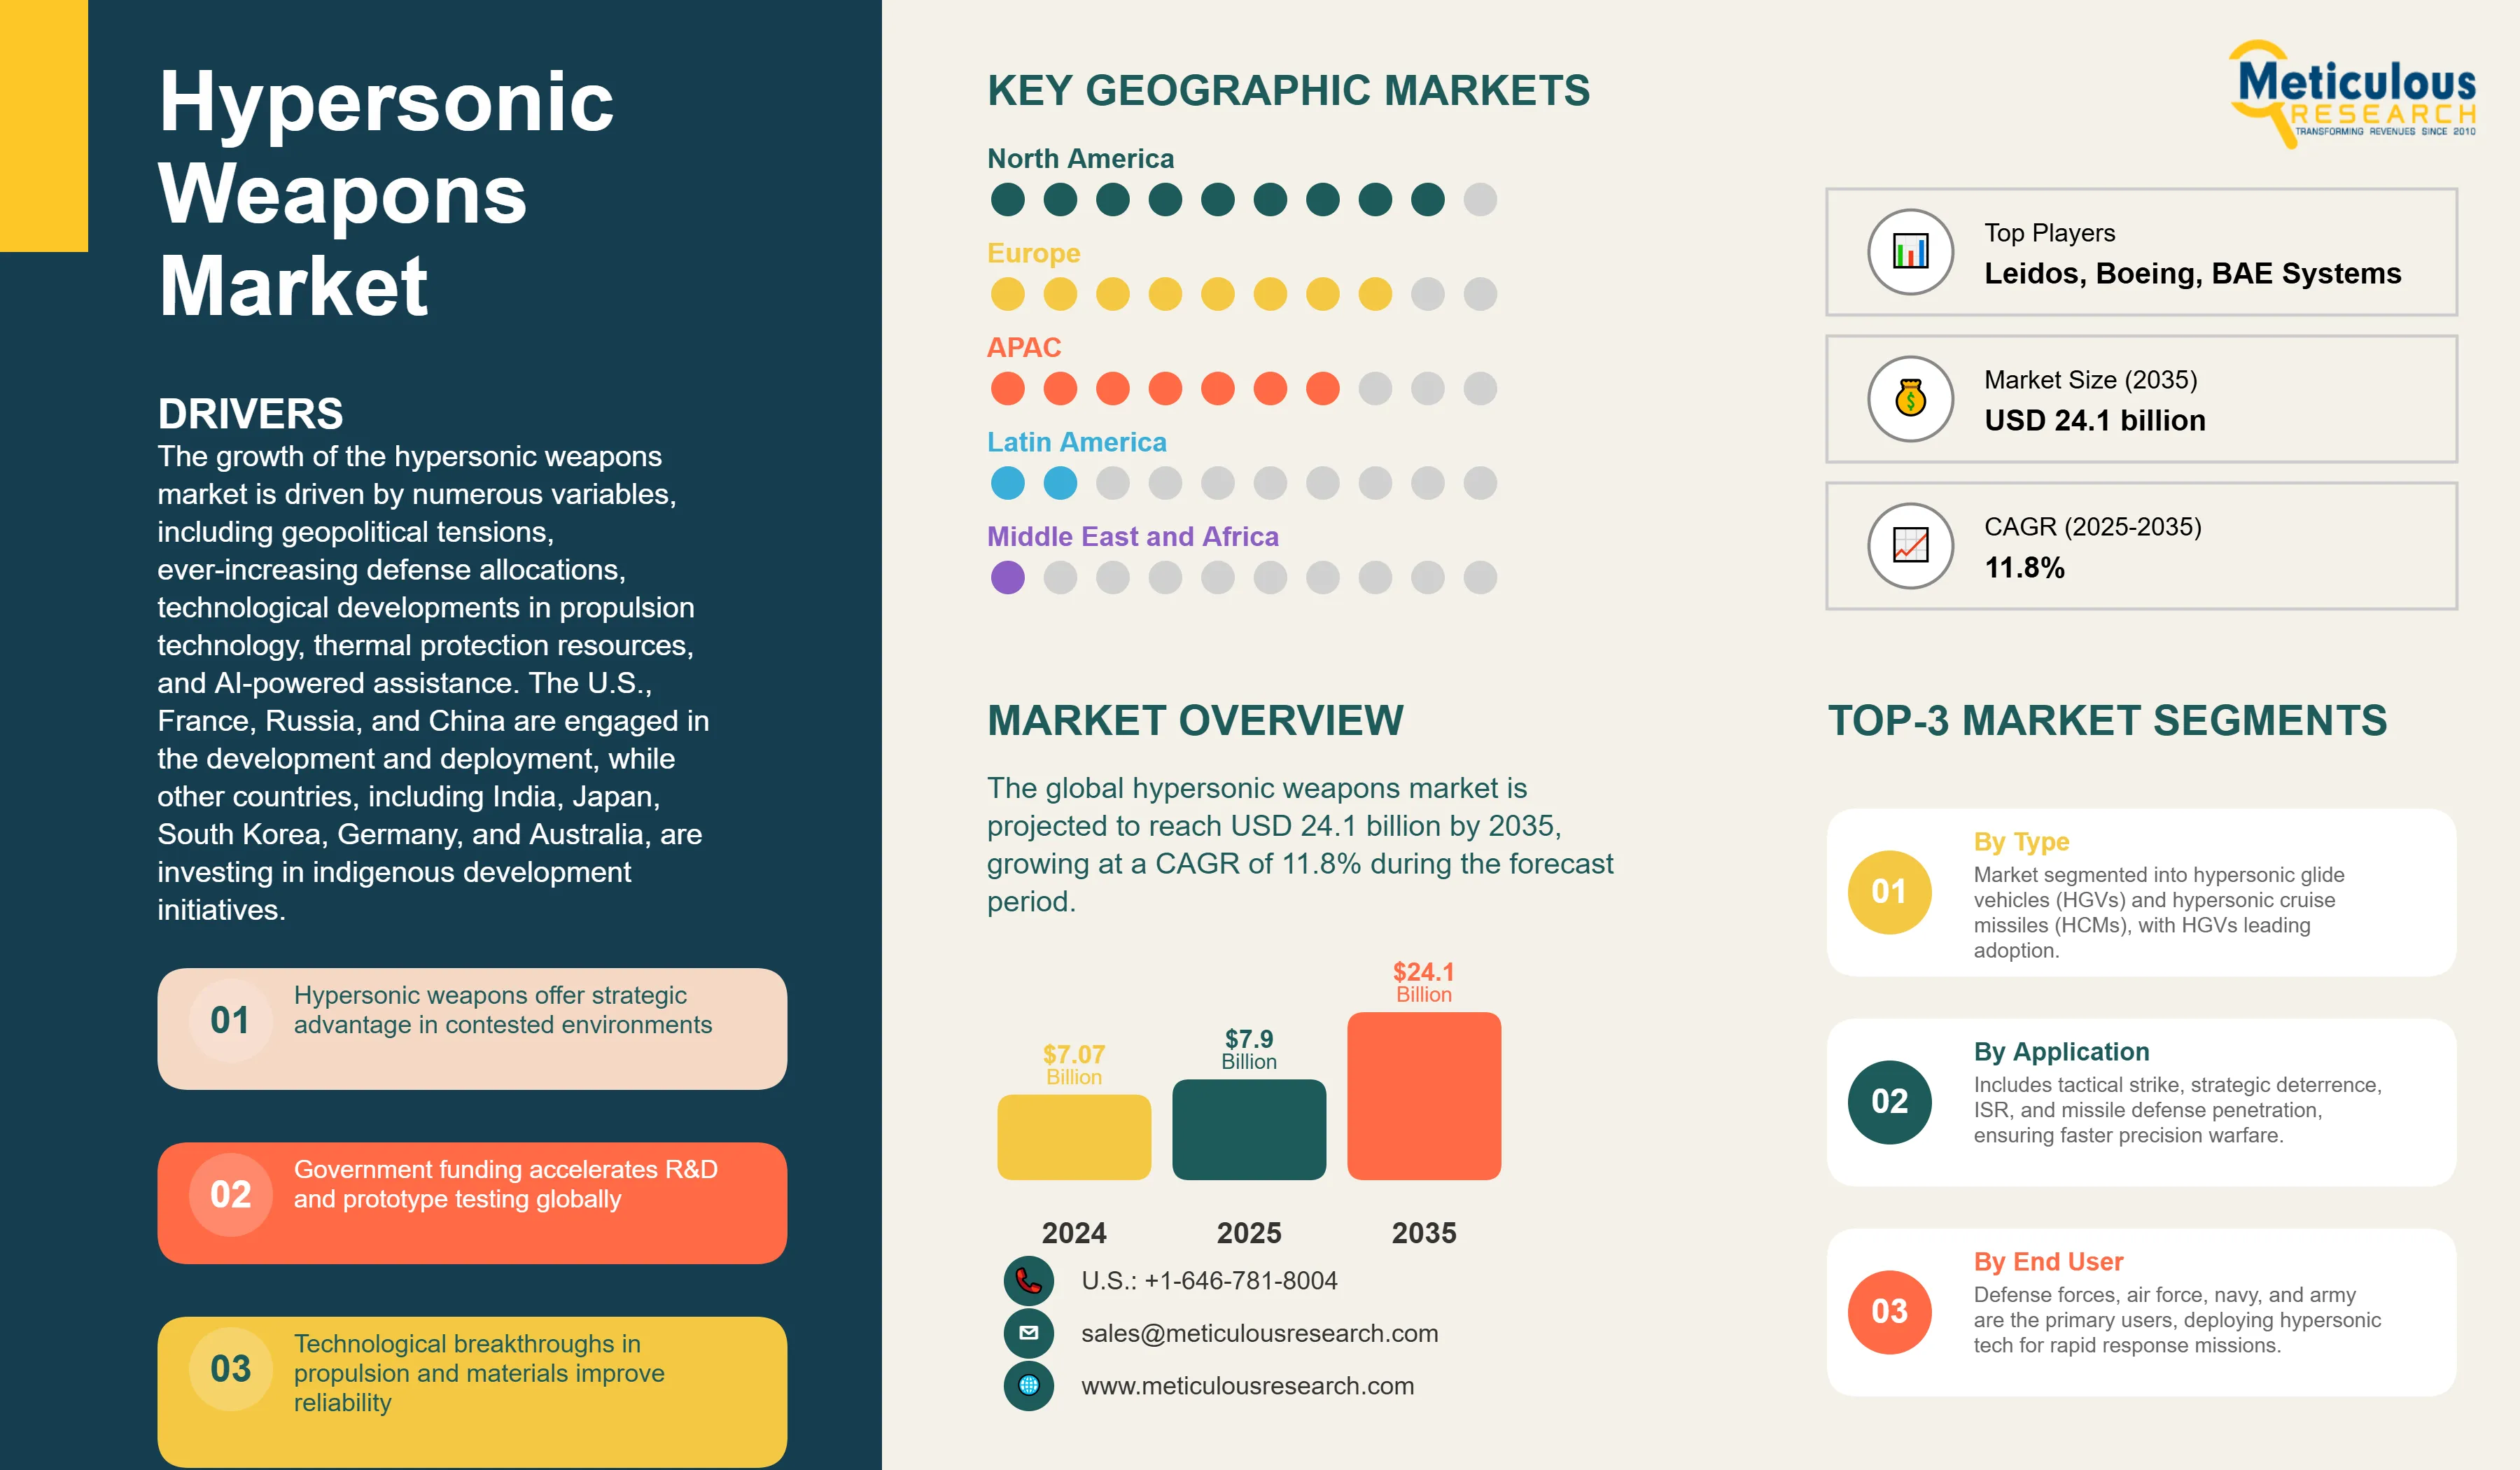
The global hypersonic weapons market was valued at USD 7.2 billion in 2024. This market is projected to reach USD 24.1 billion by 2035 from an estimated USD 7.5 billion, growing at a CAGR of 11.8% during the forecast period.
- Published
- Sep 2025
- Pages
- 198
- Format
- PDF + Excel
- Report ID
- MRAD - 1041587
- Base year
- 2024
- 2024 · BASELINE
- $7.20B
- 2035
- $24.10B
- CAGR 2025–2035
- 11.8%
2024 baseline · 2025–2035 forecast at 11.8% CAGR · hover a bar for the value
Key highlights
Hypersonic Missiles Dominate Market Demand Across Strategic Strike Missions
North America Dominates the Hypersonic Weapons Market Due to Advanced R&D and Strategic Edge
Asia-Pacific’s Rapid Rise Owing to Indigenous Programs, and Multilateral Collaboration Drives Regional Leadership
Report summary
| Particulars | Details |
|---|---|
| Market size (2025) | USD 7.9 billion |
| Revenue forecast in 2035 | USD 24.1 billion |
| CAGR (2025-2035) | 11.8% |
| Format | PDF, Excel & Cloud Portal · 198 pages |
| Base Year | 2024 |
| Forecast period | 2025 – 2035 |
| Report coverage | Market size and forecast, competitive landscape and benchmarking, country/regional level analysis, key trends, growth drivers and restraints |
| Segments covered | By Type (Hypersonic Missiles, Hypersonic Gliding Vehicles), By Domain · (Land, Naval, Airborne) By Range (Short-range, Medium-range, Long-range) By Subsystem (Guidance System, Propulsion Systems, Warheads) Geography |
| Regional scope | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
| Key companies profiled | Lockheed Martin Corporation, L3Harris Technologies Inc., General Dynamics Corporation, BAE Systems, Raytheon Technologies Corporation, Leidos, Boeing, Northrop Grumman Corporation, Thales Group, Israel Aerospace Industries |
| Customization | Comprehensive report customization with purchase. Addition or modification to country, regional & segment scope available |
| Pricing Details | Access customized purchase options to meet your specific research requirements. Explore flexible pricing models |
Report overview
Segments covered: type, domain, range, subsystem.
The growth of the hypersonic weapons market is driven by numerous variables, including geopolitical tensions, ever-increasing defense allocations, technological developments in propulsion technology, thermal protection resources, and AI-powered assistance. The U.S., France, Russia, and China are engaged in the development and deployment, while other countries, including India, Japan, South Korea, Germany, and Australia, are investing in indigenous development initiatives. As per the U.S. Congressional Research Service, in 2023, more than 15 countries were proactively pursuing the development of advanced hypersonic weapon systems.
Hypersonic weapon platforms are envisioned as crucial for next-generation dissuasion and accurate strike capabilities. In 2024, the Pentagon attested that hypersonic systems were incorporated into joint force preparation, with more than USD 4.7 billion sanctioned to associated research & development and testing. Moreover, as per SIPRI, worldwide armed forces spending touched USD 2.72 trillion in 2024, with a surging share focused on high accuracy and long-range precision strikes. On the other hand, China steered several glide vessel tests under its DF-ZF initiative, demonstrating functional maturity. The industry is propelled by the demand for pivotable, rapid weapons that possess the ability to evade conventional counter-missile systems. As of 2025, hypersonic weapons are shifting from the investigational phase to the pre-operational phase, with acquisition plans spanning across multiple geographies.
Report infographic
Base CAGR: 11.8%
|
Category |
Key Factor |
Short-Term Impact (2025–2028) |
Long-Term Impact (2029–2035) |
Estimated CAGR Impact |
|
Drivers |
1. Hypersonic weapons offer strategic advantage in contested environments |
High funding allocation to R&D programs |
Full-scale deployment and mass production |
▲ +2.5% |
|
2. Breakthroughs in Propulsion & Materials |
Accelerates prototype readiness |
Expands mission profiles |
▲ +1.8% |
|
|
Restraints |
1. High Development & Production Costs |
Limits participation to major defense primes |
Supply chain bottlenecks |
▼ −1.4% |
|
2. Thermal Management and Guidance Remain Technical Challenges |
Restricts international sales |
Encourages indigenous programs |
▼ −0.9% |
|
|
Opportunities |
1. Allied Cooperative Programs |
Tech-sharing accelerates capability building |
Multinational systems integration |
▲ +1.6% |
|
2. AI-Enhanced Guidance Systems |
Improves targeting in contested environments |
Expands commercial spin-offs |
▲ +1.3% |
|
|
Trends |
1. Shift Toward Dual-Use Hypersonic Platforms |
Enables ISR & strike missions |
Broadens procurement base |
▲ +1.0% |
|
Challenges |
1. Counter-Hypersonic Defense Development |
Reduces deterrence value over time |
Spurs next-gen innovation |
▼ −0.8% |
Market dynamics
5 factors across 2 forcesHypersonic weapons offer strategic advantage in contested environments
According to RAND Corporation, in 2023, more than 70% of defense strategists in NATO and the Indo-Pacific regions saw hypersonic weapons as crucial for defeating sophisticated air defense systems. These weapons combine speed, altitude, and mobility, making them challenging to intercept. The US Indo-Pacific Command revealed that during collaborative exercises, hypersonic platforms lowered simulated response times by 60%. Their capacity to deliver precise blows in restricted areas is generating procurement interest across different regions.
Government funding accelerates R&D and prototype testing globally
According to the Stockholm International Peace Research Institute (SIPRI), in 2024, global defense R&D investment on hypersonic weapons exceeded USD 12 billion, with the U.S., China, and Russia contributing more than 60%. The US Department of Defense increased its hypersonic budget by 22% year on year, while China's CASIC obtained additional cash under its 14th Five-Year Plan. These expenditures enable quick prototyping, wind tunnel testing, and flight trials, with over 50 hypersonic experiments taking place globally in 2023
Technological breakthroughs in propulsion and materials improve reliability
An increase in the scramjet propulsion system has made it possible for continuous flight at Mach 5 or higher, as well as the retention of the aircraft's manoeuvrability. Such a feat is achieved through the supersonic combustion of the engine air that flows which is technically called "supersonic combustion." Besides that, new carbon-carbon composite materials have been developed to give off more than 3,000°F of thermal resistance, which is necessary for hypersonic vehicles faced with such a temperature extreme. These novelties not only extend the reliability but also allow the range of precision hypersonic weapons to be longer. The US HAWC program has achieved successful AI-based flight control system integration, resulting in improved trajectory stability under dynamic conditions, as well as enhanced guidance accuracy.
Table of contents
13 chapters · 146 sections · 198 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2035) |
|---|---|---|
| By Type | Hypersonic Missiles | — |
| By Range | — | — |
By Type
- Hypersonic Missiles Dominate Market Demand Across Strategic Strike Missions
- The hypersonic missiles segment accounts for the highest revenue share in 2025 and is set to continue its market dominance through 2035.
- This market dominance is owing to the demand for long-range, precision-guided strike capabilities.
- These missiles are being integrated into air, sea, and land platforms, with the US ARRW, China's DF-17, and Russia's Zircon leading the way.
- Hypersonic missiles provide rapid response, low interception risk, and strategic deterrence value.
- The US Navy's CPS system is intended for submarine launch, whilst the Army's LRHW allows for transportable ground deployment.
- Demand is increasing across NATO and the Indo-Pacific, with procurement projects speeding up as geopolitical tensions rise.
- Countries worldwide invest in hypersonic missile capabilities to maintain competitive military advantages and strengthen deterrence strategies, with development programs spanning conventional and nuclear payload options across multiple launch platforms.
By Range
- Short-range Hypersonic Systems Gain Traction for Tactical Battlefield Use
- According to the Center for Strategic and Budgetary Assessments (CSBA), short-range hypersonic systems will see a significant rise in development interest, notably for tactical applications like anti-ship, anti-air, and battlefield interdiction.
- These systems are primarily built for fast deployment and agility and have a range of 500-1,000 kilometers.
- China's DF-17 and Russia's Kinzhal are examples of short-range hypersonic platforms designed for regional deterrence.
- The United States Army is looking into short-range LRHW variants for mobile forces, while India's DRDO is developing tactical scramjet demonstrators.
- These devices are gaining importance in A2/AD situations and contested zones where speed and precision are essential.
- Industry growth is sustained by evolving military doctrines that emphasize rapid engagement of regional threats and the increasing availability of hypersonic technologies through international cooperation programs.
Geographic analysis
North America
Largest shareNorth America dominated the hypersonic weapons market in 2025, owing primarily to significant defense R&D investments, advanced technological capabilities, and a strong military infrastructure. The United States leads the world in development and deployment, with programs like the Air-Launched Rapid Response Weapon (ARRW) and Long-Range Hypersonic Weapon (LRHW) receiving billions of dollars in funding for research, testing, and operational integration. These initiatives are supported by advances in scramjet propulsion, thermal-resistant materials, and precision guidance systems, which improve reliability and strategic applicability. The region's dominance is bolstered by well-known defense contractors, strong government support, and a focus on maintaining a strategic advantage over potential adversaries. Collectively, these factors place North America as the largest and most technologically advanced market for hypersonic weapons, accounting for the vast majority of global investments and deployments in this sector. North America Dominates the Hypersonic Weapons Market Due to Advanced R&D and Strategic Edge
Asia-Pacific
Fastest growthAccording to the Asia-Pacific Security Studies Journal, hypersonic weapons programs in the Asia-Pacific are expected to increase owing to strategic competition in the South China Sea and Taiwan Strait. China's DF-17 and DF-ZF systems are now operational, and India's DRDO is constructing the HSTDV scramjet demonstrator. Japan launched feasibility studies for indigenous hypersonic systems as part of its 2022 defense modernization strategy. Similarly, the SCIFiRE program is a collaboration between Australia and the United States to develop air-launched hypersonic missiles. Thus, regional governments are focusing on hypersonic capabilities for deterrent, quick strike, and anti-access/area denial (A2/AD) measures. The market expansion is further fueled by the strategic imperative to counter emerging threats, particularly drone swarms and advanced missile defense systems. Advancements in scramjet propulsion, thermal protection materials, and AI-driven guidance systems enable sustained hypersonic flight capabilities exceeding Mach 5 speeds. Also, regional defense budgets continue expanding to support hypersonic weapons as critical enablers of strategic deterrence and precision strike capabilities. The presence of multiple military powers in proximity intensifies competitive dynamics, ensuring the Asia Pacific remains the fastest-growing segment for hypersonic weapons development and deployment. China’s hypersonic program encompasses comprehensive development of boost-glide vehicles, cruise missiles, and anti-ship variants designed to penetrate advanced missile defense systems. China's strategic approach prioritizes indigenous development through state-owned enterprises and defense research institutions, reducing dependence on foreign technologies while advancing asymmetric warfare capabilities. The country's hypersonic arsenal includes multiple operational systems capable of delivering conventional and nuclear payloads at speeds exceeding Mach 5 with enhanced maneuverability compared to traditional ballistic missiles. According to China Aerospace Science and Industry Corporation (CASIC), China's DF-ZF hypersonic glide vehicle will complete numerous flight tests in 2023 and be deployed in limited numbers by the PLA Rocket Force. The system is intended for precision strikes against naval assets and command centers, with maneuverability that rivals conventional missile defense. China's 14th Five-Year Plan involves increased financing for hypersonic research and development, with a focus on AI-enabled guiding and thermal. Asia-Pacific’s Rapid Rise Owing to Indigenous Programs, and Multilateral Collaboration Drives Regional Leadership China Operationalizes Hypersonic Glide Vehicles for Regional Deterrence
Competitive landscape
The global hypersonic weapons market is moderately consolidated, with defense primes such as Lockheed Martin, Raytheon Technologies, Northrop Grumman, Boeing, BAE Systems, and L3Harris Technologies dominating R&D and production. Lockheed Martin’s AGM-183A ARRW underwent final testing in 2023, while Raytheon partnered with Northrop to develop scramjet-powered systems under the HAWC program. China’s DF-17 and Russia’s Avangard systems entered limited deployment, reflecting strategic prioritization. Competitive advantage lies in propulsion efficiency, thermal shielding, and guidance accuracy, with firms investing in AI-enabled flight control and composite materials.
- —
The last planned end-to-end test of the AGM-183A Air-Launched Rapid Response Weapon (ARRW) was carried out by the U.S. Air Force on March 17, 2024. From a B-52 bomber over the Pacific, the crew made a successful launch, and the test was basically a check of the missile's overall abilities. The test has provided extremely valuable data for future hypersonic programs; however, the details of the separation of the glide vehicle and the flight trajectory have not been released. The developmental program of ARRW reached several important milestones, but the project was not promoted to an operational deployment stage, and it is currently not planned to integrate B-52 platforms by late 2025. The legacy of the program is a big contribution to the hypersonic technology maturation efforts that are happening now.
- May 2024
The US Army awarded Lockheed Martin Corporation a USD 756 million contract to improve the Long-Range Hypersonic Weapon (LRHW) system. The contract entails providing additional LRHW battery equipment, systems, software engineering support, and logistics.
- Lockheed Martin Corporation
- L3Harris Technologies Inc.
- General Dynamics Corporation
- BAE Systems
- Raytheon Technologies Corporation
- Leidos
- Boeing
- Northrop Grumman Corporation
- Thales Group
- Israel Aerospace Industries
Frequently asked questions
The Hypersonic Weapons Market size is estimated to be USD 7.9 billion in 2025 and grow at a CAGR of 11.8% to reach USD 24.1 billion by 2035.
Cite this report
Meticulous Research. (2025). Hypersonic Weapons Market - Global Opportunity Analysis And Industry Forecast (2025-2035) (Report No. MRAD - 1041587). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/hypersonic-weapons-market-6270