Functional Chocolates Market (2026-2036)
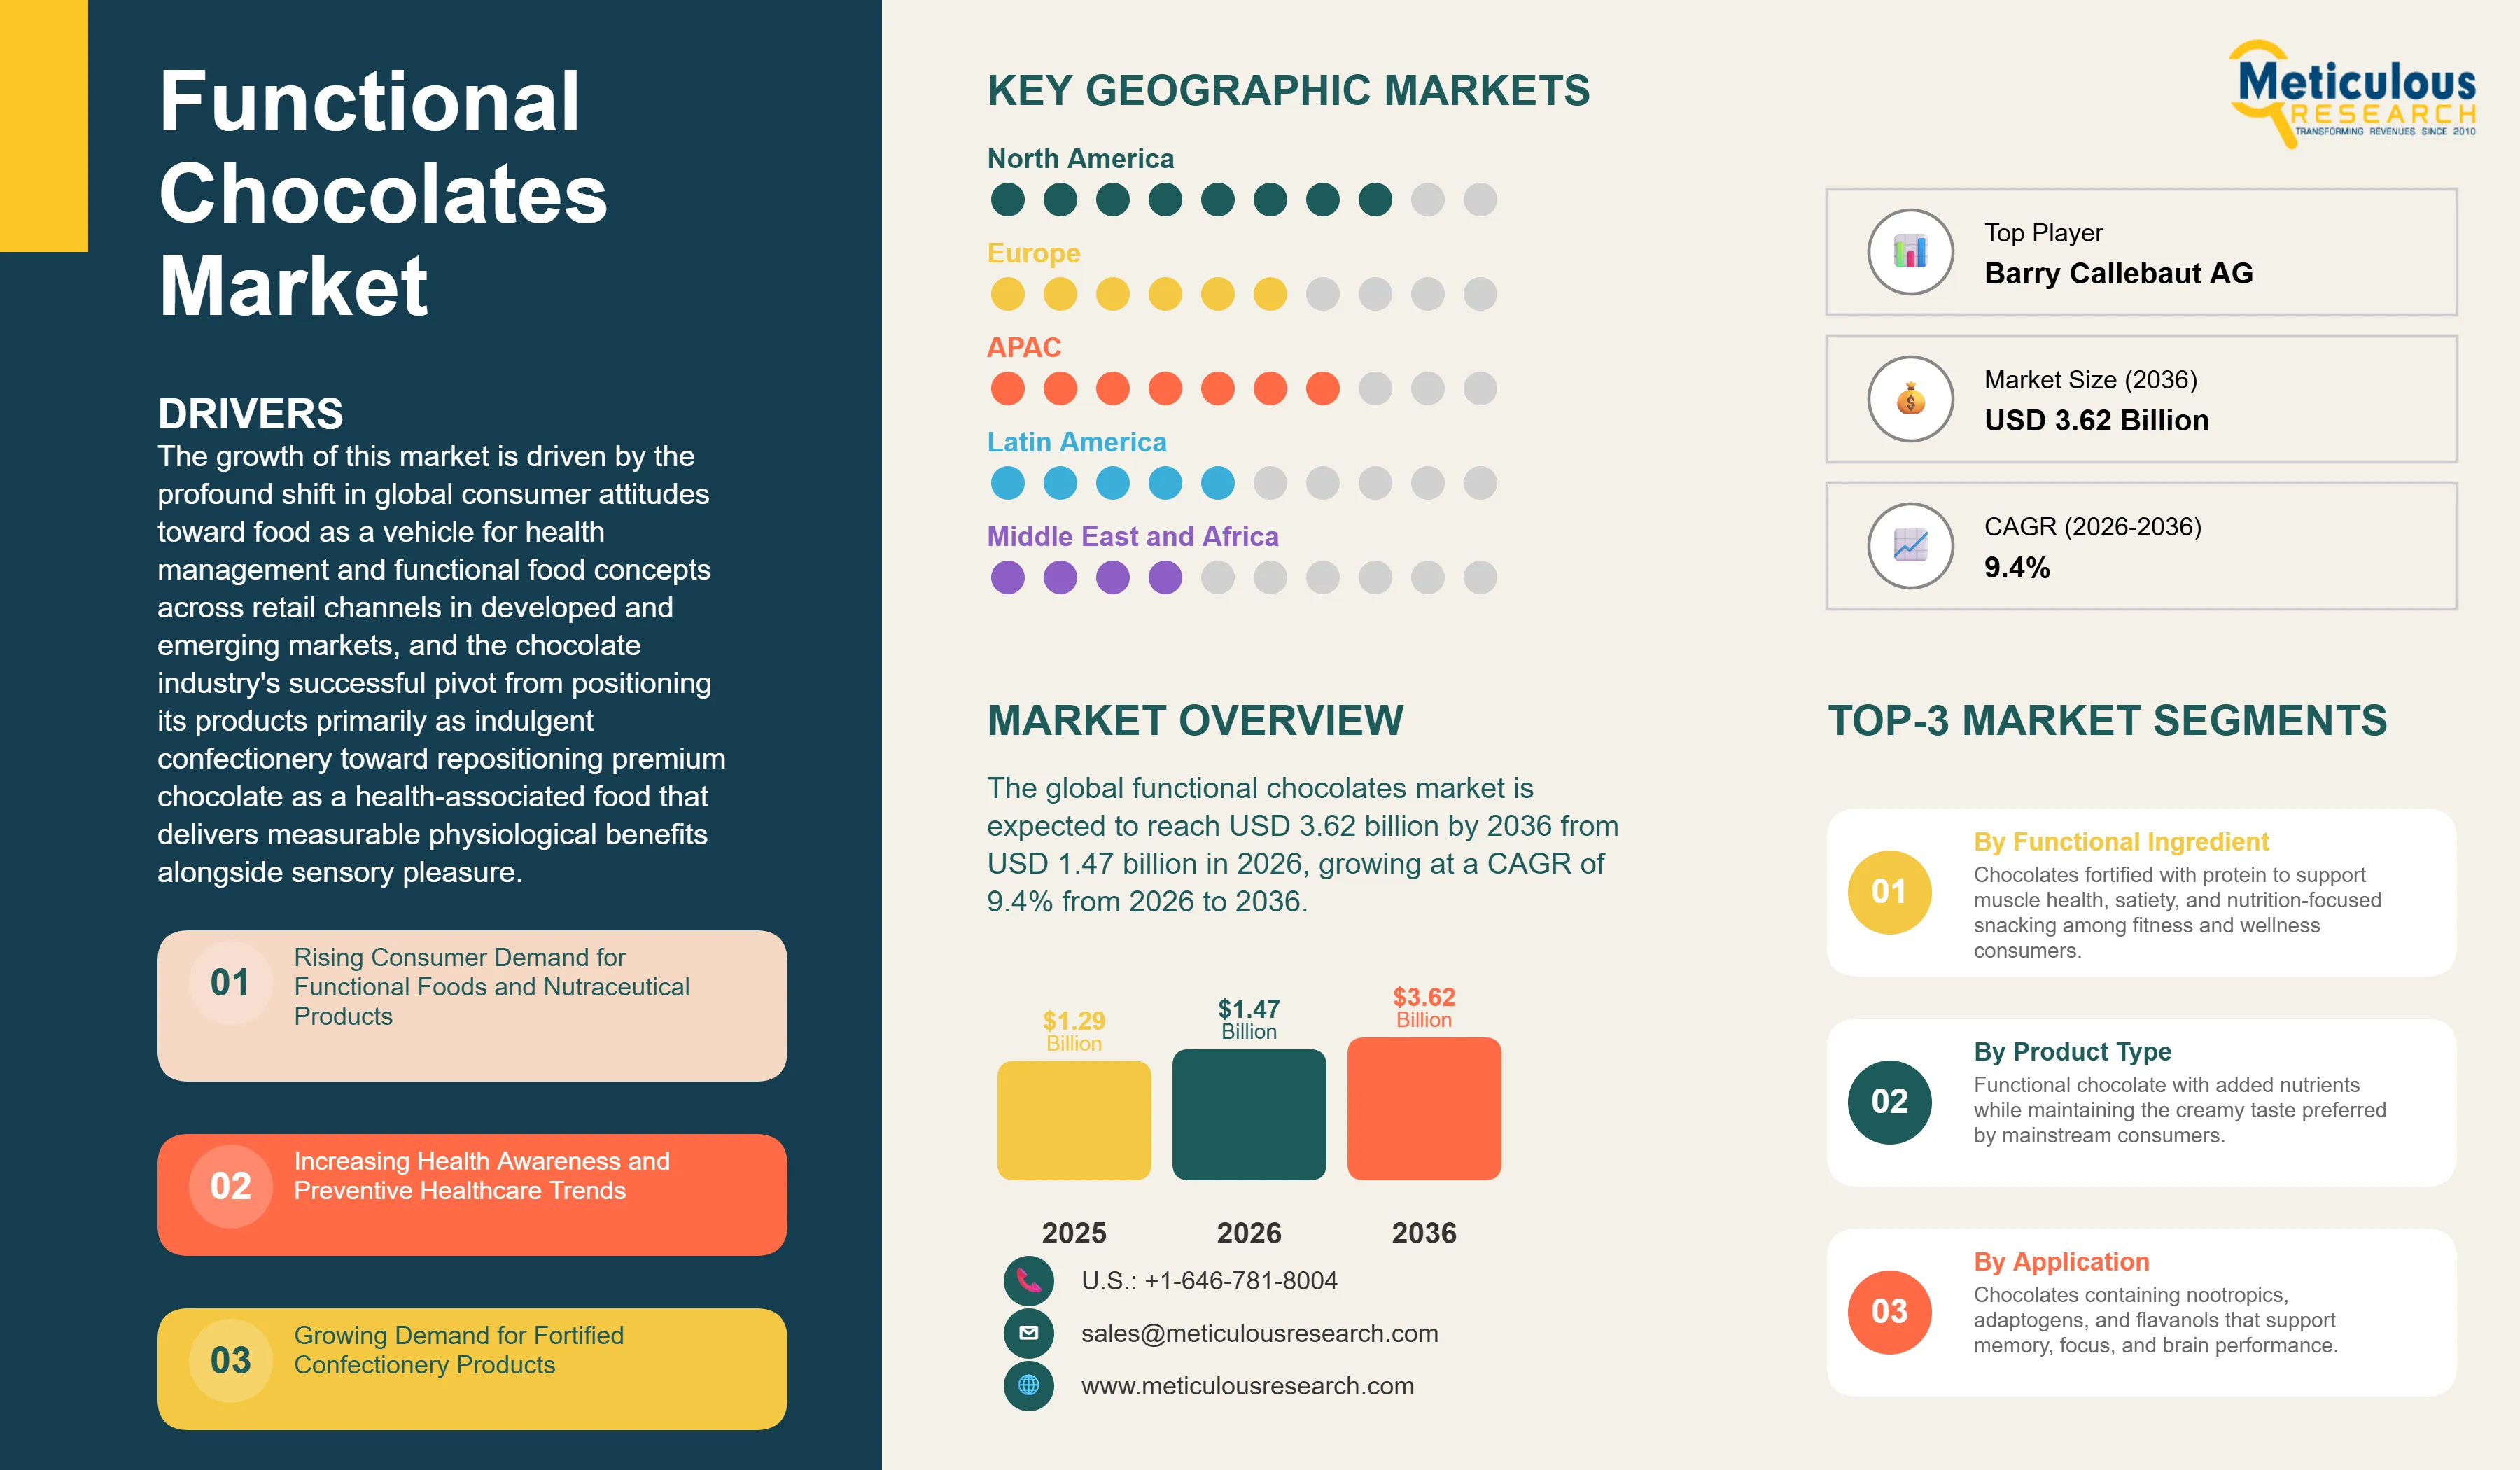
The global functional chocolates market was valued at USD 1.29 billion in 2025. This market is expected to reach USD 3.62 billion by 2036 from USD 1.47 billion in 2026, growing at a CAGR of 9.4% from 2026 to 2036.
- Published
- Mar 2026
- Pages
- 265
- Format
- PDF + Excel
- Report ID
- MR-1848
- Base year
- 2025
- 2025 · BASELINE
- $1.29B
- 2036
- $3.62B
- CAGR 2026–2036
- 9.4%
2025 baseline · 2026–2036 forecast at 9.4% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global functional chocolates market is projected to reach USD 3.62 billion by 2036.
The market is expected to grow at a CAGR of 9.4% from 2026 to 2036.
North America is expected to dominate the global functional chocolates market with the largest market share in 2026, driven by the high level of consumer health consciousness and established willingness to pay premium prices for functional food products, the strong presence of specialist functional chocolate brands including Hu Kitchen, Lily's Sweets, Endangered Species Chocolate, and Alter Eco Foods that have built significant retail distribution in natural and specialty food channels, and the robust e-commerce infrastructure that supports direct-to-consumer sales of premium functional chocolate products to health-oriented consumer segments.
Asia-Pacific is expected to witness the fastest growth during the forecast period, driven by rising disposable incomes and growing health awareness across China, India, Japan, and South Korea, the rapid expansion of premium chocolate consumption in markets that have historically been lower per-capita chocolate consumers relative to Western markets, and the strong cultural resonance of functional food concepts in Asian markets where food-as-medicine traditions create favorable consumer receptivity to health benefit claims on food products.
By functional ingredient, the protein-enriched chocolates segment is expected to hold the largest share of the overall functional chocolates market in 2026, as sports nutrition-oriented protein chocolate bars and protein-fortified chocolate snacks represent the most commercially developed and widely distributed functional chocolate category, with established shelf presence in mass grocery, pharmacy, and sports nutrition retail channels and strong consumer recognition of protein content as a health-positive attribute in snack foods.
By functional ingredient, the probiotic and prebiotic chocolates segment is expected to witness the fastest growth during the forecast period, driven by the explosive growth of consumer interest in gut health and microbiome science, the successful translation of probiotic supplementation concepts from yogurt and dietary supplement formats into chocolate delivery systems that provide both the sensory appeal of premium chocolate and the microbiome support benefits of clinically validated probiotic strains.
By product type, the dark chocolate segment is expected to hold the largest share of the overall functional chocolates market in 2026, as dark chocolate's established health-positive image — grounded in well-publicized research on cocoa flavanol benefits for cardiovascular health and cognitive function — gives it natural positioning as the base format for functional chocolate products targeting health-conscious consumers, and its compatibility with a wide range of functional ingredient additions including protein, adaptogens, and superfoods makes it the preferred format for premium functional chocolate formulation.
By product type, the sugar-free chocolate segment is expected to witness the fastest growth during the forecast period, driven by the global rise in diabetes prevalence and pre-diabetic consumer populations seeking chocolate enjoyment without glycemic impact, the growing mainstream adoption of low-carbohydrate and ketogenic dietary patterns that create demand for sugar-free confectionery, and the significant improvement in sugar-free chocolate taste and texture quality achieved through advanced alternative sweetener technologies including erythritol, monk fruit extract, and allulose.
By application, the general wellness segment is expected to hold the largest share of the overall functional chocolates market in 2026, as the majority of functional chocolate products target broad health-conscious consumer segments with general wellness positioning rather than specific clinical applications, and general wellness remains the largest and most commercially accessible application category within the functional food market.
By application, the cognitive health segment is expected to witness the fastest growth during the forecast period, driven by growing consumer concern about cognitive performance, mental focus, and age-related cognitive decline, the emergence of nootropic ingredient formulations incorporating lion's mane mushroom, ashwagandha, phosphatidylserine, and cocoa flavanols that are finding broad consumer acceptance in chocolate delivery formats.
By distribution channel, online retail and e-commerce is expected to witness the fastest growth during the forecast period, reflecting the structural advantage of direct-to-consumer digital channels for specialty and premium functional chocolate brands that lack the scale to secure broad conventional retail shelf presence but can reach health-conscious consumer segments effectively through targeted digital marketing and subscription commerce models.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 3.62 Billion |
| Market Size in 2026 | USD 1.47 Billion |
| Market Size in 2025 | USD 1.29 Billion |
| Market Growth Rate (2026–2036) | CAGR of 9.4% |
| Format | PDF, Excel & Cloud Portal · 265 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Functional Ingredient, Product Type, Application, Distribution Channel, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: functional ingredient, product type, application, distribution channel.
The growth of this market is driven by the profound shift in global consumer attitudes toward food as a vehicle for health management, the accelerating mainstreaming of nutraceutical and functional food concepts across retail channels in developed and emerging markets, and the chocolate industry's successful pivot from positioning its products primarily as indulgent confectionery toward repositioning premium chocolate as a health-associated food that delivers measurable physiological benefits alongside sensory pleasure. Functional chocolates are confectionery products that combine a chocolate base — dark, milk, white, or sugar-free — with bioactive ingredients that provide specific health benefits beyond basic caloric nutrition, including proteins for muscle maintenance and satiety, probiotics and prebiotics for gut microbiome support, vitamins and minerals for micronutrient fortification, antioxidants for cellular protection, adaptogens and herbal extracts for stress modulation and cognitive support, and botanical ingredients including CBD for relaxation and wellness applications. The category encompasses both mass-market fortified chocolate products offered by large multinational confectionery companies and premium artisanal functional chocolate brands that command significant price premiums by emphasizing clean-label ingredient transparency, superfood inclusion, and evidence-based health positioning.
The functional chocolate category occupies a commercially compelling intersection between the established and growing global chocolate confectionery market, valued at over USD 130 billion, and the rapidly expanding functional food and nutraceutical market, which is driven by the same consumer health awareness trends that are reshaping food purchasing behavior across all categories. Chocolate's unique sensory properties — its creamy mouthfeel, complex flavor profile, and deeply established emotional associations with pleasure and reward — give it structural advantages as a delivery vehicle for functional ingredients relative to supplement formats such as capsules, tablets, and unflavored protein powders that many consumers find unappealing or inconvenient. The growing consumer willingness to pay premium prices for chocolate products that combine health benefits with the sensory experience of premium chocolate represents a fundamental market opportunity that has attracted investment from both established confectionery companies and a new generation of health-focused chocolate brands.
The functional chocolates market represents the convergence of two of the most dynamic consumer product categories of the past decade: premium chocolate confectionery and functional food and nutraceutical products. The category has evolved from its origins in simple vitamin-fortified chocolate products and sugar-free diabetic chocolates toward a sophisticated and rapidly diversifying landscape of products that integrate specific bioactive ingredient systems with premium chocolate platforms to deliver targeted health benefits that are communicated to consumers through transparent labeling, evidence-based marketing claims, and the credibility of established functional ingredient brands.
The technical foundation of functional chocolate product development is the successful incorporation of bioactive functional ingredients into chocolate matrices without compromising the taste, texture, and shelf stability that consumers expect from premium chocolate products. Chocolate is a complex colloidal system of cocoa butter, cocoa solids, sugar, and milk solids that is sensitive to temperature, moisture, and ingredient compatibility in ways that create genuine formulation challenges for functional ingredient integration. Proteins added to chocolate formulations must be selected and processed to avoid off-flavors, grittiness, and emulsification disruption that impair the eating experience. Probiotics incorporated into chocolate require microencapsulation protection systems that maintain viable bacterial counts through the high temperatures and humidity fluctuations of chocolate manufacturing, storage, and distribution. Water-soluble vitamins and minerals must be incorporated in forms that resist migration into the chocolate fat phase and maintain bioavailability. Adaptogens and botanical extracts must be introduced in flavor-compatible forms and concentrations that deliver effective doses without overwhelming the chocolate's flavor profile. The development of microencapsulation technologies, encapsulated probiotic preparations, and lipid-coated nutrient delivery systems specifically designed for confectionery matrices has been a critical enabling factor in the category's technical advancement.
The competitive landscape of the functional chocolates market spans three distinct segments that differ in scale, business model, and target consumer. Large multinational confectionery companies including Nestlé, Mars, Mondelez, Hershey, and Ferrero are addressing functional chocolate through product line extensions and acquisitions that add health-positioned variants to their established mainstream chocolate portfolios, targeting mass-market health-interested consumers through conventional grocery retail channels. Mid-tier premium chocolate companies including Lindt and Barry Callebaut are developing high-cacoa-content and functional ingredient enriched products that leverage their premium brand positioning to command higher price points in specialty and department store channels. A rapidly growing ecosystem of specialist functional chocolate brands including Hu Kitchen, Lily's Sweets, Alter Eco, Theo Chocolate, Goodio, and Love Cocoa are building direct-to-consumer and natural food retailer businesses around clean-label, organic, and specifically formulated functional chocolate products that prioritize ingredient transparency and health benefit specificity over broad mass-market distribution.
Report infographic
Market dynamics
5 factors across 3 forcesRising Consumer Demand for Functional Foods and Nutraceutical Products
The primary driver of the functional chocolates market is the structural shift in global consumer food purchasing behavior toward products that deliver nutritional function and health benefits alongside conventional food enjoyment. The global functional food and nutraceutical market has grown from a niche category serving health-conscious early adopters to a mainstream consumer segment that encompasses billions of consumers across all income levels and geographic markets. This growth is driven by demographic aging in developed markets, where older consumers increasingly seek food products that support healthy aging, joint health, cardiovascular function, and cognitive maintenance. It is reinforced by the growing awareness among younger consumers that preventive nutrition practices implemented early in life contribute to long-term health outcomes, creating health-motivated food purchasing behavior across age cohorts rather than being concentrated among elderly populations.
Consumer research consistently demonstrates that the majority of consumers in North America and Europe, and a rapidly growing proportion in Asia-Pacific, actively seek out foods with functional health benefits and are willing to pay meaningful premiums for products that deliver credible health benefit claims backed by ingredient transparency. Chocolate, as one of the most universally beloved food categories globally, is uniquely positioned to benefit from this functional food demand growth, as the combination of established consumer affection for chocolate with the desire for health-beneficial eating creates a consumer acceptance advantage for functional chocolate products relative to functional food formats with lower baseline appeal.
Table of contents
12 chapters · 156 sections · 265 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Functional Ingredient | Protein-Enriched Chocolates | Probiotic and prebiotic chocolates |
| By Product Type | Dark Chocolate | Sugar-free chocolate |
| By Application | General Wellness | Cognitive health |
| By Distribution Channel | Supermarkets and Hypermarkets | Online retail and e-commerce |
By Functional Ingredient
- The protein-enriched chocolates segment is expected to hold the largest share of the functional chocolates market by functional ingredient.
- Protein-fortified chocolate products represent the most commercially mature and broadly distributed functional chocolate category, with established shelf presence in grocery, pharmacy, convenience, and sports nutrition retail channels and strong mainstream consumer recognition of protein content as a desirable nutritional attribute in snack foods.
- The sports nutrition channel, which encompasses protein bars, protein shakes, and protein-enriched snack products, has driven the development and consumer acceptance of high-protein chocolate-flavored and chocolate-coated products, creating an established consumer demand base that specialist functional chocolate brands have translated into premium whole-chocolate products with higher cocoa content and cleaner ingredient profiles.
- The macronutrient context of protein enrichment — supporting muscle maintenance, satiety, and metabolic health — resonates across a broad consumer base extending well beyond dedicated sports nutrition consumers to include weight management-motivated consumers, aging adults seeking to maintain muscle mass, and general health-conscious consumers who have incorporated higher protein intake as a dietary priority.
- However, the probiotic and prebiotic chocolates segment is expected to witness the fastest growth during the forecast period.
- The gut health and microbiome wellness category has emerged as one of the highest-growth segments of the functional food and supplement market globally, driven by rapidly expanding consumer awareness of the gut microbiome's role in immune function, mental health through the gut-brain axis, metabolic health, and overall wellness.
- The successful translation of probiotic supplementation from yogurt and capsule formats into premium chocolate delivery systems addresses a genuine consumer desire for enjoyable, convenient, and consistent probiotic intake that yogurt cannot satisfy for consumers who dislike dairy or do not consume yogurt regularly, and that supplement capsules cannot deliver with the same daily compliance motivation as a premium chocolate product.
- Microencapsulation technology advances that maintain probiotic viability through chocolate manufacturing and extended shelf life are enabling the credible development of products with clinically relevant probiotic doses in chocolate formats, providing the technical foundation for rapid commercial expansion of this segment.
By Product Type
- The dark chocolate segment is expected to hold the largest share of the functional chocolates market by product type.
- Dark chocolate's dominant position in the functional chocolate category reflects its established health-positive consumer image, grounded in well-publicized scientific research demonstrating that cocoa flavanols present at high concentrations in dark chocolate deliver clinically meaningful benefits for cardiovascular health through improved endothelial function and blood flow regulation, for cognitive function through cerebral blood flow enhancement and neuroprotective mechanisms, and for antioxidant protection against oxidative stress.
- This research-supported health positioning gives dark chocolate a natural credibility advantage as a base format for functional chocolate products that is not shared by milk chocolate or white chocolate, which contain lower or negligible cocoa flavanol concentrations.
- The compatibility of dark chocolate's intense and complex flavor profile with the earthy, bitter, and botanical flavor notes of adaptogenic and superfood functional ingredients — including mushroom extracts, ashwagandha, turmeric, and matcha — further reinforces dark chocolate's dominant position in the premium functional ingredient chocolate category.
- However, the sugar-free chocolate segment is expected to witness the fastest growth during the forecast period.
- The convergence of rising diabetes prevalence, mainstream adoption of low-carbohydrate dietary patterns, and significant technical improvement in the taste quality of sugar-free chocolate formulations is driving rapid growth in consumer demand for sugar-free functional chocolate options.
- Brands including Lily's Sweets, ChocZero, and Hu Kitchen's sugar-free line have demonstrated the commercial viability of premium sugar-free functional chocolate at retail price points of USD 4 to 8 per bar, with strong repeat purchase rates indicating high consumer satisfaction with product quality.
- The combination of sugar-free formulation with functional ingredient addition — protein fortification for diabetic consumers managing both sugar intake and muscle mass, or adaptogen inclusion for consumers following ketogenic diets who seek stress and cognitive support — creates compound functional value propositions that justify the premium pricing of sugar-free functional chocolate products.
By Application
- The general wellness segment is expected to hold the largest share of the functional chocolates market by application.
- General wellness-positioned functional chocolate products target the broadest and most commercially accessible consumer segment: health-conscious individuals who seek products that support their overall wellbeing without addressing a specific clinical condition or sports performance objective.
- This broad positioning is the most commercially practical approach for functional chocolate brands seeking significant retail distribution and mass consumer appeal, as it does not require consumers to self-identify with a specific health condition or nutrition protocol to consider the product relevant to their needs.
- Products positioned for general wellness leverage the established health associations of dark chocolate's cocoa flavanols, combined with broadly appealing functional additions such as vitamins, minerals, and general antioxidant-rich superfoods, to create health-positive products that health-conscious mainstream consumers can incorporate into their daily routines without requiring specific wellness knowledge or health objectives.
- However, the cognitive health application is expected to witness the fastest growth during the forecast period.
- The rapid expansion of consumer interest in cognitive performance, mental focus, memory support, and long-term neuroprotection is creating strong demand for functional food products that credibly address these outcomes.
- Functional chocolate products incorporating cocoa flavanols at concentrations demonstrated in clinical studies to improve cerebral blood flow and cognitive test performance, combined with nootropic additives including lion's mane mushroom standardized extract, phosphatidylserine, bacopa monnieri, and citicoline, represent a compelling and differentiated product proposition that addresses growing consumer anxiety about cognitive health.
- The aging demographic in developed markets, where concerns about age-related cognitive decline are motivating active preventive nutrition strategies, and the performance-oriented millennial and Gen Z consumer segments seeking cognitive optimization products for professional and academic performance, represent a large and commercially attractive bimodal target audience for cognitive health functional chocolate products.
By Distribution Channel
- The supermarkets and hypermarkets segment is expected to hold the largest share of the functional chocolates market by distribution channel.
- Mass grocery retail remains the highest-volume distribution channel for chocolate confectionery globally, and functional chocolate products with sufficient brand recognition and mainstream consumer appeal to secure grocery retail shelf placement achieve the highest absolute sales volumes of any distribution channel.
- Large confectionery companies including Nestlé, Mars, Mondelez, and Hershey leverage their established retail relationships and trade marketing infrastructure to secure prominent shelf positioning for their functional chocolate product line extensions in mainstream grocery channels, reaching casual health-interested consumers who encounter functional chocolate products during routine grocery shopping rather than specifically seeking them out in specialty channels.
- However, the online retail and e-commerce segment is expected to witness the fastest growth during the forecast period.
- The structural advantages of digital commerce for premium and specialist functional chocolate brands are compelling: direct-to-consumer online channels enable detailed product story communication about ingredient sourcing, functional benefits, and clinical evidence; they allow subscription commerce models that provide recurring revenue and high customer retention; they support targeted marketing to health-oriented consumer communities through social media, wellness influencer partnerships, and search engine marketing; and they provide access to national and international consumer audiences for brands that lack the scale to secure conventional retail distribution.
- The pandemic-driven acceleration of online grocery and specialty food purchasing created lasting behavioral changes in consumer willingness to purchase premium food products online, and functional chocolate brands have been among the principal beneficiaries of this behavioral shift.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to hold the largest share of the global functional chocolates market. The United States is the primary driver of North American market leadership, representing the most commercially developed functional food market globally in terms of consumer awareness, retail infrastructure for specialty and premium functional products, and willingness to pay premium prices for health-positioned food innovations. The U.S. natural and specialty food retail channel, anchored by retailers including Whole Foods Market, Sprouts Farmers Market, and Natural Grocers, provides the retail infrastructure through which premium functional chocolate brands achieve their initial commercial traction and brand building before transitioning to broader conventional grocery distribution. The rapid growth of direct-to-consumer e-commerce for premium food products in the United States, combined with the country's sophisticated social media and wellness influencer marketing ecosystem, has enabled a generation of specialist functional chocolate brands to build significant consumer followings and revenue bases without the capital requirements of conventional retail distribution programs. Canada contributes meaningfully to North American market leadership through its health-conscious consumer base, well-developed natural food retail channel, and growing direct-to-consumer digital commerce infrastructure for premium food products. Canadian consumers demonstrate strong alignment with U.S. functional food consumption trends, with comparable willingness to pay premium prices for clean-label, organic, and functional chocolate products, and the cross-border availability of major U.S. functional chocolate brands in Canadian natural food retail and e-commerce channels supports market development without the market entry investment requirements of genuinely separate international expansion.
Asia-Pacific
Fastest growthAsia-Pacific is expected to witness the highest growth rate in the functional chocolates market during the forecast period. This growth is driven by the combination of rapidly rising premium food consumption in China, India, Japan, and South Korea, the strong cultural tradition of food-as-medicine thinking in Asian markets that creates favorable consumer receptivity to functional benefit claims on food products, and the explosive growth of health and wellness consumer segments in rapidly urbanizing middle-class populations across the region. Japan represents the most commercially mature functional food market within Asia-Pacific, with a decades-long history of Foods for Specified Health Uses (FOSHU) and Foods with Functional Claims (FFC) regulatory frameworks that have established strong consumer familiarity with functional food concepts and health claim substantiation requirements. Japanese consumers demonstrate high willingness to pay premium prices for functional food products with credible health benefit claims, and the country's sophisticated confectionery market and strong premium chocolate culture create favorable conditions for functional chocolate market development. South Korea's highly health-conscious urban consumer base, driven by the country's strong beauty and wellness culture, is creating rapidly growing demand for functional food products including functional chocolates addressing skin health, weight management, and cognitive performance. China's functional food market is growing rapidly as rising incomes and health awareness among urban middle-class consumers drive demand for premium health-positioned food products, with functional chocolate benefiting from the premium positioning of chocolate confectionery among Chinese consumers for whom high-quality imported and domestic premium chocolate carries strong aspirational brand associations alongside health benefit communication. India's functional chocolate market is at an earlier stage of development but is growing rapidly among urban, educated, and health-conscious consumer segments, supported by the country's well-developed tradition of herbal and Ayurvedic functional ingredients — including ashwagandha and turmeric — that are increasingly incorporated into functional chocolate products targeting Indian consumers.
Competitive landscape
- Nestlé S.A.
- Mars, Incorporated
- Mondelez International
- Lindt & Sprüngli
- Barry Callebaut AG
- Hershey Company
- Ferrero Group
- Hu Kitchen
- Endangered Species Chocolate
- Lily's Sweets
- Alter Eco Foods
- Theo Chocolate
- Goodio Chocolate
- Love Cocoa
- Taza Chocolate
Frequently asked questions
The global functional chocolates market is expected to grow from USD 1.47 billion in 2026 to USD 3.62 billion by 2036.
Cite this report
Meticulous Research. (2026). Functional Chocolates Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MR-1848). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/functional-chocolates-market-6531