Enterprise Collaboration Tools Market (2026-2036)
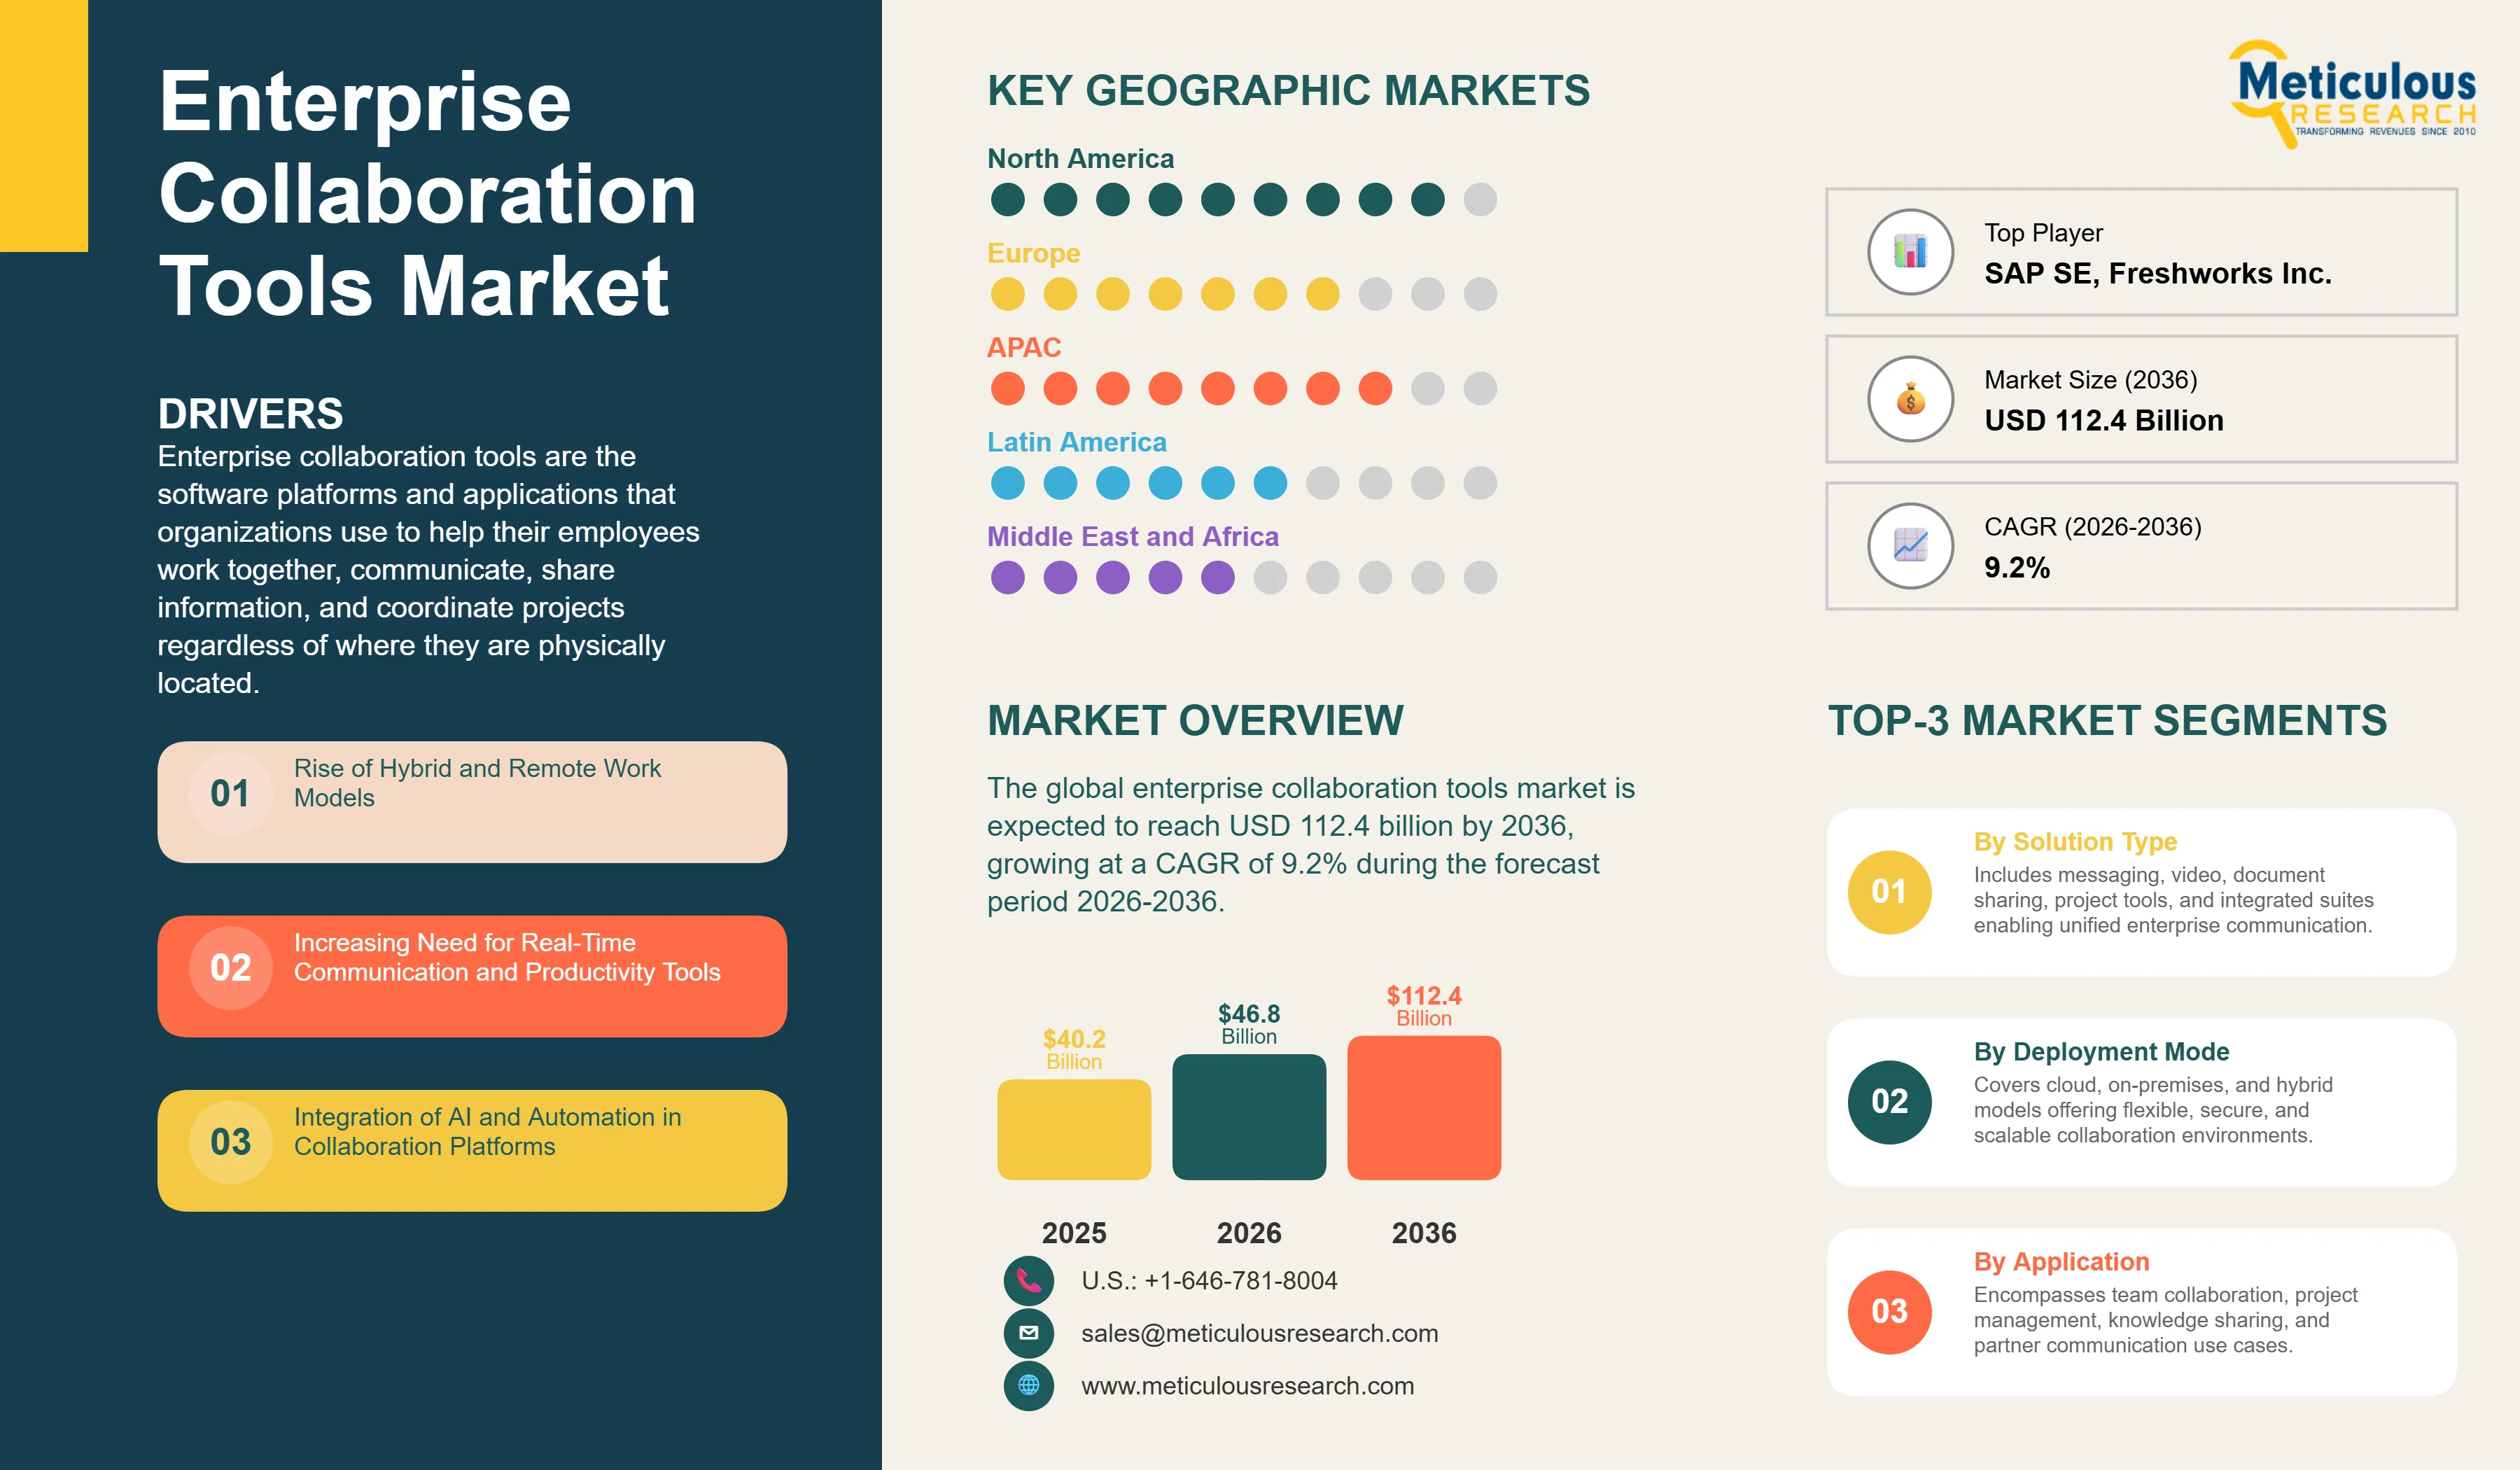
The global enterprise collaboration tools market was valued at USD 40.2 billion in 2025. This market is expected to reach USD 112.4 billion by 2036 from an estimated USD 46.8 billion in 2026, growing at a CAGR of 9.2% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 310
- Format
- PDF + Excel
- Report ID
- MR-1939
- Base year
- 2025
- 2025 · BASELINE
- $40.20B
- 2036
- $112.4B
- CAGR 2026–2036
- 9.2%
2025 baseline · 2026–2036 forecast at 9.2% CAGR · hover a bar for the value
Key highlights
The global enterprise collaboration tools market is projected to reach USD 112.4 billion by 2036.
The market is expected to grow at a CAGR of 9.2% during the forecast period 2026-2036.
The global enterprise collaboration tools market was valued at USD 40.2 billion in 2025 and is estimated to reach USD 46.8 billion in 2026.
North America is expected to dominate the global enterprise collaboration tools market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By solution type, the integrated collaboration suites segment is expected to hold the largest share of the market in 2026, while the project and workflow collaboration tools segment is projected to register the highest CAGR during the forecast period.
By deployment mode, the cloud-based segment is expected to hold the largest share in 2026, while the hybrid deployment segment is projected to register the highest CAGR during the forecast period.
By application, the internal team collaboration segment is expected to hold the largest share in 2026, while the knowledge sharing and training segment is projected to register the highest CAGR during the forecast period.
By enterprise size, the large enterprises segment is expected to hold the largest share in 2026, while the SMEs segment is projected to register the highest CAGR during the forecast period.
By industry vertical, the IT and telecommunications segment is expected to hold the largest share in 2026, while the healthcare segment is projected to register the highest CAGR during the forecast period.
By feature type, the real-time collaboration features segment is expected to hold the largest share in 2026, while the AI and automation features segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 112.4 Billion |
| Market Size in 2026 | USD 46.8 Billion |
| Market Size in 2025 | USD 40.2 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 9.2% |
| Format | PDF, Excel & Cloud Portal · 310 pages |
| Dominating Solution Type | Integrated Collaboration Suites |
| Fastest Growing Solution Type | Project and Workflow Collaboration Tools |
| Dominating Deployment Mode | Cloud-Based |
| Fastest Growing Deployment Mode | Hybrid Deployment |
| Dominating Application | Internal Team Collaboration |
| Fastest Growing Application | Knowledge Sharing and Training |
| Dominating Enterprise Size | Large Enterprises |
| Fastest Growing Enterprise Size | Small & Medium Enterprises (SMEs) |
| Dominating Industry Vertical | IT & Telecommunications |
| Fastest Growing Industry Vertical | Healthcare |
| Dominating Feature Type | Real-Time Collaboration Features |
| Fastest Growing Feature Type | AI and Automation Features |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: solution type, deployment mode, application, enterprise size, industry vertical.
Enterprise collaboration tools are the software platforms and applications that organizations use to help their employees work together, communicate, share information, and coordinate projects regardless of where they are physically located. These tools range from chat and messaging applications like Microsoft Teams and Slack that allow colleagues to have instant conversations, to video conferencing platforms like Zoom that connect teams face-to-face across distances, to document sharing systems like Google Workspace and SharePoint that let multiple people work on the same file simultaneously, to project management tools like Asana and Monday.com that help teams track tasks, deadlines, and progress. Taken together, these tools form the digital workplace infrastructure that enables modern organizations to function effectively across offices, homes, and multiple countries.
The market is growing because the way people work has fundamentally changed, and there is no going back to purely office-based working for most knowledge workers. The COVID-19 pandemic accelerated a shift toward remote and hybrid working that was already underway, and the majority of knowledge workers now expect to have the flexibility to work from various locations as part of their employment package. Organizations that have discovered that remote and hybrid teams can maintain or even improve productivity with the right collaboration tools in place are not reverting to requiring full-time office attendance, meaning the demand for enterprise collaboration software is now structural and permanent rather than temporary. Additionally, the rapid integration of artificial intelligence into collaboration platforms is creating a new category of AI-assisted work that promises to automate routine tasks, summarize long conversation threads, generate meeting notes automatically, and provide intelligent assistance to workers across every type of collaboration activity, making these tools increasingly indispensable to daily work.
Two significant opportunities are shaping the next phase of market growth. The integration of AI copilot features into existing collaboration platforms, most visibly through Microsoft Copilot integrated with Teams and Office 365 and Google Gemini integrated with Google Workspace, is creating a compelling upgrade incentive for existing enterprise customers to move to higher-priced premium tiers that include AI features. This AI-driven upsell dynamic is already generating significant revenue growth at Microsoft and Google and is being rapidly replicated across the broader collaboration software market. In addition, the very large number of small and medium-sized enterprises globally that still rely on basic email and consumer-grade communication tools rather than purpose-built enterprise collaboration platforms represents a large and largely untapped market that is being addressed by more affordable cloud-based solutions and is expected to be a significant growth driver throughout the forecast period.
Market dynamics
6 factors across 3 forcesRise of Hybrid and Remote Work Models
The most powerful and durable driver of the enterprise collaboration tools market is the structural shift to hybrid and remote working that has permanently changed how knowledge workers work and what technology they need to do so effectively. Before 2020, most organizations relied on physical proximity and in-person interaction as the primary mechanism for team coordination, with digital collaboration tools playing a supporting rather than central role. The COVID-19 pandemic forced essentially the entire global knowledge workforce to rely entirely on digital collaboration tools overnight, and the experience demonstrated that well-equipped remote teams could maintain productivity across most types of knowledge work. The result is that the majority of knowledge workers in developed markets now work in hybrid arrangements that combine some office time with regular remote working, and both organizations and employees expect the digital collaboration infrastructure to support seamless and effective work regardless of physical location. This expectation has raised the minimum acceptable standard for enterprise collaboration tooling across virtually every organization and is generating sustained investment in upgrading, expanding, and maintaining enterprise collaboration software as a core operational infrastructure rather than a discretionary technology.
Integration of AI and Automation in Collaboration Platforms
The integration of AI capabilities into enterprise collaboration platforms is creating the most significant product upgrade cycle in the market's history, as organizations that have already standardized on a collaboration platform are being presented with compelling AI-powered feature upgrades that justify moving to premium pricing tiers and accelerating platform adoption across their workforces. The productivity value of AI meeting summaries, intelligent email drafting, automated document generation, and smart search across organizational knowledge is measurable and significant, providing the ROI justification that enterprise procurement teams require for technology spending approvals. Microsoft's early commercial success with Copilot for Microsoft 365, which achieved USD 1 billion in annual revenue run rate faster than any other Microsoft product in the company's history, demonstrates the commercial appetite for AI-enhanced collaboration features among enterprise customers and is creating competitive urgency for every other collaboration platform to invest in equivalent AI capabilities.
Table of contents
14 chapters · 191 sections · 310 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Solution Type | Integrated Collaboration Suites | Project and workflow collaboration tools |
| By Deployment Mode | Cloud-Based | Hybrid deployment |
| By Application | Internal Team Collaboration | Knowledge sharing and training |
| By Industry Vertical | — | Healthcare |
By Solution Type
- Integrated Collaboration Suites to Dominate
- The global market for enterprise collaboration tools is segmented into communication and messaging tools, video conferencing and virtual meeting tools, content and document collaboration tools, project and workflow collaboration tools, enterprise social networks and engagement platforms, and integrated collaboration suites.
- The integrated collaboration suites segment is expected to account for the largest share of the global enterprise collaboration tools market.
- Integrated suites including Microsoft 365 with Teams, Google Workspace, and Salesforce's integrated platform represent the highest-revenue category because they combine multiple collaboration capabilities in a single subscription, capture the entire collaboration budget of an enterprise rather than a single use case, and benefit from the consolidation trend that is directing enterprise spending toward fewer, more comprehensive platforms.
- Microsoft 365 and Google Workspace together serve hundreds of millions of users globally and represent by far the largest revenue pools in the collaboration software market.
- However, the project and workflow collaboration tools segment is projected to register the highest CAGR during the forecast period.
- The explosion of knowledge work driven by digital transformation across all industries is creating growing demand for structured project management and workflow automation tools that help teams coordinate complex multi-step work more efficiently.
- Asana, Monday.com, and Atlassian's Jira and Confluence products are growing rapidly as organizations recognize that unstructured chat and document sharing tools are insufficient for managing complex cross-functional projects and need dedicated workflow and project coordination capabilities.
By Deployment Mode
- Cloud-Based to Hold the Largest Share
- The global market for enterprise collaboration tools is segmented into cloud-based, on-premises, and hybrid deployment.
- The cloud-based segment is expected to account for the largest share of the global enterprise collaboration tools market.
- Cloud-based deployment is overwhelmingly the default choice for enterprise collaboration software in the current market, because collaboration tools fundamentally need to be accessible from anywhere and on any device, which is only practically achievable through cloud delivery.
- The continuous feature updates, automatic scaling, and global availability that cloud platforms deliver without customer-managed infrastructure maintenance have made on-premises alternatives progressively less competitive, and even large enterprises that were previously committed to on-premises IT are migrating their collaboration workloads to cloud platforms.
- However, the hybrid deployment segment is projected to register the highest CAGR during the forecast period.
- Some regulated industries including financial services, healthcare, and government have data residency and sovereignty requirements that prevent them from storing all communications and documents in public cloud infrastructure, but want the user experience and features of cloud collaboration platforms.
- Hybrid deployments that store sensitive data on-premises or in private cloud environments while using cloud-delivered application interfaces are growing as a compromise that meets regulatory requirements without sacrificing user experience.
By Application
- Internal Team Collaboration to Hold the Largest Share
- The internal team collaboration segment is expected to account for the largest share of the global enterprise collaboration tools market.
- Internal team communication and coordination between colleagues is the most fundamental and highest-frequency use case for enterprise collaboration tools, covering the daily chat messages, video calls, document sharing, and meeting coordination that constitute the majority of collaboration activity across every organization.
- This is also the application where the network effects of having all employees on the same platform are strongest, creating winner-take-most dynamics that benefit the dominant platform providers.
- However, the knowledge sharing and training segment is projected to register the highest CAGR during the forecast period.
- Organizations are increasingly recognizing that much of their institutional knowledge is trapped in individual employees' heads or in unstructured conversation threads, and that capturing and making this knowledge accessible through structured knowledge management and learning platforms has significant productivity and resilience value.
- The combination of AI-powered knowledge discovery, which can find relevant information from across an organization's communications and documents based on a natural language query, with formal learning management system capabilities is creating a new and fast-growing category of knowledge collaboration tools.
By Industry Vertical
- IT and Telecommunications to Hold the Largest Share
- The IT and telecommunications segment is expected to account for the largest share of the global enterprise collaboration tools market.
- Technology companies are the heaviest users of enterprise collaboration tools per employee, driven by the nature of software development and technology work which is inherently collaborative, project-based, and often distributed across global teams and time zones.
- The IT sector adopted cloud collaboration tools earliest and at highest penetration rates, and technology companies typically spend more per employee on collaboration software than any other industry vertical, making them the highest-revenue vertical despite not necessarily being the largest employer.
- However, the healthcare segment is projected to register the highest CAGR during the forecast period.
- Healthcare organizations are undergoing significant digital transformation of their communication and coordination workflows, driven by the need to improve care coordination across multidisciplinary clinical teams, the challenge of connecting administrative staff working remotely with clinical staff on-site, and the growing use of telehealth that requires robust video communication capabilities.
- The complexity of healthcare compliance requirements, including HIPAA in the U.S. and equivalent regulations in other markets, creates demand for specialist healthcare collaboration platforms with built-in compliance features that support faster growth of purpose-built healthcare collaboration solutions.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global enterprise collaboration tools market. The United States is home to virtually all of the world's leading enterprise collaboration software companies, including Microsoft, Google, Slack/Salesforce, Zoom, Atlassian, Asana, Monday.com, Dropbox, Box, and RingCentral, and the U.S. enterprise software market is the world's largest and most mature. American enterprises were among the first to broadly adopt cloud-based collaboration tools, and the U.S. knowledge worker population, which numbers in the tens of millions across technology, financial services, healthcare, professional services, and media industries, represents the highest-spending collaboration software customer base in the world. The strong culture of flexible and remote working in the U.S. technology sector, which has been a model for broader adoption across the economy, has maintained high levels of collaboration tool investment even as office attendance has partially recovered from pandemic lows. Canada's advanced technology sector in cities including Toronto, Vancouver, and Montreal contributes additional North American market demand, with strong Canadian adoption of U.S.-origin collaboration platforms.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific enterprise collaboration tools market is expected to grow at the fastest CAGR during the forecast period. Asia-Pacific is the world's largest and fastest-growing region for enterprise software adoption more broadly, and its diverse range of markets from the technologically sophisticated workforces of Japan, South Korea, Singapore, and Australia to the very large and rapidly digitalizing economies of India, China, Indonesia, and Vietnam collectively represent an enormous and growing addressable market for enterprise collaboration tools. India's very large and globally connected IT services industry, which provides software development and business process services to clients worldwide and employs millions of knowledge workers who work across time zones with distributed international teams, is one of the most intensive users of enterprise collaboration tools in the world and is a major demand driver for the Asia-Pacific market. China's large enterprise software market has significant domestic collaboration platform alternatives including DingTalk from Alibaba, WeCom from Tencent, and Feishu from ByteDance that compete with international platforms, but the growing international business activities of Chinese enterprises and the subsidiaries of multinational companies operating in China generate meaningful demand for global platform adoption. Southeast Asian economies including Indonesia, Vietnam, and Thailand are experiencing rapid enterprise software adoption as their business communities grow and digitalize.
Europe
Europe is a large and sophisticated enterprise collaboration tools industry with high adoption rates across the UK, Germany, France, the Netherlands, and Scandinavia. European enterprises were significant early adopters of cloud collaboration tools, particularly Zoom and Microsoft Teams during the pandemic, and the region's strong emphasis on data privacy under GDPR has created demand for collaboration platforms with strong data governance, geographic data residency options, and privacy-by-design features that European enterprises and regulators require. Several European countries including Germany and the Netherlands have strong digital workplace cultures that support high per-user collaboration software spending, and the European public sector including government ministries, healthcare systems, and educational institutions represents a large and growing customer base for compliant and security-certified collaboration platforms.
Latin America
Latin America and the Middle East and Africa are growing collaboration markets as enterprise software adoption accelerates alongside economic development in these regions.
Competitive landscape
- Microsoft Corporation (U.S.)
- Google LLC (U.S.)
- Slack Technologies/Salesforce (U.S.)
- Zoom Video Communications Inc. (U.S.)
- Cisco Systems Inc. (U.S.)
- Atlassian Corporation Plc (Australia/U.S.)
- Asana Inc. (U.S.)
- Monday.com Ltd. · Israel
- Dropbox Inc. (U.S.)
- Box Inc. (U.S.)
- SAP SE · Germany
- IBM Corporation (U.S.)
- RingCentral Inc. (U.S.)
- Zoho Corporation Pvt. Ltd. · India
- Freshworks Inc. (U.S./India)
Frequently asked questions
The global enterprise collaboration tools market is expected to reach USD 112.4 billion by 2036 from an estimated USD 46.8 billion in 2026, at a CAGR of 9.2% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Enterprise Collaboration Tools Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1939). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/enterprise-collaboration-tools-market-6622