Endoscopic Closure Devices Market (2026-2036)
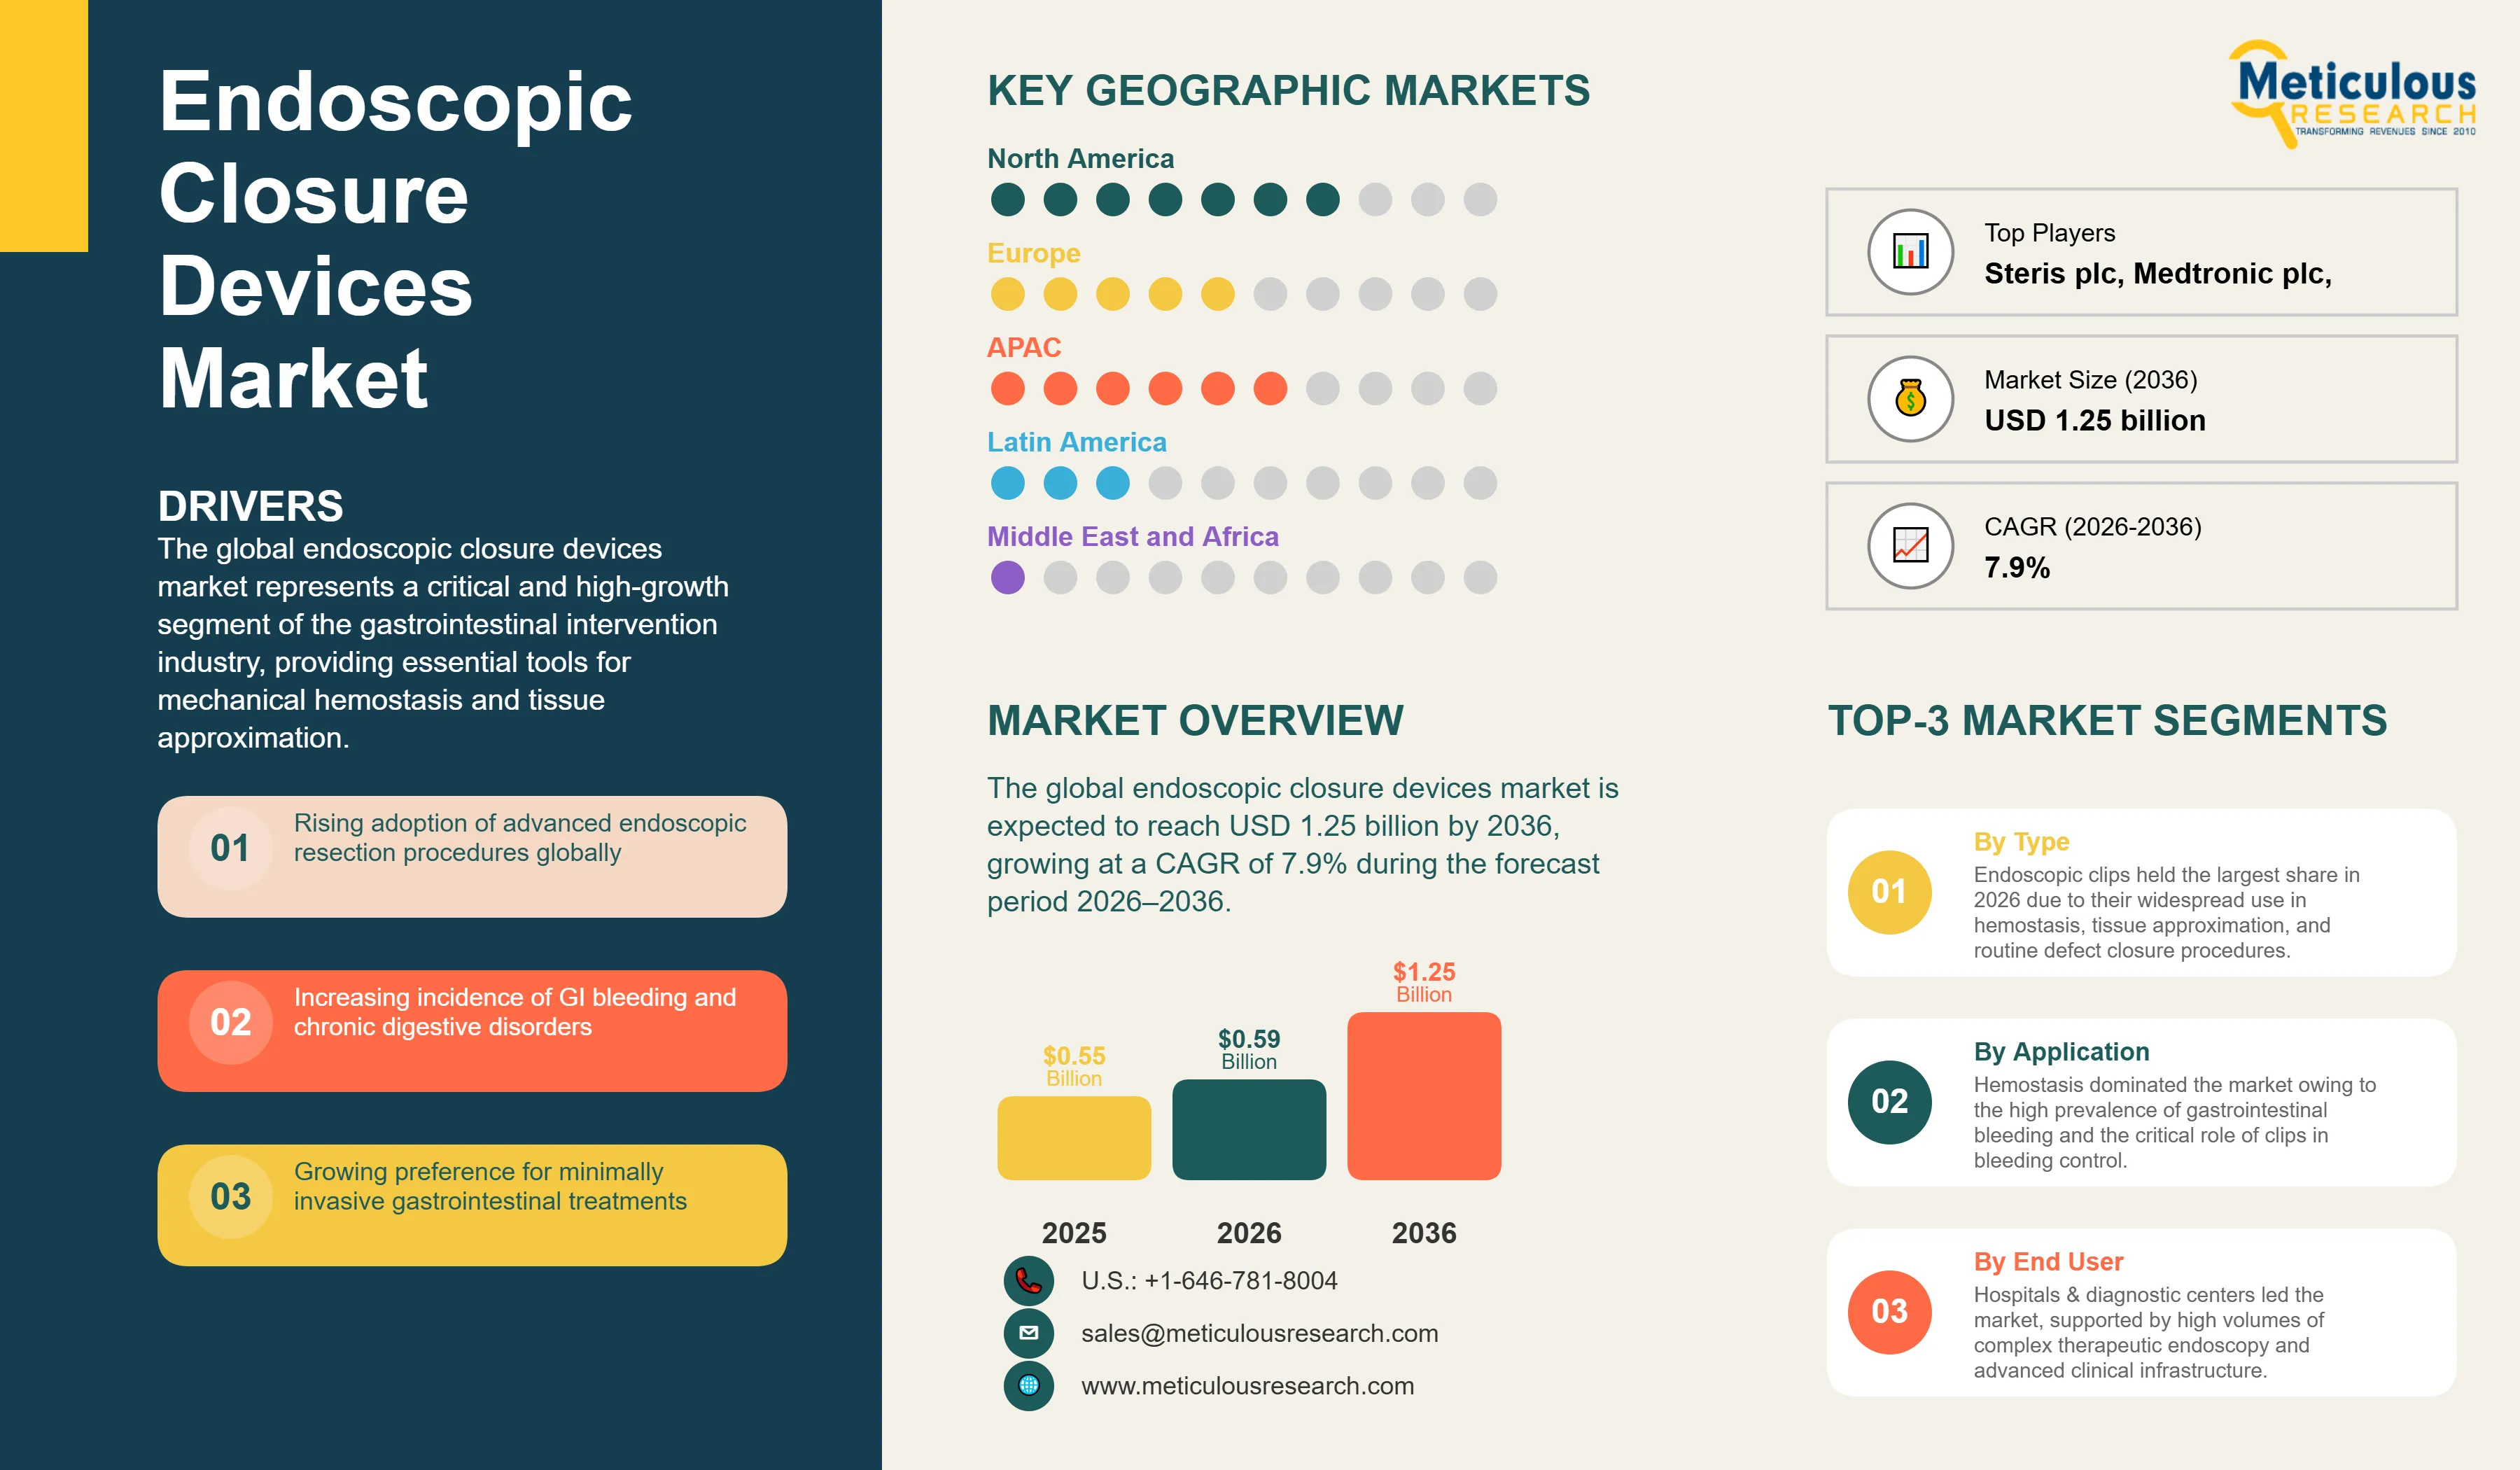
The global endoscopic closure devices market is estimated to be USD 0.59 billion in 2026. This market is expected to reach USD 1.25 billion by 2036, growing at a CAGR of 7.9% during the forecast period 2026–2036.
- Published
- Jun 2026
- Pages
- 271
- Format
- PDF + Excel
- Report ID
- MRHC - 1042086
- Base year
- 2025
- 2026 · ESTIMATED
- $590.0M
- 2036
- $1.25B
- CAGR 2026–2036
- 7.9%
2025 baseline · 2026–2036 forecast at 7.9% CAGR · hover a bar for the value
Key highlights
The global endoscopic closure devices market is projected to reach USD 1.25 billion by 2036, growing at a CAGR of 7.9% during the forecast period 2026–2036.
North America is expected to dominate the global market in 2026, driven by high prevalence of gastrointestinal diseases and established reimbursement for therapeutic endoscopy.
Asia Pacific is projected to witness the fastest growth, fueled by high gastric cancer incidence and advanced resection techniques in Japan, South Korea, and China.
By product type, the endoscopic clips segment is expected to hold the largest share in 2026, as the standard-of-care tool for routine hemostasis and mucosal approximation.
By application, the hemostasis segment is expected to account for the largest share in 2026, given the critical role of clips in managing acute gastrointestinal bleeding.
By end user, the hospitals & diagnostic centers segment is expected to hold the largest share in 2026, as the primary setting for complex therapeutic endoscopic procedures.
Key players operating in the global market include Olympus Corporation, Boston Scientific Corporation, Cook Medical, Ovesco Endoscopy AG, and Steris plc.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 590.0 million |
| Market Size (2036) | USD 1.25 billion |
| CAGR (2026–2036) | 7.9% |
| Format | PDF, Excel & Cloud Portal · 271 pages |
| Segments Covered | By Product Type · By Application · By End User |
| Key Companies | Olympus Corporation, Boston Scientific Corporation (US), Cook Medical (US), Ovesco Endoscopy AG, Steris plc (Ireland/US), Medtronic plc, ConMed Corporation (US), Fujifilm Holdings Corporation, Hoya Corporation (PENTAX Medical), Teleflex Incorporated (US), Apollo Endosurgery, Inc. (US/Boston Scientific), Micro-Tech (Nanjing) Co., Ltd., Wilson Instruments (SHA) Co., Ltd., G-Flex S.A., Medi-Globe GmbH, Endo-Technik W. Griesat GmbH, US Endoscopy (Steris) (US), Cantel Medical Corp. (Steris) (US), B. Braun Melsungen AG, Laborie Medical Technologies |
Report overview
Segments covered: product type, application, end user.
The global endoscopic closure devices market represents a critical and high-growth segment of the gastrointestinal intervention industry, providing essential tools for mechanical hemostasis and tissue approximation. Endoscopic closure devices, ranging from traditional through-the-scope clips to advanced over-the-scope systems and suturing devices, have revolutionized the management of gastrointestinal bleeding, perforations, and mucosal defects. This market is primarily driven by the rising global incidence of gastrointestinal diseases, the increasing adoption of minimally invasive resection techniques (such as EMR and ESD), and the continuous evolution of device designs that offer superior closure strength and precision. According to clinical guidelines from the American Society for Gastrointestinal Endoscopy (ASGE) and the European Society of Gastrointestinal Endoscopy (ESGE), mechanical closure is a cornerstone of safe and effective therapeutic endoscopy. As endoscopists move toward performing more complex endoluminal surgeries, the demand for robust closure systems that can manage full-thickness defects and large mucosal voids is expected to accelerate, supported by technological innovations that enhance device deliverability and procedural efficiency.
Report infographic
Market dynamics
8 factors across 4 forcesRapid Expansion of Complex Endoscopic Resection and Endoluminal Surgery
The increasing adoption of advanced endoscopic resection techniques, such as Endoscopic Mucosal Resection (EMR) and Endoscopic Submucosal Dissection (ESD), is a major driver for the closure devices market. These procedures allow for the minimally invasive removal of early-stage cancers and large polyps but often leave behind significant mucosal defects that require prophylactic closure to prevent delayed complications. Furthermore, the rise of endoluminal surgeries like Peroral Endoscopic Myotomy (POEM) has created a critical need for high-tension closure systems that can safely seal intentional full-thickness incisions, driving the demand for specialized clips and suturing devices in advanced endoscopy units.
Rising Global Incidence of Gastrointestinal Bleeding and Chronic GI Disorders
The high global burden of gastrointestinal bleeding, driven by the widespread use of antiplatelet and anticoagulant medications and the rising prevalence of gastrointestinal disorders, remains a fundamental driver for the market. According to the International Agency for Research on Cancer, approximately 1.9 million new colorectal cancer cases were diagnosed globally in 2022, accelerating colorectal cancer screening and therapeutic endoscopy volumes. Furthermore, approximately 300 million surgical procedures are performed worldwide each year, according to estimates published by the The Lancet Commission on Global Surgery, reflecting the growing demand for minimally invasive interventions. Endoscopic clips remain the standard mechanical tool for achieving rapid hemostasis during acute gastrointestinal bleeding and for tissue closure following polypectomy and other therapeutic endoscopic procedures, creating sustained demand for advanced tissue approximation devices that improve procedural safety and patient outcomes.
Table of contents
12 chapters · 107 sections · 271 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Endoscopic clips | Over-the-scope closure systems |
| By Application | Hemostasis | Endoscopic mucosal defect closure |
| By End User | Hospitals & diagnostic centers | Ambulatory surgical centers (ASCs) |
By Product Type
- The endoscopic clips segment is expected to hold the largest share of the global endoscopic closure devices market in 2026.
- This dominant position is driven by the widespread clinical use of through-the-scope clips for routine hemostasis and small defect closure.
- Their ease of use, established safety profile, and relative cost-effectiveness make them the primary tool in every endoscopy unit.
- However, the over-the-scope closure systems segment is projected to register the highest CAGR during the forecast period.
- The increasing volume of complex endoluminal surgeries and the clinical need for robust, full-thickness closure of large defects and perforations are driving the rapid adoption of these advanced systems.
By Application
- The hemostasis segment is expected to hold the largest share in 2026.
- This segment's leadership is substantiated by the high frequency of gastrointestinal bleeding emergencies, where mechanical closure via clips is a critical and life-saving intervention.
- However, the endoscopic mucosal defect closure segment is projected to grow at the fastest CAGR during the forecast period.
- This growth is fueled by the rising adoption of advanced resection techniques like EMR and ESD, where prophylactic closure of the resulting mucosal voids is increasingly performed to optimize clinical outcomes and prevent delayed complications.
By End User
- The hospitals & diagnostic centers segment is expected to hold the largest share in 2026.
- The vast majority of complex therapeutic and emergency endoscopic procedures are performed in hospital-based units that have the necessary specialized interventional expertise and advanced facilities.
- However, the ambulatory surgical centers (ASCs) segment is projected to register the highest CAGR during the forecast period.
- The ongoing global trend toward moving routine therapeutic gastrointestinal care to outpatient settings to improve healthcare efficiency and reduce costs is driving the rapid growth of this specialized segment.
Geographic analysis
North America
Largest shareNorth America is expected to dominate the global endoscopic closure devices market in 2026. This leading position is attributed to the high prevalence of gastrointestinal diseases, well-established reimbursement models for therapeutic endoscopy, and the early adoption of advanced endoscopic techniques. The region benefits from a highly developed healthcare infrastructure and a strong presence of leading medical device manufacturers. Key companies operating in the North America market are Boston Scientific Corporation, Steris plc, Cook Medical, and Medtronic plc. Largest Share: North America
Asia-Pacific
Fastest growthThe Asia-Pacific region is projected to witness the fastest growth in the global endoscopic closure devices market, with a CAGR of 8-10% during the forecast period. This rapid expansion is driven by the high incidence of gastric and esophageal cancers in countries like Japan, South Korea, and China, where advanced resection techniques (ESD) are widely practiced. Increasing healthcare expenditure and the modernization of endoscopy units are further accelerating the adoption of high-end closure systems. Key companies operating in the Asia Pacific market are Olympus Corporation, Fujifilm Holdings, Fujifilm, and various regional partners for global medical device leaders. Fastest Growing: Asia-Pacific
Competitive landscape
The global endoscopic closure devices market is characterized by a mix of major global medical technology corporations and specialized innovative players focusing on advanced tissue management. Competition is primarily focused on improving the closure strength, deliverability, and precision of clips and suturing systems. Key players are investing in next-generation multi-clip appliers and automated closure devices that can simplify complex procedures. There is also a significant emphasis on developing specialized systems for full-thickness closure and management of large mucosal voids. Strategic developments often involve acquisitions of smaller companies with innovative closure technologies or specialized niche applications. Furthermore, manufacturers are increasingly focusing on providing comprehensive procedural support and training programs for endoscopists, which is critical for gaining clinician trust and maintaining market leadership in an increasingly technically demanding field.
- Olympus Corporation · Japan
- Boston Scientific Corporation (US)
- Cook Medical (US)
- Ovesco Endoscopy AG · Germany
- Steris plc (Ireland/US)
- Medtronic plc · Ireland
- ConMed Corporation (US)
- Fujifilm Holdings Corporation · Japan
- Hoya Corporation (PENTAX Medical) · Japan
- Teleflex Incorporated (US)
- Apollo Endosurgery, Inc. (US/Boston Scientific)
- Micro-Tech (Nanjing) Co., Ltd. · China
- Wilson Instruments (SHA) Co., Ltd. · China
- G-Flex S.A. · Belgium
- Medi-Globe GmbH · Germany
- Endo-Technik W. Griesat GmbH · Germany
- US Endoscopy (Steris) (US)
- Cantel Medical Corp. (Steris) (US)
- B. Braun Melsungen AG · Germany
- Laborie Medical Technologies · Canada
Frequently asked questions
The global market is estimated at USD 0.59 billion in 2026, with a projected growth to USD 1.25 billion by 2036, at a CAGR of 7.9%.
Cite this report
Meticulous Research. (2026). Endoscopic Closure Devices Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1042086). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/endoscopic-closure-devices-market-6769