Directed Energy Weapons Market (2025-2035)
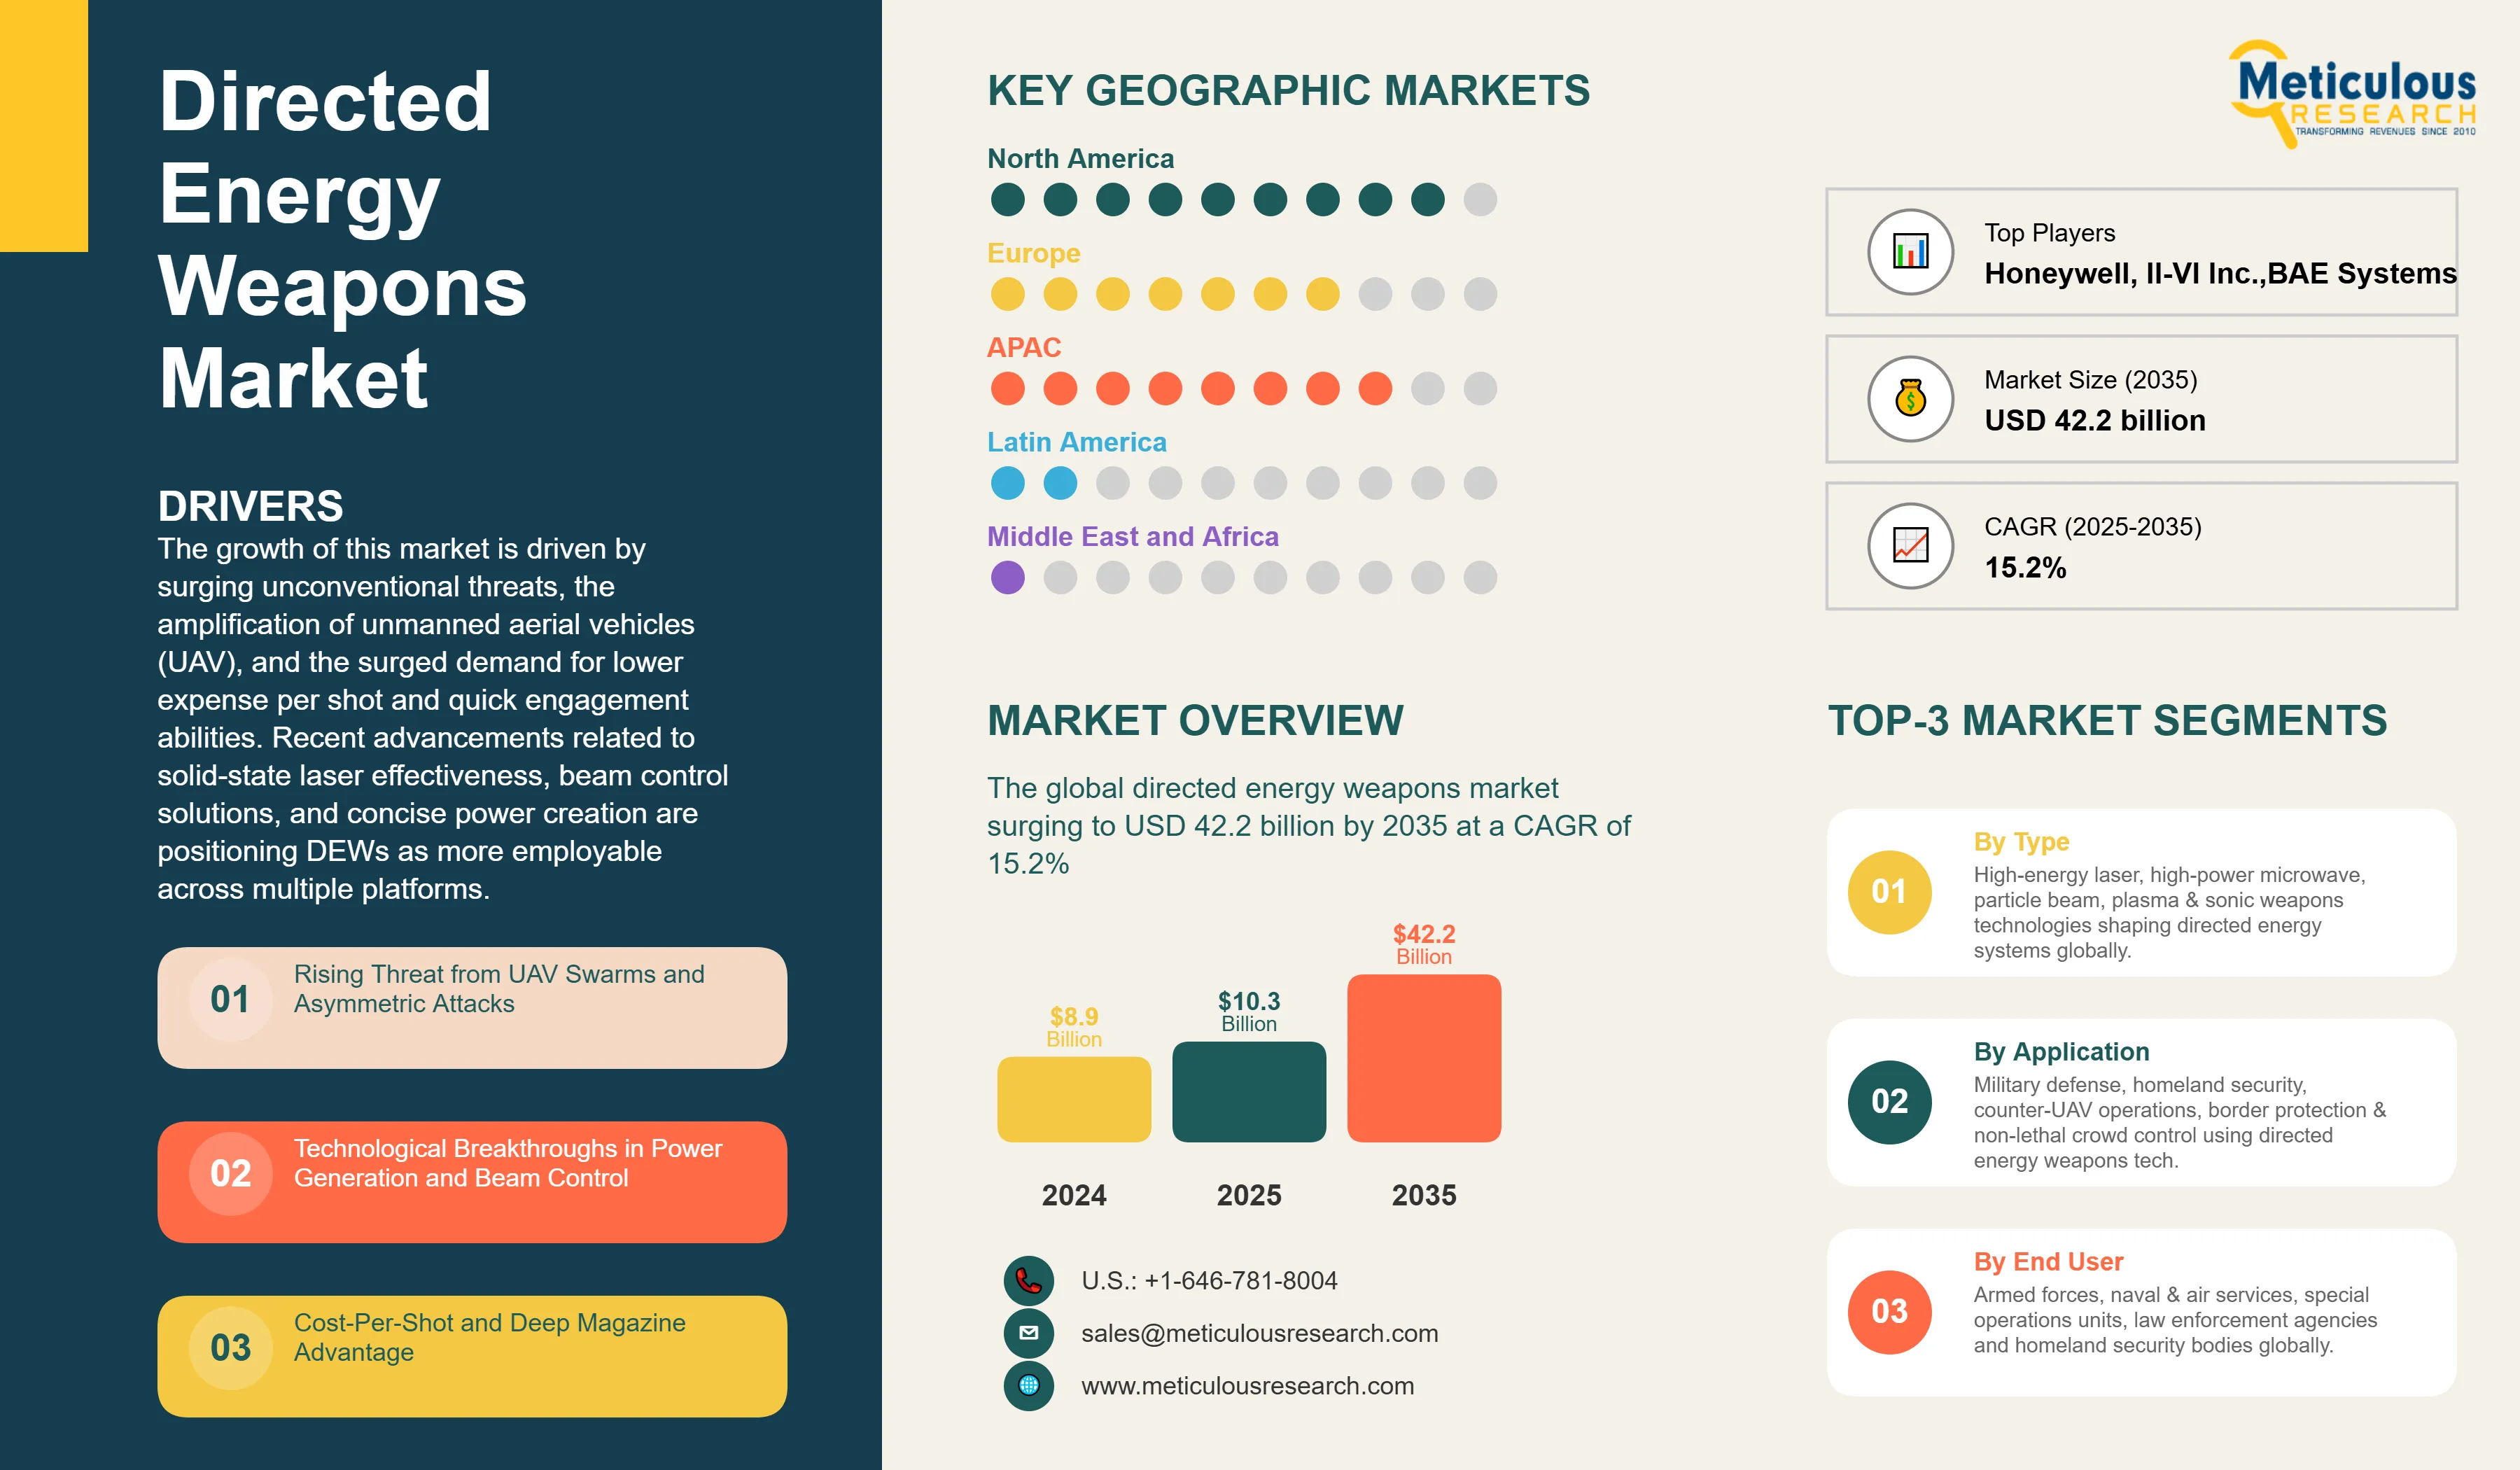
The global directed energy weapons (DEW) market was valued at USD 8.9 billion in 2024 and is projected to reach USD 10.3 billion in 2025, surging to USD 42.2 billion by 2035 at a CAGR of 15.2%.
- Published
- Sep 2025
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRAD - 1041593
- Base year
- 2024
- 2024 · BASELINE
- $8.90B
- 2035
- $42.20B
- CAGR 2025–2035
- 15.2%
2024 baseline · 2025–2035 forecast at 15.2% CAGR · hover a bar for the value
Key highlights
The global directed energy weapons (DEW) market was valued at USD 8.9 billion in 2024 and is projected to reach USD 10.3 billion in 2025, surging to USD 42.2 billion by 2035 at a CAGR of 15.2%.
High Energy Laser (HEL) Dominates While High Power Microwave (HPM) Leads in Growth
North America leads the global DEW market. This dominance is driven by the U.S.’s dominant defense spending and rapid transition of DEW programs from prototypes to fielded systems.
Asia-Pacific is the fastest-growing DEW market, rising with 17.8% CAGR, driven by rising regional tensions, UAV proliferation, and an increasing focus on indigenous defense technologies.
According to the German Federal Ministry of Defence, in 2022, Germany initiated trials of non-lethal DEWs for crowd control and border security, including microwave-based systems for area denial.
Report summary
| Particulars | Details |
|---|---|
| Market size (2025) | USD 10.3 billion |
| Revenue forecast in 2035 | USD 42.2 billion |
| CAGR (2025-2035) | 15.2% |
| Format | PDF, Excel & Cloud Portal · 250 pages |
| Base Year | 2024 |
| Forecast period | 2025 – 2035 |
| Report coverage | Market size and forecast, competitive landscape and benchmarking, country/regional level analysis, key trends, growth drivers and restraints |
| Segments covered | By Technology (High Energy Laser Technology, High Power Microwave Technology, Particle Beam Weapons, Plasma Weapons, and Sonic Weapons), By Lethality (Lethal and Non-Lethal), By Platform (Land-based DEW, Airborne-based DEW, Ship-based DEW, and Space-based DEW), By Application (Defense and Homeland Security), Geography |
| Regional scope | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
| Key companies profiled | Diehl Defense GmbH & Co. KG, Elbit Systems Ltd., Honeywell International Inc., II-VI Inc., BAE Systems Plc, Kord Technologies, L3Harris Technologies Inc., Leonardo S.p.A., Lockheed Martin Corporation, Northrop Grumman Corporation, Rafael Advanced Defense Systems Ltd., Raytheon Technologies Corporation, Rheinmetall AG, Thales Group, The Boeing Company |
| Customization | Comprehensive report customization with purchase. Addition or modification to country, regional & segment scope available |
| Pricing Details | Access customized purchase options to meet your specific research requirements. Explore flexible pricing models |
Report overview
Segments covered: technology, lethality, platform, application.
The growth of this market is driven by surging unconventional threats, the amplification of unmanned aerial vehicles (UAV), and the surged demand for lower expense per shot and quick engagement abilities. Recent advancements related to solid-state laser effectiveness, beam control solutions, and concise power creation are positioning DEWs as more employable across multiple platforms. National initiatives such as the U.S. Army’s Directed Energy Maneuver-Short Range Air Defense (DE M-SHORAD), the U.S. Navy’s HELIOS laser, and the UK’s DragonFire project are fuelling operational fielding.
Moreover, high-energy lasers (HELs) and microwave solutions are increasingly incorporated into naval systems, ground modules, and airborne systems. In 2024, the U.S. Department of Defense sanctioned USD 1.1 billion toward advancements in DEW, reporting a 22% surge as compared to 2022. NATO and Indo-Pacific geographies investing in these modalities, with India and Japan introducing national DEW initiatives. The industry is shifting from research & development to procurement, with functional consistency, power scalability, and platform incorporation being key emphasis.
Report infographic
Key Factors Impacting Global Directed Energy Weapons Market (2025–2035)
Base CAGR: 15.2%
|
Category |
Key Factor |
Short-Term Impact (2025–2028) |
Long-Term Impact (2029–2035) |
Estimated CAGR Impact |
|
Drivers |
1. Rising threat from UAV swarms and asymmetric attacks |
Accelerates procurement of HEL and HPM systems |
Integration into layered defense architectures across multiple domains |
▲ +2.8% |
|
|
2. Technological breakthroughs in power generation and beam control |
Enables mobile and naval platform deployment |
Expands DEW use into tactical and strategic roles |
▲ +2.4% |
|
Restraints |
1. Power Supply Limitations Restrict Deployment on Mobile Platforms |
Limits adoption for nations with smaller defense budgets |
Slows scaling across all service branches |
▼ −1.6% |
|
|
2. Limited all-weather and battlefield reliability |
Requires redundant kinetic systems |
Drives ongoing R&D investment in adaptive optics and atmospheric compensation |
▼ −1.3% |
|
Opportunities |
1. Counter-hypersonic missile interception |
Early-stage R&D programs gaining funding |
Potential game-changer for strategic missile defense |
▲ +1.7% |
|
|
2. Non-lethal DEWs for crowd control and asset protection |
Expands market into law enforcement and border security |
Creates dual-use export opportunities |
▲ +1.4% |
|
Trends |
1. AI-enabled autonomous target acquisition |
Faster and more accurate engagement decisions |
Fully integrated autonomous DEW platforms |
▲ +1.5% |
|
Challenges |
1. Energy storage and power supply limitations |
Limits portability and continuous operation |
Pushes innovation in compact, high-capacity power systems |
▼ −0.9% |
Market dynamics
4 factors across 2 forcesRising Threat from UAV Swarms and Asymmetric Attacks
Small, low-cost drones, often deployed in coordinated swarms, pose a significant challenge to conventional air defense systems by saturating radar coverage and exhausting expensive interceptor missiles. For example, while a missile interceptor can cost up to $100,000 per shot, directed energy weapons such as high-energy lasers can neutralize multiple drones for a few dollars or less per engagement, providing a far more sustainable defense solution. Asymmetric tactics, such as drone-carried explosives and electronic warfare payloads, are increasingly being used by both state and non-state actors, as evidenced by the Middle East and Ukraine conflicts. These evolving threats have accelerated global investment in DEWs, which offer scalable, rapid, and precise countermeasures capable of protecting critical infrastructure, military bases, and naval vessels from swarm-based and unconventional aerial attacks.
Technological Breakthroughs in Power Generation and Beam Control
According to MIT Lincoln Laboratory, in 2024, advancements in beam control and power scaling enabled DEWs to maintain target lock under adverse weather and movement conditions. Adaptive optics and AI-based tracking systems improved hit accuracy in mobile platforms. These improvements address historical limitations of DEWs and support deployment in dynamic combat environments. The U.S. Air Force reported successful airborne trials of HEL systems aboard AC-130 aircraft, marking a milestone in platform versatility.
Cost-Per-Shot and Deep Magazine Advantage
According to RAND Corporation, in 2022, cost-per-shot analysis revealed that high-energy laser systems operate at less than USD 1 per engagement, compared to USD 100,000 for traditional missile interceptors. This cost efficiency is critical for sustained operations, especially in contested environments with frequent threats. DEWs also offer an “unlimited magazine” advantage, as long as power is available, reducing logistical burdens. These attributes are driving procurement interest across NATO and Indo-Pacific defense agencies.
Table of contents
13 chapters · 141 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2035) |
|---|---|---|
| Other segments | High Energy Laser (HEL) | — |
| By Lethality | — | Non-lethal DEWs |
Other segments
- High Energy Laser (HEL) Dominates While High Power Microwave (HPM) Leads in Growth
- The high-energy laser (HEL) systems section is expected to grow at 16% CAGR during the forecast period.
- HELs are being integrated into naval vessels, ground vehicles, and airborne platforms, with power outputs ranging from 20 to 100 kilowatts.
- Lockheed Martin’s HELIOS and Northrop Grumman’s Solid-State Laser Technology Maturation (SSL-TM) programs have demonstrated successful drone and missile interception.
- The U.S. Navy reported a 70% success rate in HEL engagements during live-fire trials, validating their operational readiness.
- HEL systems demonstrate exceptional precision, capable of hitting targets as small as a coin from kilometer distances, as evidenced by the UK's DragonFire laser system trials.
- The technology's ability to engage multiple targets sequentially at the speed of light provides significant tactical advantages over conventional kinetic weapons.
- HEL systems are expected to dominate future procurement due to their adaptability and low logistical footprint.
- Thus, the growing proliferation of aerial threats, particularly drone swarms and precision-guided munitions, positions HEL technology as the optimal solution for modern battlefield requirements, ensuring continued segment leadership throughout the forecast period.
By Lethality
- Non-lethal DEWs Gain Traction for Law Enforcement and Peacekeeping Missions
- Non-lethal DEWs is expected to witness fastest growth at a CAGR of 18% during the forecast period, particularly for crowd control, disabling vehicles, and protecting critical infrastructure.
- According to the United Nations Institute for Disarmament Research (UNIDIR), in 2022, non-lethal DEWs saw increased adoption for law enforcement, border control, and peacekeeping operations.
- Microwave-based systems and dazzlers are being used for area denial, crowd dispersion, and vehicle immobilization.
- The U.K. Home Office deployed portable dazzlers for riot control, while Germany and France initiated trials of microwave DEWs for border security.
- These systems offer reduced risk of fatality and comply with international humanitarian standards.
- Adoption is growing among police forces and UN peacekeeping units, with demand expected to rise amid urban unrest and migration pressures.
- The segment benefits from reduced regulatory constraints compared to lethal weapons systems, facilitating faster approval processes and broader adoption.
- Technological advancements in beam control and power modulation enhance precision and reduce collateral effects, addressing ethical concerns while maintaining operational effectiveness in diverse security scenarios.
Geographic analysis
North America
Largest shareNorth America leads the global DEW market. This dominance is driven by the U.S.’s dominant defense spending and rapid transition of DEW programs from prototypes to fielded systems. According to the U.S. Department of Defense, in 2024, North America accounted for over 50% of global DEW funding, with the Pentagon allocating USD 1.2 billion toward development and deployment. The U.S. Navy, Army, and Air Force are actively integrating DEWs into operational platforms, including destroyers, Stryker vehicles, and AC-130 aircraft. Moreover, according to the U.S. Congressional Research Service, in 2024, the U.S. expanded DEW integration across multiple platforms, including the Army’s DE M-SHORAD system, the Navy’s HELIOS, and the Air Force’s airborne laser trials. The DE M-SHORAD system was deployed on Stryker vehicles and demonstrated successful drone neutralization during live-fire exercises. The Pentagon aims to operationalize DEWs across all services by 2026, with emphasis on interoperability and power scalability. Canada is also investing in DEW research through its Defence Research and Development Canada (DRDC) program, focusing on non-lethal applications for border security. The region benefits from strong public-private partnerships, with firms like Lockheed Martin, Raytheon, and Epirus leading innovation. Joint exercises have validated DEW performance in real-world scenarios, accelerating procurement timelines. North America Leads in Deployment and Funding for Directed Energy Weapons
Asia-Pacific
Fastest growthAsia-Pacific is the fastest-growing DEW market, rising with 17.8% CAGR, driven by rising regional tensions, UAV proliferation, and an increasing focus on indigenous defense technologies. According to the Asia-Pacific Security Studies Journal, in 2023, DEW investments in Asia-Pacific rose by majority of share, driven by rising tensions in the South China Sea and border disputes. India’s Defence Research and Development Organisation (DRDO) initiated trials of a 25-kilowatt laser system for drone defense, while Japan’s Ministry of Defense tested microwave-based DEWs for naval applications. China continues to develop high-power laser systems under its PLA Strategic Support Force, with satellite imagery confirming installations on mobile platforms. Regional governments are prioritizing indigenous capabilities to reduce reliance on Western defense systems, with DEWs seen as strategic assets for asymmetric warfare. The region's strategic focus on indigenous development capabilities is evident through substantial government funding for DEW research and development. Growing collaboration between regional governments and international defense contractors accelerates technology transfer and local manufacturing capabilities, boosting the market growth. In 2025, China dominated the Asia Pacific regional market with a market share of over 40%. China is aggressively developing DEWs for counter-drone, missile defense, and anti-satellite missions, integrating them into its A2/AD strategy. According to the South China Morning Post, in 2023, China’s PLA deployed high-power laser systems for satellite blinding and drone interception, with installations confirmed in Xinjiang and Tibet. The systems are part of China’s broader strategy to counter U.S. space and aerial dominance. The PLA’s Strategic Support Force is leading DEW development, with emphasis on mobility and integration with radar systems. China's space program expansion, including completion of its space station in 2022, incorporates directed energy technologies as symbols of power projection capabilities. The nation's significant defense budget allocation enables large-scale research and development initiatives across high-energy laser systems, high-power microwaves, and particle beam technologies. The investment in DEWs reflects its focus on non-kinetic deterrence and asymmetric capabilities. Domestic production capacity and government investment accelerate deployment cycles, while export potential is growing in markets across Africa, the Middle East, and Southeast Asia. Asia-Pacific Accelerates Indigenous DEW Programs Amid Regional Tensions China Develops High-Power Laser Systems for Strategic Deterrence
Europe
According to the German Federal Ministry of Defence, in 2022, Germany initiated trials of non-lethal DEWs for crowd control and border security, including microwave-based systems for area denial. The Bundeswehr partnered with Rheinmetall to develop portable DEWs for riot control, with successful tests conducted in Berlin. The country's defense sector demonstrates increasing adoption of directed energy technologies, exemplified by deployment of MLG 27 light laser systems and high-energy laser guns on naval vessels operating in international waters. German defense spending exceeds NATO's 2% GDP requirement, enabling substantial investments in advanced weapon systems and research programs. The nation's approach to DEW development emphasizes precision engineering, reliability, and integration with existing military platforms, reflecting Germany's reputation for technological excellence. Additionally, Germany’s focus is on compliance with EU humanitarian standards, positioning DEWs as tools for law enforcement and peacekeeping rather than battlefield use. Germany Focuses on Non-Lethal Dews for Crowd Control and Border Security
Competitive landscape
The industry is substantially consolidated, with a combination of reinstated defense stalwarts, focused laser and microwave solution manufacturers, and evolving innovators competing for defense contracts. Leading players include Lockheed Martin Corporation, Northrop Grumman Corporation, Raytheon Technologies (RTX), BAE Systems, and Rheinmetall AG, all of which have active high-energy laser and high-power microwave programs. The competitive edge lies in power output, beam control, and platform adaptability, with firms racing to meet military requirements for mobile, scalable, and cost-efficient DEW systems.
- November 2024
Raytheon, an RTX business, has been awarded a contract by the United States Army to develop directed energy wireless power beaming technology for battlefield operations. The project, which is in line with the Department of Defense's Operational Energy Strategy, aims to improve troop safety by streamlining logistics and distributing power over long distances. Raytheon's Advanced Technology team will create transmitter and receiver systems for a long-range demonstration of powering both manned and unmanned Army systems.
- November 2024
Thales Australia and the University of Adelaide have announced a collaboration to create a novel laser directed energy weapon (LDEW) designed to counter drone swarms on the battlefield. Unlike traditional long-range continuous wave systems, the new ultra-short pulse laser (USPL) is designed to be more effective at long distances, capable of penetrating fog or clouds, and with lower weight, space, and power requirements.
- Diehl Defense GmbH & Co. KG
- Elbit Systems Ltd.
- Honeywell International Inc.
- II-VI Inc.
- BAE Systems Plc
- Kord Technologies
- L3Harris Technologies Inc.
- Leonardo S.p.A
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- Rafael Advanced Defense Systems Ltd.
- Raytheon Technologies Corporation
- Rheinmetall AG
- Thales Group
- Boeing Company
Frequently asked questions
The Directed Energy Weapons Market size is estimated to be USD 10.3 billion in 2025 and grow at a CAGR of 15.2% to reach USD 42.2 billion by 2035.
Cite this report
Meticulous Research. (2025). Directed Energy Weapons Market - Global Opportunity Analysis And Industry Forecast (2025-2035) (Report No. MRAD - 1041593). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/directed-energy-weapons-market-6276