Data Center Substation Market (2026-2036)
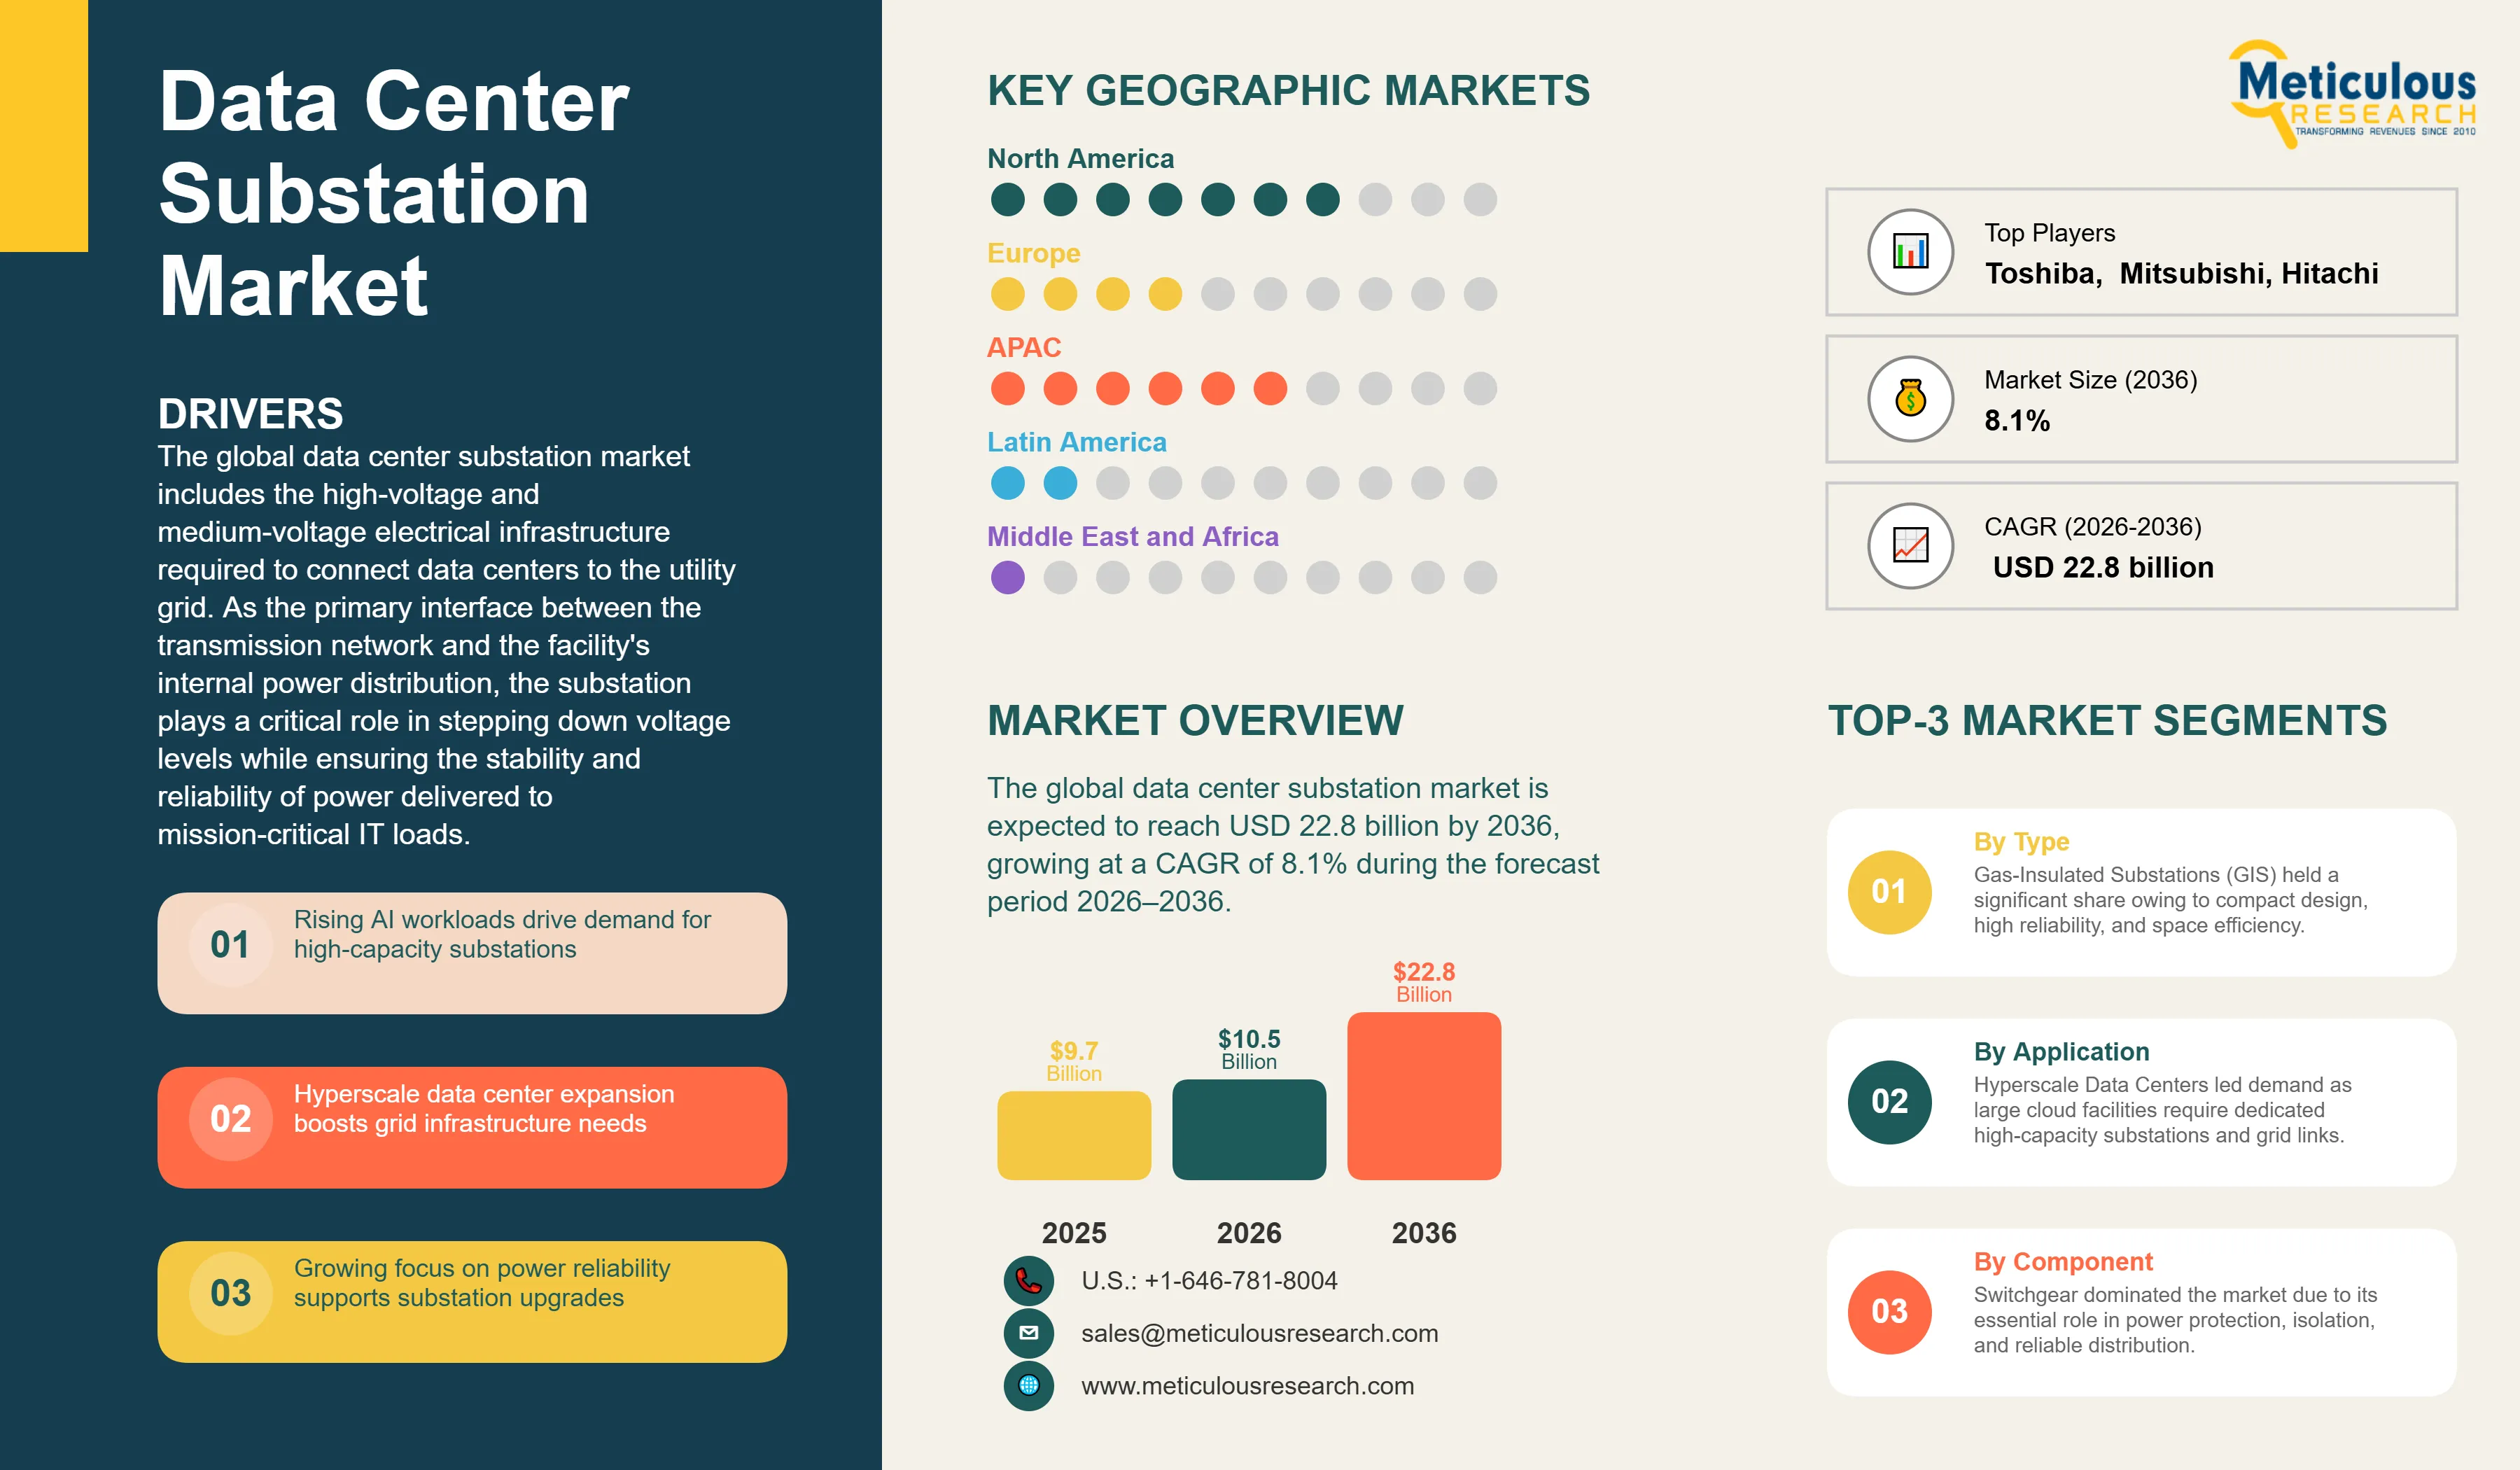
The global data center substation market was valued at USD 10.5 billion in 2026. This market is expected to reach USD 22.8 billion by 2036, growing at a CAGR of 8.1% during the forecast period 2026–2036.
- Published
- Jun 2026
- Pages
- 256
- Format
- PDF + Excel
- Report ID
- MRSE - 1042005
- Base year
- 2025
- 2026 · ESTIMATED
- $10.50B
- 2036
- $22.80B
- CAGR 2026–2036
- 8.1%
2025 baseline · 2026–2036 forecast at 8.1% CAGR · hover a bar for the value
Key highlights
The global data center substation market is projected to reach USD 22.8 billion by 2036.
The market is expected to grow at a CAGR of 8.1% during the forecast period 2026–2036.
The global data center substation market is estimated at USD 10.5 billion in 2026.
North America is expected to dominate the global data center substation market with the largest share in 2026, driven by the presence of major hyperscale cloud providers, mature utility frameworks, and significant investments in AI-ready infrastructure.
Asia-Pacific is projected to witness the fastest growth during the forecast period, fueled by rapid digitalization, expanding internet penetration, and the emergence of regional data center hubs in China, India, and Southeast Asia.
By component, the switchgear segment is expected to hold the largest share in 2026, driven by the critical requirement for circuit protection, isolation, and power distribution in high-voltage environments.
By construction, the modular/prefabricated substation segment is projected to register the highest CAGR during the forecast period, as operators prioritize speed-to-market and standardized deployment models to align with rapid IT capacity expansion.
By type, the gas-insulated substation (GIS) segment is expected to account for a significant share in 2026, mainly in urban environments where space constraints necessitate compact electrical infrastructure.
By application, the hyperscale data center segment is expected to account for the largest share in 2026, reflecting the massive power loads and dedicated grid connection requirements of large-scale cloud facilities.
The increasing adoption of SF6-free switchgear and biodegradable insulating fluids is expected to redefine the technological landscape over the forecast period, driven by stringent environmental regulations and corporate ESG goals.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 10.50 billion |
| Market Size (2036) | USD 22.80 billion |
| CAGR (2026–2036) | 8.1% |
| Format | PDF, Excel & Cloud Portal · 256 pages |
| Segments Covered | By Component · By Type: AIS, GIS, Hybrid · By Voltage Level · By Deployment · By Data Center Type: Hyperscale, Colocation, Enterprise, Edge |
Report overview
Segments covered: component, type, voltage level, deployment, data center type.
The global data center substation market includes the high-voltage and medium-voltage electrical infrastructure required to connect data centers to the utility grid. As the primary interface between the transmission network and the facility's internal power distribution, the substation plays a critical role in stepping down voltage levels while ensuring the stability and reliability of power delivered to mission-critical IT loads. The market covers a broad range of components, including power transformers, switchgear, circuit breakers, and advanced automation systems.
According to the International Energy Agency (IEA), global electricity demand from data centers reached approximately 415 TWh in 2024, accounting for nearly 1.5% of global demand, and is projected to approach 945 TWh by 2030 as computational requirements for artificial intelligence and cloud services expand.
The growth of the overall data center substation market is primarily driven by the proliferation of hyperscale data centers, the increasing power density requirements of AI-driven workloads, and the global push for modernized grid infrastructure. As data centers transition from megawatt-scale to gigawatt-scale campuses, the complexity of grid interconnection has escalated, positioning the substation as a strategic asset in the development lifecycle. The U.S. Department of Energy (DOE) reports that data center load growth has tripled over the past decade and is projected to double or triple by 2028, necessitating significant investment in dedicated substation facilities. Furthermore, the rising adoption of Tier III and Tier IV data center standards, which require high levels of redundancy and fault tolerance, is driving the demand for sophisticated substation architectures featuring multiple utility feeds and automated failover systems.
However, the growth of this market is restrained by the high initial capital expenditure and the significant lead times associated with critical electrical components. Procurement cycles for large power transformers have extended to over 100 weeks in certain regions due to shortages in raw materials such as grain-oriented electrical steel and copper. Additionally, the complex regulatory and permitting processes involved in substation siting and grid interconnection can lead to project delays of several years. Maintaining operational safety and cybersecurity in an increasingly digitized environment also presents a persistent challenge for market participants, requiring ongoing investment in advanced protection relays and secure communication protocols.
On the other hand, emerging opportunities in digital substations, grid-interactive data centers, and sustainable insulating technologies are creating new growth avenues. The implementation of the IEC 61850 standard for communication enables real-time monitoring and predictive maintenance, while the integration of renewable energy sources and battery storage systems aligns with the industry's move toward carbon neutrality. The development of SF6-free switchgear and the use of biodegradable ester oils in transformers are expected to attract continued investment, especially in regions with stringent environmental regulations such as Europe.
Report infographic
Market dynamics
7 factors across 5 forcesThe key driver for the global
data center substation market is the growing demand for power infrastructure to support AI and hyperscale computing. Training large language models (LLMs) and running generative AI applications require rack power densities that can exceed 50-100kW, necessitating high-capacity grid connections. The expansion of hyperscale facilities by major cloud providers is a significant factor; for instance, the industry added 137 new hyperscale facilities in 2024 alone. These facilities often require dedicated 110kV or 220kV substations to interface directly with high-voltage transmission lines, ensuring the necessary load capacity is available for rapid scaling.
Another key driver is the increasing
focus on power reliability and grid resilience. Data center operators are investing in advanced substation designs to minimize the risk of utility-side outages. This includes the deployment of redundant transformers and gas-insulated switchgear (GIS) that offer higher reliability and lower maintenance requirements compared to traditional air-insulated options. The modernization of aging electrical grids in developed markets also provides a tailwind, as utilities and data center operators collaborate to build more robust interconnection points that can handle the bi-directional power flows associated with on-site renewable energy integration.
Table of contents
13 chapters · 96 sections · 256 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Component | Switchgear | Power automation & control systems |
| By Construction | Conventional | Modular/prefabricated |
By Component
- The Switchgear Segment to Dominate the Global Market
- The switchgear segment is expected to account for the largest share of the market.
- The large share of this segment is primarily attributed to the critical role of switchgear in controlling, protecting, and isolating electrical equipment.
- High-voltage and medium-voltage switchgear are essential for managing the massive power loads of modern data centers, and the shift toward gas-insulated switchgear (GIS) for its reliability and compact footprint further supports this segment's dominance.
- However, the power automation & control systems segment is projected to grow at the highest CAGR during the forecast period.
- The rapid growth of this segment is driven by the increasing digitalization of substations and the need for advanced monitoring and control capabilities.
- The integration of SCADA systems, intelligent relays, and IEC 61850-compliant communication networks is becoming a standard requirement for high-availability data centers.
By Construction
- The Conventional Segment to Hold the Largest Share
- The conventional segment is expected to hold the largest share, as many large-scale substation projects still rely on traditional civil engineering and on-site assembly for high-voltage transmission-level substations.
- However, the modular/prefabricated segment is projected to register the highest CAGR.
- This growth is fueled by the 'speed-to-market' demands of hyperscale operators and the benefits of reduced on-site labor and improved quality control offered by factory-integrated solutions.
Geographic analysis
North America
Largest shareNorth America is expected to dominate the global data center substation market in 2026, driven by the strong presence of hyperscale providers and the concentration of data center hubs in regions like Northern Virginia, which has the highest density of data centers globally. The mature utility infrastructure and significant investments in grid modernization support the demand for high-capacity substation equipment. The U.S. alone has over 4,000 data centers, and the ongoing expansion of AI-ready facilities is a major growth driver. The key companies operating in the North American market are ABB Ltd., Schneider Electric SE, Siemens Energy AG, Eaton Corporation plc, and GE Vernova.
Asia-Pacific
Fastest growthAsia-Pacific data center substation market is projected to witness the fastest growth during the forecast period. This growth is driven by rapid digitalization, increasing internet penetration, and the expansion of cloud services in China, India, and Southeast Asia. China's state-led infrastructure projects and India's growing status as a global data center hub are significant factors. The emerging markets in the region are investing heavily in new power infrastructure to support the world's fastest-growing internet user base. The key companies operating in the Asia-Pacific market are Hitachi Energy Ltd., Mitsubishi Electric Corporation, Toshiba Energy Systems & Solutions Corporation, LS ELECTRIC Co., Ltd., and TBEA Co., Ltd.
Frequently asked questions
The global data center substation market is projected to reach USD 22.8 billion by 2036, growing at a CAGR of 8.1% from 2026 to 2036.
Cite this report
Meticulous Research. (2026). Data Center Substation Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRSE - 1042005). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/data-center-substation-market-6688