Computational Pathology Market (2026-2036)
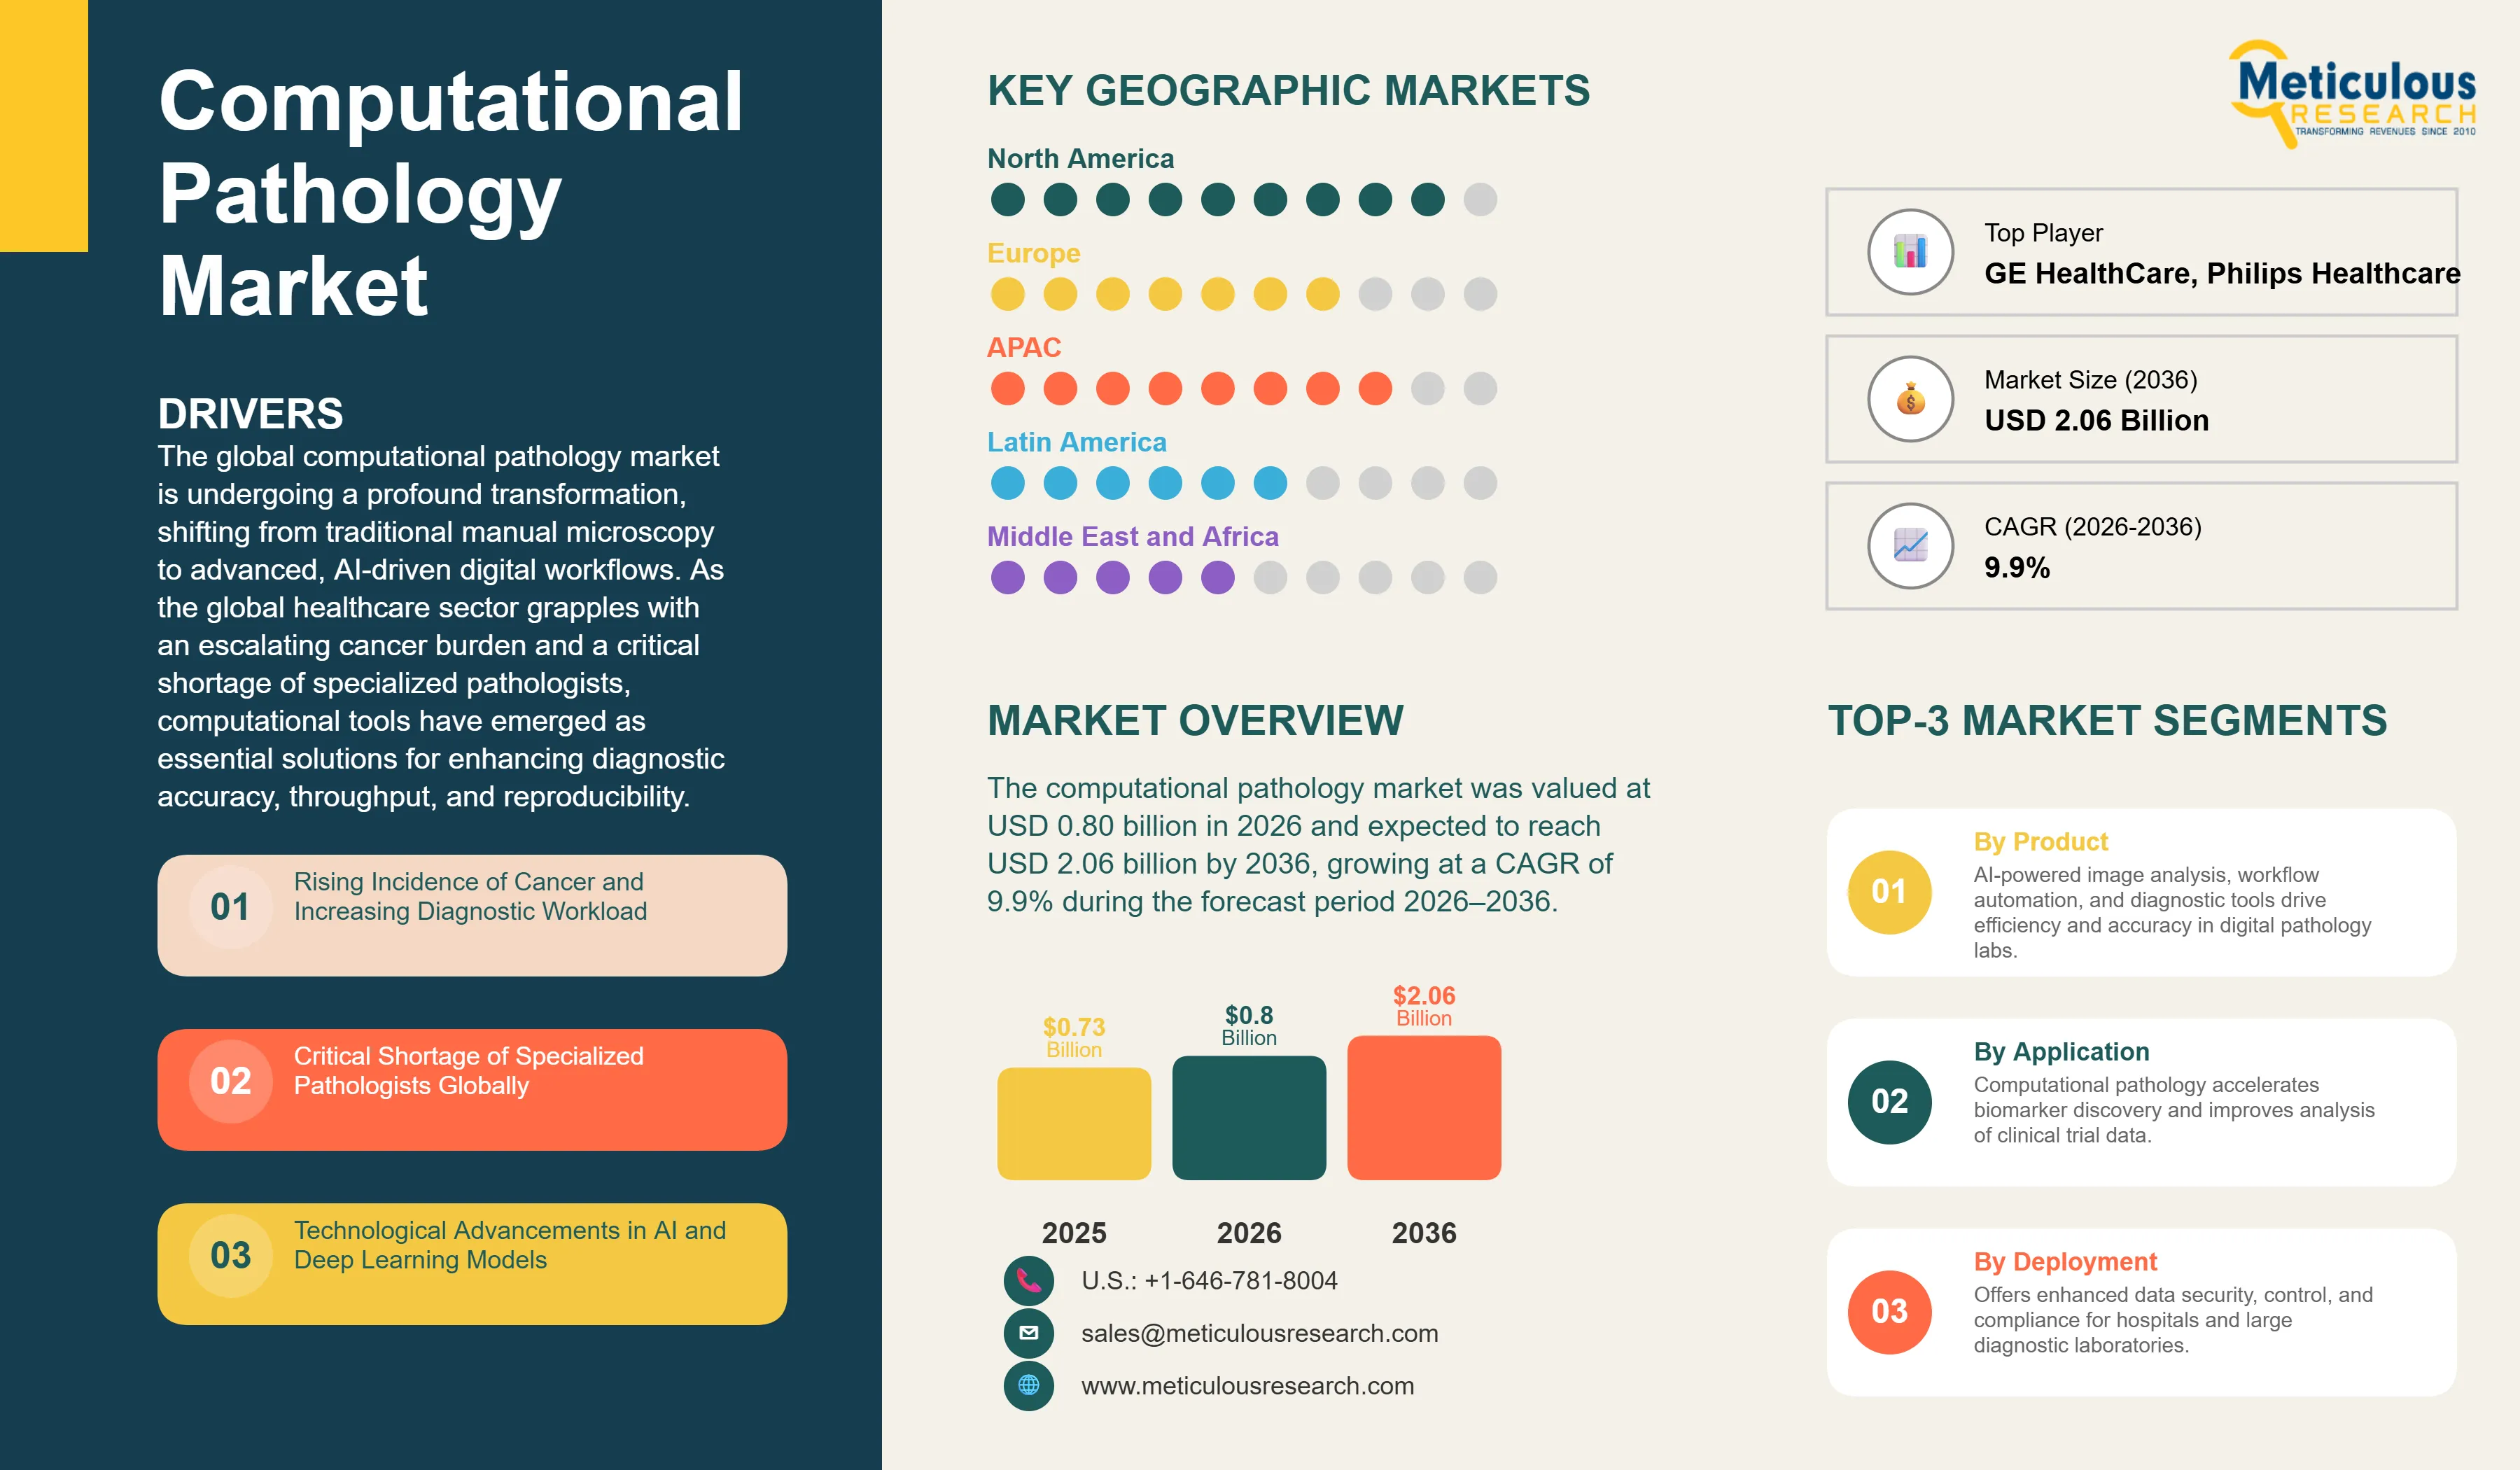
The global computational pathology market was valued at USD 0.80 billion in 2026. This market is expected to reach USD 2.06 billion by 2036, growing at a CAGR of 9.9% during the forecast period 2026–2036.
- Published
- Jun 2026
- Pages
- 275
- Format
- PDF + Excel
- Report ID
- MRHC - 1042022
- Base year
- 2025
- 2026 · ESTIMATED
- $800.0M
- 2036
- $2.06B
- CAGR 2026–2036
- 9.9%
2025 baseline · 2026–2036 forecast at 9.9% CAGR · hover a bar for the value
Key highlights
The global computational pathology market is projected to reach USD 2.06 billion by 2036.
The market is expected to grow at a CAGR of 9.9% during the forecast period 2026–2036.
The global market is estimated at USD 0.80 billion in 2026.
AI-based image analysis software is the fastest-growing product segment.
Computational tools can reduce slide review time by up to 30% in clinical workflows.
On-premise deployment accounts for approximately 56.4% of the market in 2026.
The U.S. is projected to face a shortage of 5, 700 pathologists by 2030, driving tool adoption.
North America holds the largest market share, estimated at approximately 40-50% in 2026.
Integration with multi-omics data is a major emerging trend for precision medicine.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 800.0 million |
| Market Size (2036) | USD 2.06 billion |
| CAGR (2026–2036) | 9.9% |
| Format | PDF, Excel & Cloud Portal · 275 pages |
| Segments Covered | By Product & Service: Software, Services · By Deployment Mode · By Application · By End User: Hospitals, Pharmaceutical Companies |
| Key Companies | Danaher Corporation, HealthCare, Philips Healthcare, Nikon Corporation, Olympus Corporation, K., Proscia Inc. |
Report overview
Segments covered: product & service, deployment mode, application, end user.
The global computational pathology market is undergoing a profound transformation, shifting from traditional manual microscopy to advanced, AI-driven digital workflows. As the global healthcare sector grapples with an escalating cancer burden and a critical shortage of specialized pathologists, computational tools have emerged as essential solutions for enhancing diagnostic accuracy, throughput, and reproducibility. These systems utilize sophisticated image analysis algorithms to interpret whole-slide images (WSI), enabling the identification of subtle morphological features that may be missed by the human eye. The market's growth is fundamentally anchored by the rising incidence of chronic diseases, particularly cancer, cardiovascular disorders, and neurological conditions. According to the International Agency for Research on Cancer, approximately 20 million new cancer cases and 9.7 million cancer-related deaths were reported globally in 2022, while the global cancer burden is projected to increase by 77% by 2050, reaching more than 35 million new cases annually. This growing disease burden is accelerating the adoption of AI-enabled medical devices for early detection, diagnosis, treatment planning, and patient monitoring.
Technological advancements in artificial intelligence (AI) and machine learning (ML) are the primary catalysts for market expansion. Modern computational pathology platforms now incorporate deep learning models capable of performing complex tasks such as tissue segmentation, cell counting, and biomarker quantification with unprecedented precision. These tools can reduce slide review time by up to 30%, allowing pathologists to focus on more complex cases while maintaining a high standard of care. Furthermore, the integration of computational pathology with other multi-omics data—including genomics and proteomics—is paving the way for holistic precision medicine, where diagnostic insights are personalized to the individual patient's biological profile.
The market is also benefiting from the widespread adoption of digital scanners, which create the foundational digital data needed for computational analysis. While on-premise deployment remains the dominant choice for large academic medical centers due to data control and security requirements, cloud-based SaaS models are witnessing the fastest growth. These cloud solutions offer the scalability and interoperability needed for multidisciplinary care settings and reduce the significant capital investment required for high-performance computing infrastructure. The competitive landscape is characterized by a mix of established medical device giants and agile AI startups, all vying to secure regulatory approvals and prove the clinical validity of their diagnostic algorithms.
Geographically, North America leads the global market. This dominance is driven by robust NIH funding, a high concentration of leading pharmaceutical companies, and a proactive regulatory environment for digital health tools. However, the Asia-Pacific region is projected to witness the fastest growth through 2036. Countries like China and India are rapidly modernizing their diagnostic infrastructure and adopting AI-driven solutions to manage their massive patient populations. As computational pathology becomes the standard of care, the market is poised for sustained growth, reaching over USD 2 billion by the end of the forecast period.
Report infographic
Market dynamics
7 factors across 5 forcesThe primary driver for the computational
pathology market is the rising global incidence of cancer, which is creating significant demand for faster, more accurate, and scalable diagnostic solutions. According to the International Agency for Research on Cancer, approximately 20 million new cancer cases and 9.7 million cancer-related deaths were reported globally in 2022, and the global cancer burden is projected to increase by 77% by 2050, reaching more than 35 million new cases annually. This growing disease burden is increasing pathology testing volumes and accelerating the need for AI-enabled diagnostic technologies.
Furthermore, the shortage of trained pathology
professionals remains a major challenge for healthcare systems worldwide. According to the World Health Organization, the world is projected to face a shortage of approximately 10 million health workers by 2030, including laboratory and diagnostic specialists. Computational pathology solutions help laboratories manage increasing workloads through automation, image analysis, and decision support. Technological advances in artificial intelligence and deep learning have further improved the ability of algorithms to identify complex tissue patterns with high consistency and reproducibility. In addition, the growing adoption of digital pathology is expanding the foundation for computational analysis, with the U.S. Food and Drug Administration having authorized multiple whole-slide imaging systems for primary diagnostic use, supporting broader implementation across pathology laboratories.
Table of contents
12 chapters · 104 sections · 275 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product | Software | AI-based Image Analysis Software |
| By Application | Drug Discovery & Development | Clinical Diagnostics |
By Product
- Software to Hold Largest Share
- The Software segment is expected to hold the largest share of the market.
- This segment includes whole-slide imaging software, AI-based image analysis tools, and case management systems.
- The dominance is driven by the critical role of these tools in enabling digital workflows and automated diagnostics.
- The AI-based Image Analysis Software sub-segment is projected to witness the fastest growth, as laboratories increasingly seek to automate complex diagnostic tasks and improve the reproducibility of tissue-based assessments.
By Application
- Drug Discovery & Development to Lead
- The Drug Discovery & Development segment is expected to hold the largest share of the market.
- Pharmaceutical companies were the earliest adopters of computational pathology for biomarker discovery and quantifying treatment effects in clinical trials.
- The Clinical Diagnostics segment is projected to witness the fastest growth during the forecast period, as regulatory approvals expand the use of computational tools for routine cancer diagnosis in hospital settings.
Geographic analysis
North America
Largest shareNorth America is expected to hold the largest share of the global computational pathology market in 2026, accounting for approximately 45% of total revenue. This dominance is due to robust NIH funding for cancer research, a high concentration of leading pharmaceutical companies, and the early adoption of digital health technologies. The presence of major industry players like Danaher (Leica) and Roche also strengthens the regional market.
Asia-Pacific
Fastest growthAsia-Pacific is projected to witness the fastest growth during the forecast period. The region is modernizing its diagnostic infrastructure at an unprecedented pace, with countries like China and India investing heavily in AI-driven healthcare solutions. The rising incidence of cancer and the need for efficient data management in large-scale clinical settings are the primary growth drivers. Key companies operating in the Asia-Pacific market include major global vendors and emerging local tech firms.
Competitive landscape
- Danaher Corporation
- HealthCare, Philips Healthcare, Nikon Corporation
- Olympus Corporation
- K., Proscia Inc.
Frequently asked questions
The market is projected to reach USD 2.06 billion by 2036, growing at a CAGR of 9.9% from 2026 to 2036.
Cite this report
Meticulous Research. (2026). Computational Pathology Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1042022). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/computational-pathology-market-6705