Chronic Total Occlusion (CTO) Devices Market (2026-2036)
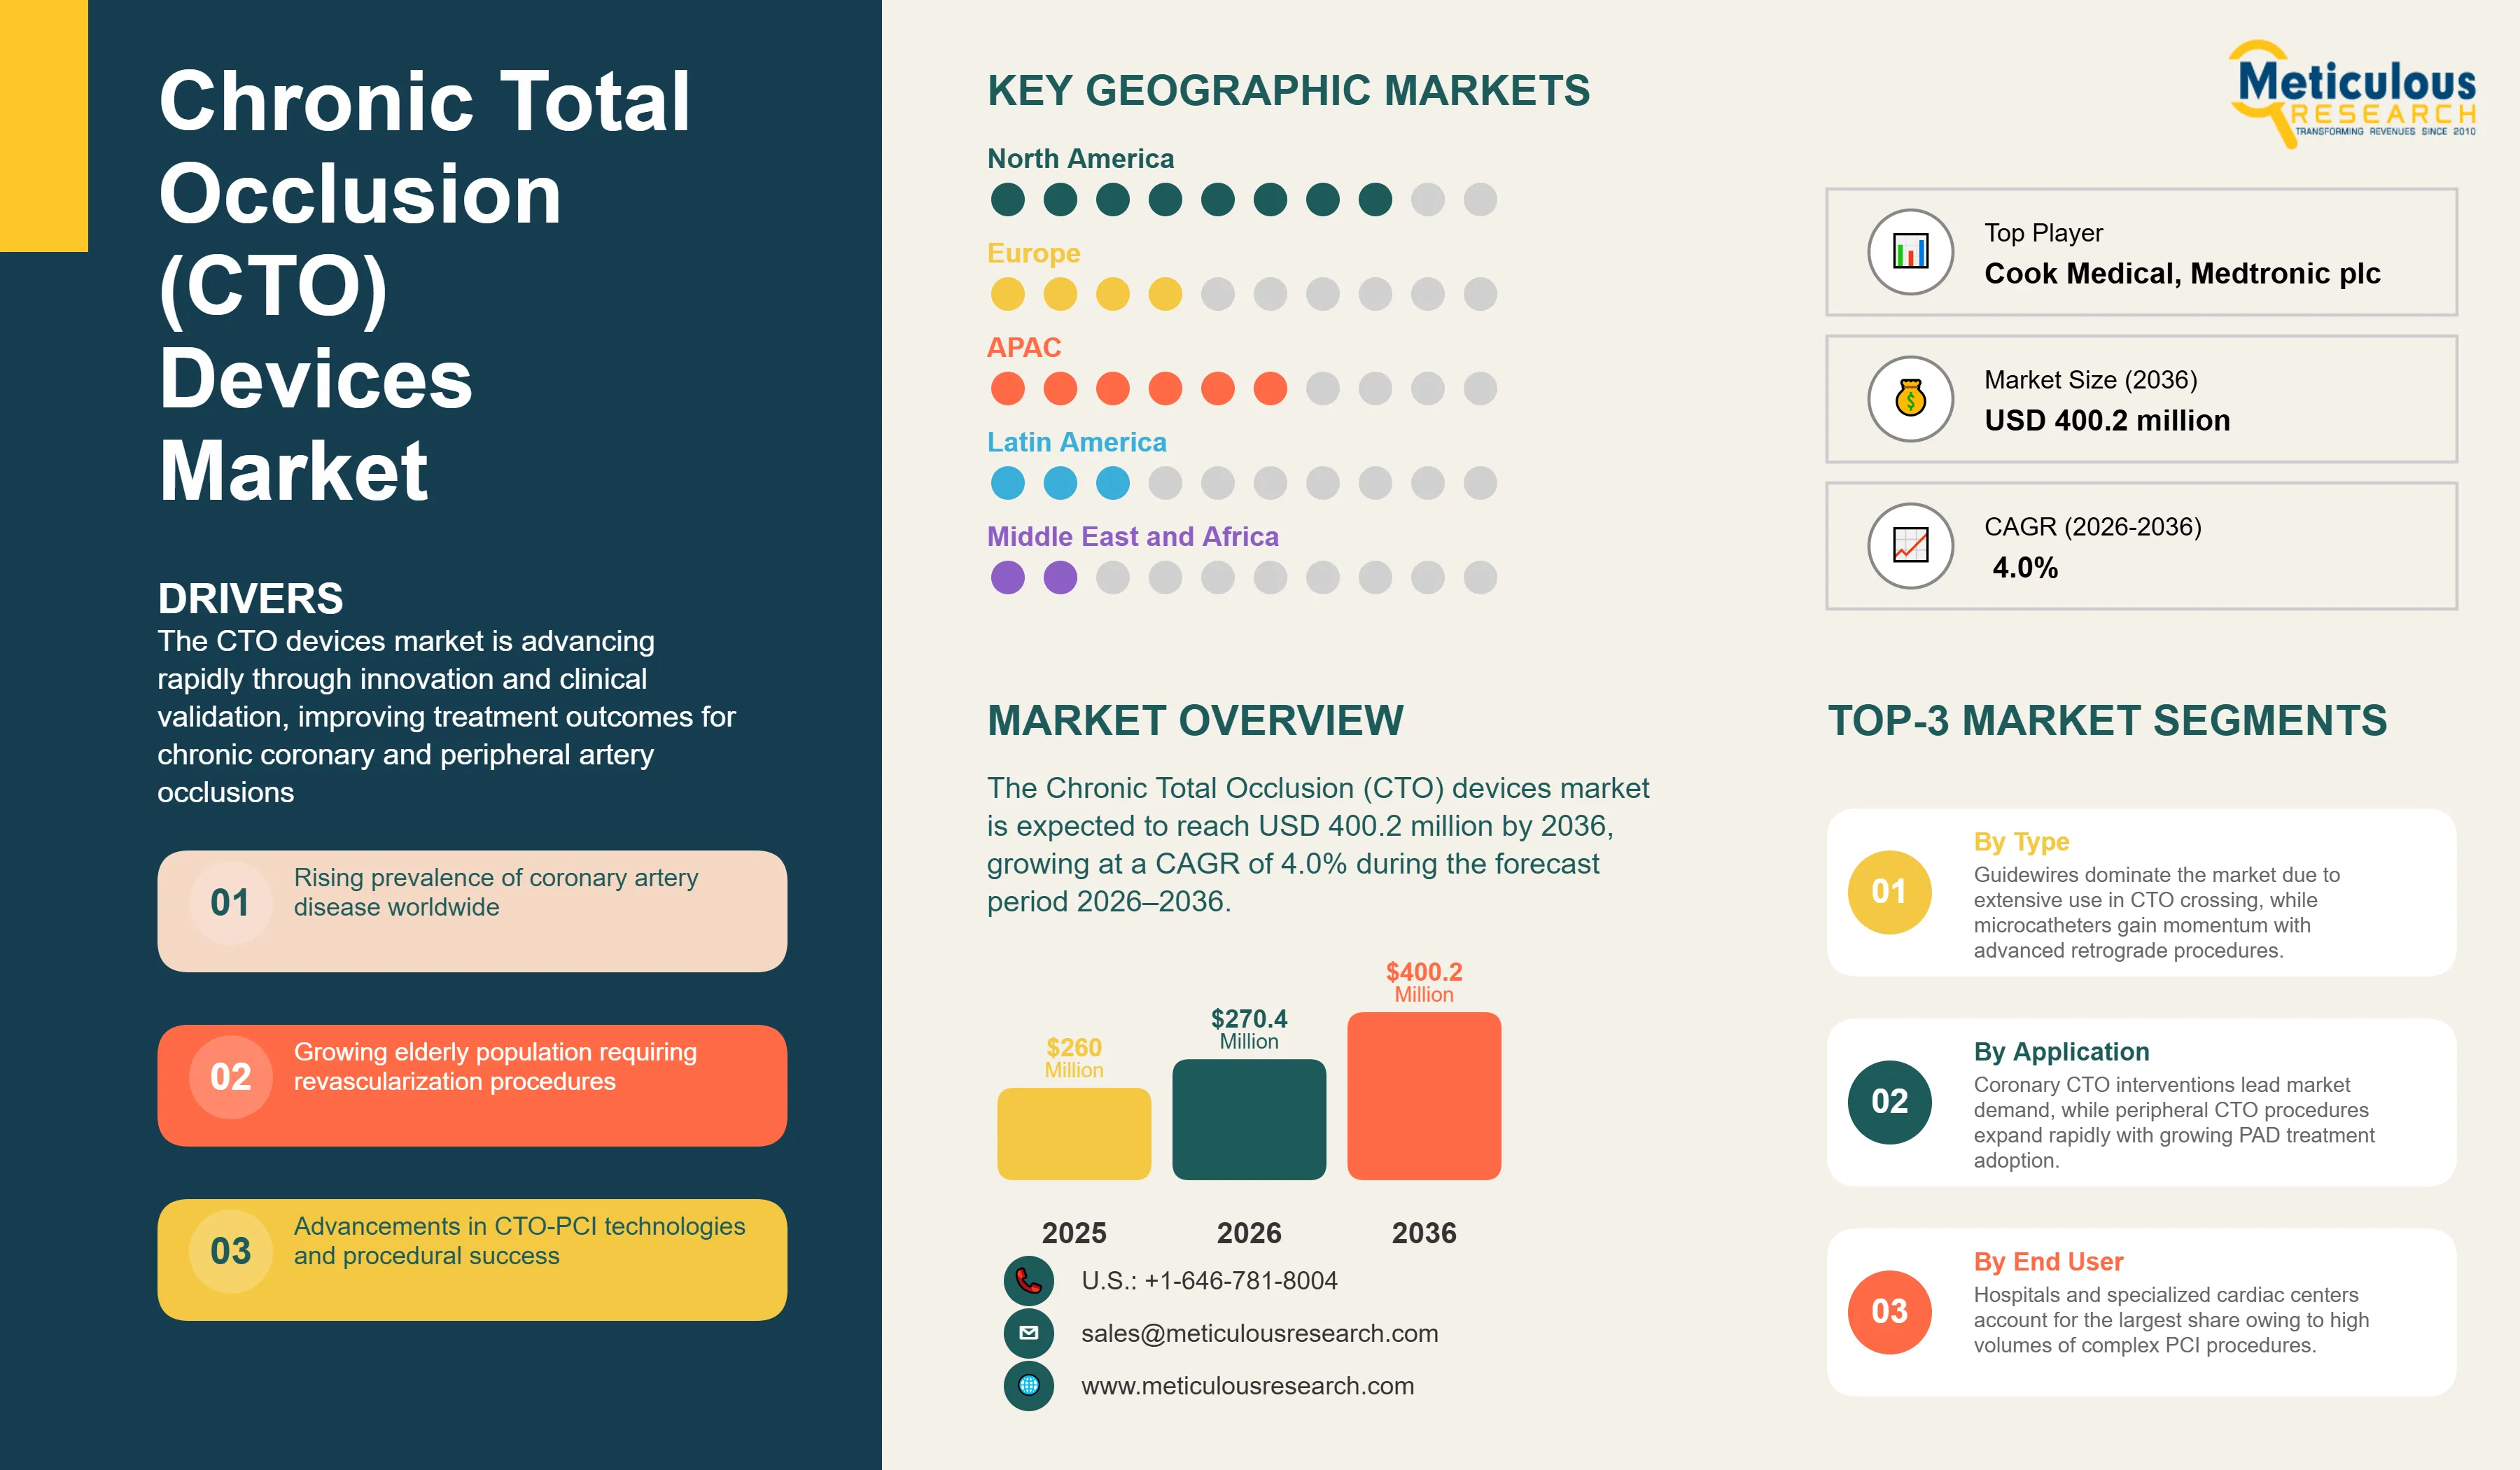
The global Chronic Total Occlusion (CTO) devices market was valued at USD 270.4 million in 2026. This market is expected to reach USD 400.2 million by 2036, growing at a CAGR of 4.0% during the forecast period 2026–2036.
- Published
- Jun 2026
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRHC - 1042011
- Base year
- 2025
- 2026 · ESTIMATED
- $270.4M
- 2036
- $400.2M
- CAGR 2026–2036
- 4.0%
2025 baseline · 2026–2036 forecast at 4.0% CAGR · hover a bar for the value
Key highlights
The global chronic total occlusion (CTO) devices market is projected to reach USD 400.2 million by 2036.
The market is expected to grow at a CAGR of 4.0% during the forecast period 2026–2036.
The global market is estimated at USD 270.4 million in 2026.
CTOs are present in approximately 15-30% of patients undergoing diagnostic coronary angiography.
Success rates for CTO-PCI have improved to over 90% in high-volume specialized centers.
The Guidewires segment currently holds the largest share of the market due to their fundamental role in all crossing strategies.
The Microcatheters segment is projected to witness the fastest growth, driven by the increasing adoption of retrograde techniques.
North America accounts for approximately 40% of the global market share in 2026.
Asia-Pacific is expected to be the fastest-growing region, with Japan being a pioneer in CTO device innovation.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 270.4 million |
| Market Size (2036) | USD 400.2 million |
| CAGR (2026–2036) | 4.0% |
| Format | PDF, Excel & Cloud Portal · 250 pages |
| Segments Covered | By Product Type: Guidewires, Microcatheters, Crossing Devices, Balloons · By Technology: Antegrade, Retrograde · By Application End User |
| Key Companies | Terumo Corporation, Abbott Laboratories, Boston Scientific Corporation, Medtronic plc, Asahi Intecc Co., Ltd., Merit Medical Systems, Inc. |
Report overview
Segments covered: product type, technology, application end user.
The global chronic total occlusion (CTO) devices market is experiencing a period of rapid technological advancement and clinical validation, transforming the treatment landscape for complex coronary and peripheral arterial diseases. A CTO is defined as a complete arterial occlusion with TIMI 0 flow that has persisted for at least three months. CTO lesions are identified in approximately 15–25% of patients undergoing coronary angiography and are present in nearly one-third of patients with significant coronary artery disease (CAD). Historically, CTOs were regarded as one of the most challenging lesion subsets in interventional cardiology, frequently leading to referral for coronary artery bypass grafting (CABG) or conservative medical therapy. However, the introduction of dedicated CTO guidewires, microcatheters, re-entry devices, and hybrid crossing algorithms has significantly improved the feasibility and success of percutaneous coronary intervention (PCI) in these complex cases.
The market's growth is fundamentally driven by the rising prevalence of coronary artery disease and the expanding global elderly population. According to estimates from the Global Burden of Disease (GBD) study, ischemic heart disease affects more than 240 million people worldwide and remains the leading cause of death globally, accounting for nearly 9 million deaths annually. Furthermore, the prevalence of CAD increases substantially with age, creating a growing pool of patients requiring revascularization procedures. CTO lesions are estimated to occur in approximately 18–30% of patients with angiographically confirmed CAD, underscoring the significant clinical burden associated with these complex occlusions. In experienced CTO centers, procedural success rates have improved from approximately 60–70% in the early 2000s to more than 85–90% today, largely due to advancements in guidewire technology, microcatheters, intravascular imaging, and operator training. Clinical evidence from large registries such as J-CTO and PROGRESS-CTO has demonstrated that successful CTO revascularization is associated with significant improvements in angina relief, exercise tolerance, and quality of life.
The technological ecosystem of the CTO devices market is highly specialized, with continuous innovation focused on miniaturization, steerability, torque response, and material science. Guidewires remain the largest product segment, serving as the foundation of both antegrade and retrograde crossing strategies. The growing adoption of complex CTO techniques has also accelerated demand for microcatheters, which provide enhanced support, wire exchange capability, and navigation through tortuous collateral channels. Dedicated re-entry systems and dissection-re-entry devices are gaining traction as operators increasingly adopt advanced crossing strategies for heavily calcified and long-segment occlusions. CTO interventions are among the most device-intensive procedures performed in catheterization laboratories and frequently require multiple guidewires, microcatheters, balloons, and imaging tools, resulting in substantially higher disposable device utilization compared with conventional PCI procedures.
Geographically, North America and Europe continue to account for a significant share of the CTO devices market due to their advanced cardiovascular care infrastructure, high procedural volumes, and strong adoption of complex PCI techniques. The United States performs more than one million PCI procedures annually and remains the largest market for CTO interventions, supported by favorable reimbursement frameworks and widespread availability of specialized catheterization laboratories. However, the Asia-Pacific region is expected to witness the fastest growth during the forecast period. Japan has played a pioneering role in the development of contemporary CTO techniques and contributes significantly to global guidewire innovation and operator training. Meanwhile, China is experiencing rapid expansion in interventional cardiology services, supported by increasing healthcare expenditure, growing cardiovascular disease burden, and the establishment of dedicated CTO training programs and centers of excellence. As healthcare systems increasingly prioritize minimally invasive treatment approaches, the demand for specialized CTO devices is expected to remain strong throughout the forecast period.
Report infographic
Market dynamics
6 factors across 5 forcesThe primary driver for the CTO
devices market is the increasing prevalence of complex coronary and peripheral artery diseases. According to the Global Burden of Disease (GBD) study, ischemic heart disease affects more than 240 million people worldwide and remains the leading cause of mortality globally. The growing burden of diabetes and hypertension, affecting approximately 830 million and 1.3 billion people worldwide, respectively, has contributed to a rise in multi-vessel coronary disease and heavily calcified lesions. CTOs are identified in approximately 15–25% of patients undergoing coronary angiography. Furthermore, technological advancements have increased CTO-PCI success rates from around 60–70% in the early 2000s to over 85–90% in experienced centers, accelerating the adoption of minimally invasive revascularization as an alternative to CABG for selected patient populations.
Table of contents
12 chapters · 114 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Guidewires | Microcatheters |
| By Application | Coronary Interventions | Peripheral CTO Interventions |
By Product Type
- Guidewires to Hold Largest Share
- The Guidewires segment is expected to hold the largest share of the market.
- Guidewires are the fundamental tool for every CTO crossing strategy, and a single procedure often requires multiple wires as the interventionalist escalates from soft, hydrophilic wires to stiffer, tapered-tip wires.
- The high volume of wire consumption per procedure ensures this segment remains the primary revenue driver.
- The Microcatheters segment is projected to register the fastest CAGR during the forecast period.
- This growth is driven by the increasing complexity of crossing strategies, particularly the retrograde approach, which requires high-support microcatheters for collateral channel crossing and wire exchange.
- The development of dual-lumen microcatheters for side-branch protection and parallel wiring is also fueling demand in this segment.
By Application
- Coronary Interventions to Lead
- The Coronary Interventions segment is expected to hold the largest share of the market.
- Coronary revascularization is a high clinical priority due to the life-threatening nature of CAD.
- The established network of cardiac catheterization labs and the high volume of coronary procedures globally ensure that this application remains the dominant market segment.
- The Peripheral CTO Interventions segment is projected to witness the fastest growth during the forecast period.
- Interventionalists are increasingly applying the advanced techniques developed for coronary CTOs to treat complex peripheral arterial disease (PAD).
- The rising focus on limb salvage and the treatment of chronic limb-threatening ischemia (CLTI) are driving the demand for specialized peripheral CTO tools.
Geographic analysis
North America
Largest shareNorth America is expected to hold the largest share of the global CTO devices market in 2026, driven by the high adoption of advanced interventional technologies and a well-established healthcare infrastructure in the United States. The large share of regions is further supported by a high volume of complex cardiac procedures and favorable reimbursement for specialized medical devices. The key companies operating in the North American market are Abbott Laboratories, Boston Scientific, and Medtronic.
Asia-Pacific
Fastest growthAsia-Pacific is projected to witness the fastest growth during the forecast period. Japan is a global pioneer in CTO device innovation and technique development, while China and India are experiencing a rapid increase in procedural volumes and the establishment of specialized heart centers. The growing clinical expertise and rising healthcare spending in these markets present significant opportunities for manufacturers. The key companies operating in the Asia-Pacific market are Asahi Intecc, Terumo Corporation, and various emerging domestic players in China.
Competitive landscape
- Terumo Corporation
- Abbott Laboratories, Boston Scientific Corporation
- Medtronic plc
- Asahi Intecc Co., Ltd.
- Merit Medical Systems, Inc.
Frequently asked questions
The market is projected to reach USD 400.2 million by 2036, growing at a CAGR of 4.0% from 2026 to 2036.
Cite this report
Meticulous Research. (2026). Chronic Total Occlusion (CTO) Devices Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1042011). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/chronic-total-occlusion-devices-market-6694