Autoinjectors Market (2025-2032)
The Autoinjectors Market was valued at $2.01 billion in 2024. This market is expected to reach $3.76 billion by 2032, from an estimated $2.16 billion in 2025, at a CAGR of 8.3% during the forecast period 2025-2032. Autoinjectors Market Size & Forecast The growth of this market is primarily driven
- Published
- Jan 2024
- Pages
- 230
- Format
- PDF + Excel
- Report ID
- MRHC - 1041216
- Base year
- 2024
- 2024 · BASELINE
- $2.01B
- 2032
- $3.76B
- CAGR 2025–2032
- 8.3%
2024 baseline · 2025–2032 forecast at 8.3% CAGR · hover a bar for the value
Key highlights
By Type: The Disposable Autoinjectors Segment to Dominate the Autoinjectors Market in 2025
By Route of Administration: The Subcutaneous Segment to Dominate the Autoinjectors Market in 2025
By Technology: The Manual Autoinjectors Segment to Dominate the Autoinjectors Market in 2025
By Application: The Diabetes Segment to Dominate the Autoinjectors Market in 2025
By Distribution Channel: The Retail Pharmacies Segment to Dominate the Autoinjectors Market in 2025
By End User: The Home Care Segment to Dominate the Autoinjectors Market in 2025
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 230 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 8.3% |
| Market Size (Value) | $3.76 Billion by 2032 |
| Segments Covered | By Type · Disposable Autoinjectors · Reusable Autoinjectors · Smart Autoinjectors · Bluetooth Connectivity · Near Field Communication (NFC) Connectivity · Wearable Autoinjectors · By Route of Administration · Subcutaneous · Intramuscular · By Technology · Manual Autoinjectors · Automatic Autoinjectors · By Application · Rheumatoid Arthritis · Osteoporosis · Diabetes · Multiple Sclerosis · Other Applications · (Note: Other applications include epilepsy, oncology, anaphylaxis, migraine, and anemia.) · By Distribution Channel · Hospital Pharmacies · Retail Pharmacies · Online/E-commerce Platforms · By End User · Home Care · Hospitals & Clinics · Other End Users · (Note: Other end users include long-term care settings and military & defense.) |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, France, Italy, U.K., Spain, Austria, Netherlands, and Rest of Europe), Asia–Pacific (India, China, Japan, Australia, South Korea, and Rest of Asia–Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa. |
| Key Companies Profiled | Becton, Dickinson and Company (U.S.), Ypsomed AG (Switzerland), SHL Medical (Switzerland), Recipharm AB (Sweden), Owen Mumford Limited (U.K), Halozyme, Inc. (U.S.), AstraZeneca (U.K.), Teva Pharmaceutical Industries Ltd. (Israel), Solteam Incorporation Co., Ltd. (China), Gerresheimer AG (Germany), West Pharmaceutical Services, Inc. (U.S.), Bayer AG (Germany), and Union Medico ApS. (Denmark). |
Report overview
Segments covered: type, technology, application, distribution, route of administration, end user. Regions: North America, Europe, Latin America.
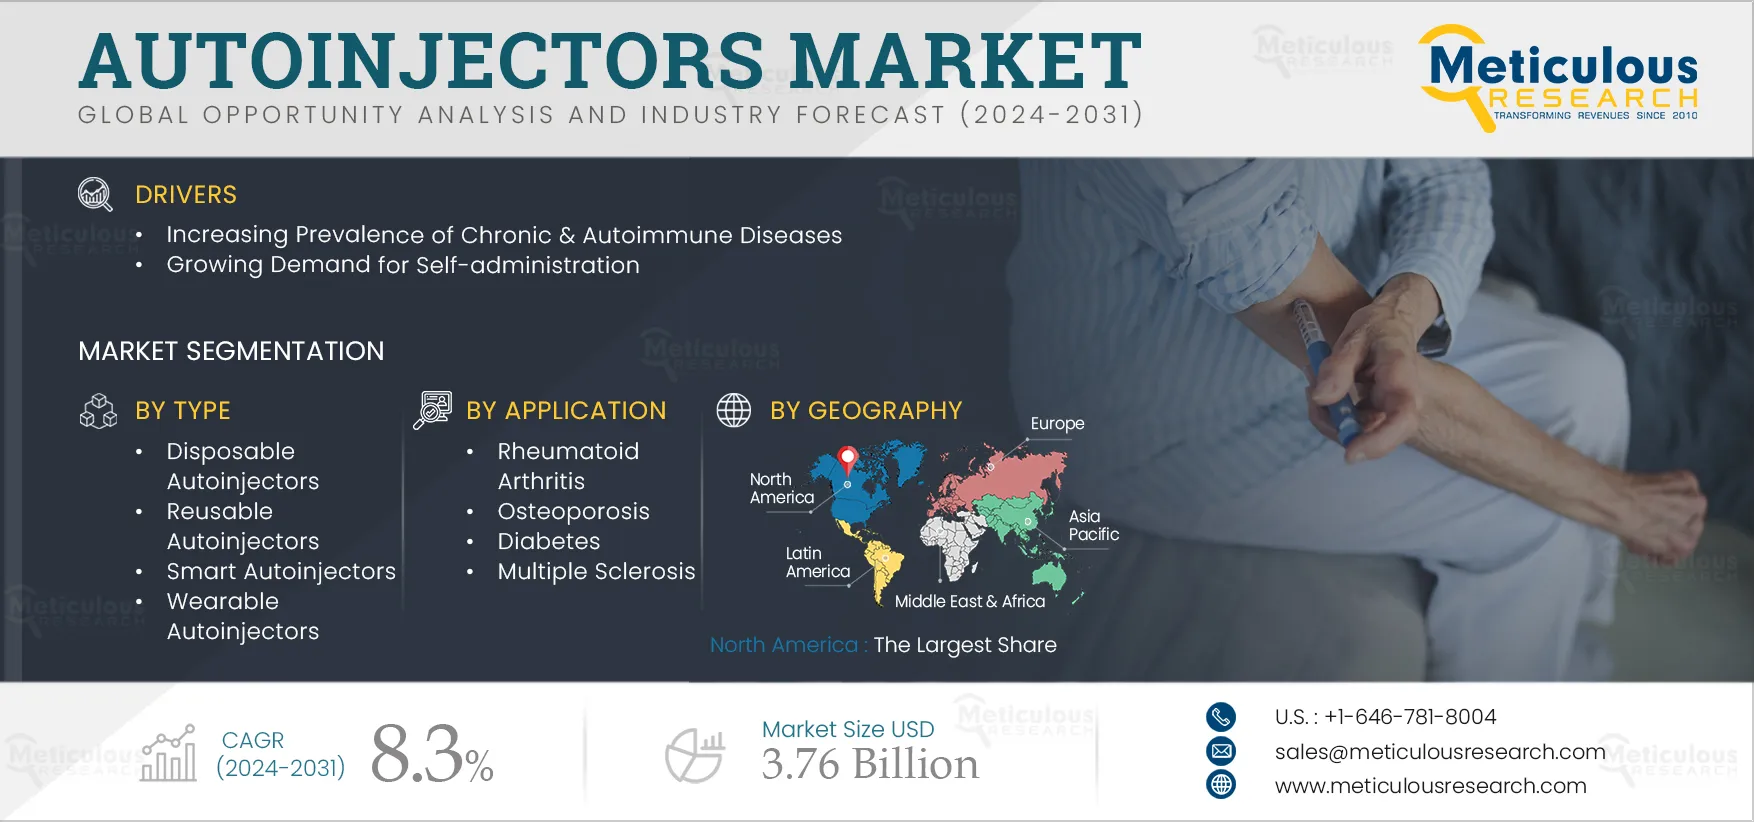
The growth of this market is primarily driven by the increasing prevalence of chronic & autoimmune diseases, the growing demand for self-administration of medicines, and technological advancements in autoinjectors. Moreover, the growing demand for home healthcare and partnerships & collaborations by market players are expected to generate market growth opportunities.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Prevalence of Chronic & Autoimmune Diseases
Autoinjectors are utilized to treat various chronic diseases, including diabetes, osteoporosis, and rheumatoid arthritis, as well as autoimmune diseases and adverse occurrences. For instance:
- According to the International Diabetes Federation, in 2021, 537 million people were diagnosed with diabetes worldwide. Among these, the Western Pacific region accounted for 206 million cases, while Southeast Asia accounted for 90 million, the Middle East & North Africa for 73 million, Europe for 61 million, North America & the Caribbean for 51 million, South and Central America for 32 million, and Africa for 24 million. This number is projected to reach 643 million in 2032 and 783 million in 2045.
- According to the World Health Organization’s (WHO) 2024 data, 18 million people had rheumatoid arthritis in 2019.
- According to a 2024 survey conducted by the International Osteoporosis Foundation (IDF), 43% of women respondents reported having fractured a bone after a simple fall and bump after the age of 50. The percentages were the highest in Japan (73.3%) and the U.K. (60.9%) and lowest in Brazil (21.6%).
Thus, the increasing incidence of chronic & autoimmune diseases is boosting the demand for autoinjectors for proper medication.
Technological Advancements in Autoinjectors
Advancements in autoinjector technology have improved their safety and reliability. Advanced autoinjectors include features that maintain proper dosage precision and avoid accidental needlestick injuries. For instance, needle-retraction systems withdraw the needle after injection to reduce needlestick injuries. Autoinjectors have progressively become more user-friendly. Companies have invested in design innovation to simplify the distribution and use of autoinjectors. These devices are lightweight, small, and have simple mechanics that allow patients to self-administer medication with minimal discomfort and effort.
Moreover, many autoinjectors now have connectivity features that allow them to communicate with smartphones and other devices. This connectivity allows for the gathering of information about injection history, medicine use, and patient adherence. These technological advances in autoinjector performance and design have enhanced treatment adherence, patient experience, and overall safety, driving the adoption of autoinjectors.
Table of contents
14 chapters · 119 sections · 230 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Disposable Autoinjectors | Smart autoinjectors |
| By Route of Administration | Subcutaneous | — |
| By Technology | Manual Autoinjectors | — |
| By Application | Diabetes | — |
| By Distribution Channel | Retail Pharmacies | — |
| By End User | Home Care | — |
By Type
- The disposable autoinjectors segment is expected to account for the largest share of 51.7% of the autoinjectors market.
- The large market share of this segment can be attributed to the advantages of disposable autoinjectors over other types, such as automatic safety features, ease of use (especially for patients with low dexterity), audible and visual feedback indicators, consistent injection activation, complete injection, and controlled injection depth.
- Furthermore, the companies operating in this market are focused on introducing innovative offerings to cater to the rising demand for autoinjectors.
- For instance, in January 2025, Taisho Pharmaceutical Co., Ltd. (Japan) launched the Nanozora 30mg Autoinjector for S.C.
- Injection, a single-use autoinjector dosage form, to prevent needle piercing accidents.
- Such developments are contributing to the segment’s large share.
- However, the smart autoinjectors segment is projected to register the highest CAGR of 9.7% during the forecast period 2025-2032.
- The growth of this segment is driven by technological advancements in autoinjectors and the benefits of smart autoinjectors, such as dosage accuracy through prefilled medication, reduced anxiety due to minimal needle injuries, and improved patient compliance and medication adherence.
By Route of Administration
- The Subcutaneous Segment to Dominate the Autoinjectors Market in 2025
- The subcutaneous segment is expected to account for the larger share of the autoinjectors market.
- The segment’s large market share can be attributed to the availability of a large number of drugs that are administered subcutaneously, and the increasing number of new drugs being launched for subcutaneous self-administration.
- For instance, in May 2022, Jabil, Inc. (U.S.) launched Qfinity, a modular solution for subcutaneous (SC) drug self-administration and a reusable autoinjector platform, to support drug delivery in the pharmaceutical industry.
- Such developments are expected to support the growth of this segment in the coming years.
By Technology
- The manual autoinjectors segment is expected to account for the larger share of the autoinjectors market.
- The segment’s large market share can be attributed to the increasing adoption of manual autoinjectors due to their lower prices compared to automatic injectors, ease of use, and ability to provide controlled and precise dosing.
By Application
- The Diabetes Segment to Dominate the Autoinjectors Market in 2025
- The diabetes segment is expected to account for the largest share of the autoinjectors market.
- The segment’s large market share can be attributed to the increasing number of insulin-dependent patients and the rising number of diabetes cases.
- For instance, according to the International Diabetes Federation, 537 million people were diagnosed with diabetes globally in 2021.
- This number is expected to increase to 783 million in 2045.
- Thus, the increasing number of diabetes cases contributes to the segment’s large market share.
By Distribution Channel
- The retail pharmacies segment is expected to account for the largest share of the autoinjectors market.
- The large market share of this segment can be attributed to the availability of a diverse selection of autoinjectors at retail pharmacies, which enables patients to choose the most suitable autoinjector based on their specific preferences, needs, and healthcare expert recommendations.
- The wide variety of autoinjector options available at retail pharmacies ensures that patients can purchase autoinjectors that best suit their needs.
By End User
- The Home Care Segment to Dominate the Autoinjectors Market in 2025
- The home care segment is expected to account for the largest share of 57.6% of the autoinjectors market.
- The large market share of this segment can be attributed to the increasing adoption of home care devices due to their convenience, precision, and accuracy.
- Additionally, market players have increased their focus on raising awareness about diseases such as diabetes and rheumatoid arthritis, driving the adoption of autoinjectors in home care settings.
- Furthermore, this segment is also projected to register the highest CAGR of 8.8% during the forecast period 2025-2032.
- Patients’ increasing preference for the self-administration of medications and technological advancements in autoinjectors are driving the growth of this segment.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of 36.5% of the autoinjectors market, followed by Europe and Asia-Pacific. North America’s significant market share can be primarily attributed to the presence of major autoinjector manufacturers such as Halozyme, Inc. (U.S.) and Becton, Dickinson and Company (U.S.), the increasing demand for self-administration of drugs, technological advancements in autoinjectors, and the increasing cases of diabetes, osteoporosis, and rheumatoid arthritis in the region. By Geography: North America to Dominate the Autoinjectors Market in 2025
Asia-Pacific
Fastest growthHowever, Asia-Pacific is slated to register the highest CAGR of 8.8% during the forecast period. The growth of this regional market is driven by the growing awareness about autoinjectors, the increasing number of awareness programs focusing on autoimmune diseases in countries such as China and India, and the growing healthcare infrastructure in the region.
Competitive landscape
- October 2024
ALTAVIZ (U.S.) launched AltaVISC, a new autoinjector platform for next-generation therapies.
- May 2024
Coherus BioSciences, Inc. (U.S.) launched the UDENYCA (pegfilgrastim-cbqv), single-dose (6mg/0.6mL), prefilled autoinjector to decrease the incidence of infection as displayed by febrile neutropenia.
- May 2024
C.H. Boehringer Sohn AG & Co. KG (Germany) received the U.S. Food and Drug Administration (FDA) approval for its Cyltezo Pen, a new autoinjector option for Cyltezo (adalimumab-adbm) to treat multiple chronic inflammatory diseases.
- April 2020
Teva Pharmaceuticals USA, Inc. (U.S.) launched an autoinjector device for the AJOVY (fremanezumab-vfrm) injection for the preventive treatment of migraine in adults in the U.S.
- Becton
- Dickinson and Company (U.S.)
- Ypsomed AG · Switzerland
- SHL Medical · Switzerland
- Recipharm AB · Sweden
- Owen Mumford Limited (U.K)
- Halozyme, Inc. (U.S.)
- AstraZeneca (U.K.)
- Teva Pharmaceutical Industries Ltd. · Israel
- Solteam Incorporation Co., Ltd. · China
- Gerresheimer AG · Germany
- West Pharmaceutical Services, Inc. (U.S.)
- Bayer AG · Germany
- Union Medico ApS · Denmark
Frequently asked questions
The Autoinjectors Market comprises devices designed for the self-administration of drugs, typically for chronic conditions like diabetes, rheumatoid arthritis, and other autoimmune diseases. These devices enhance convenience and safety, allowing patients to administer precise doses of medications with minimal effort.
Cite this report
Meticulous Research. (2024). Autoinjectors Market - Global Opportunity Analysis And Industry Forecast (2025-2032) (Report No. MRHC - 1041216). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/autoinjectors-market-5899