Air Conditioners Market (2025-2032)
The Air Conditioners Market was valued at $172.8 billion in 2024. This market is expected to reach $276.7 billion by 2032 from an estimated $183.2 billion in 2025, at a CAGR of 6.1% during the forecast period from 2025 to 2032. Air Conditioners Market Size & Forecast Based on volume, the air conditioners
- Published
- Apr 2025
- Pages
- 310
- Format
- PDF + Excel
- Report ID
- MRSE - 104700
- Base year
- 2032
- 2032 · FORECAST
- $276.7B
- 2032
- $276.7B
- CAGR 2025–2032
- 6.1%
2025–2032 forecast at 6.1% CAGR · hover a bar for the value
Key highlights
The Split ACs Segment to Dominate the Air Conditioners Market in 2025
The Up to 2 Ton Segment to Dominate the Air Conditioners Market in 2025
The Smart ACs Segment to Witness Rapid Growth in the Air Conditioners Market during the Forecast Period
The Residential End Users Segment to Dominate the Air Conditioners Market in 2025
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 310 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2032 |
| CAGR | 6.1% |
| Market Size (Value) in 2025 | USD 183.2 billion |
| Market Size (Value) in 2032 | USD 276.7 billion |
| Market Size (Volume) in 2032 | 1071.5 million units |
| Segments Covered | By Type · Split ACs · Window ACs · Centralized/Ducted ACs · VRF (Variable Refrigerant Flow) Systems · Portable Air Conditioners · By Tonnage · Up to 2 Tons · 2 Tons to 5 Tons · 5 Tons to 10 Tons · More than 10 Tons · By Technology · Inverter ACs · Non-inverter Acs · By Rating · 1 Star ACs · 2 Star ACs · 3 Star ACs · 4 Star ACs · 5 Star Acs · By End User · Residential End Users · Commercial End Users · Industrial End Users |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, Switzerland, Sweden, Belgium, and Rest of Europe), Asia-Pacific (China, Japan, India, Indonesia, South Korea, Singapore, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and Middle East & Africa (UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa) |
| Key Companies | Daikin Industries, Ltd. (Japan), Mitsubishi Electric Corporation (Japan), Hitachi-Johnson Controls Air Conditioning (Japan), Carrier Global Corporation (U.S.), Whirlpool Corporation (U.S.), Haier Smart Home Co. Ltd. (China), LG Electronics (South Korea), Voltas Limited (India), Panasonic Corporation (Japan), Robert Bosch GmbH (Germany), Samsung Electronics Co., Ltd. (South Korea), Fujitsu Limited (Japan), Blue Star Ltd (India), Toshiba Corporation (Japan), Electrolux (Sweden), Gree Electric Appliances Inc. (China), Midea Group Co. Ltd (China), and American Standard Companies Inc. (U.S.) |
Report overview
Segments covered: type, tonnage, technology, rating, end user. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
Based on volume, the air conditioners market is projected to reach 1071.5 million units by 2032, at a CAGR of 7% during the forecast period.
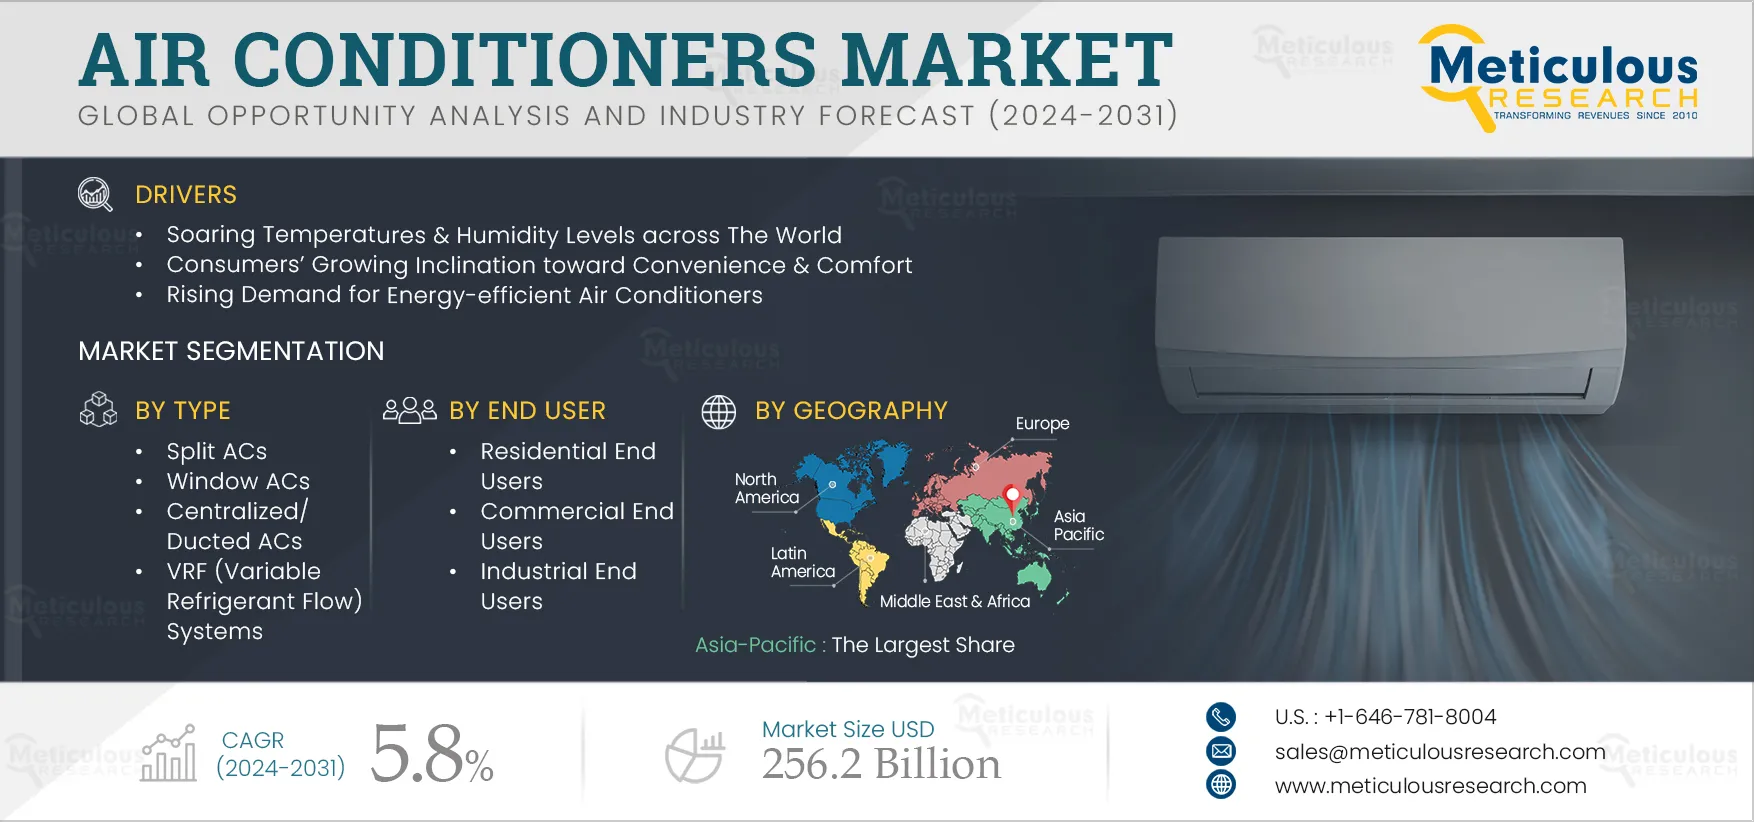
This market's growth is fueled by escalating global temperatures and humidity levels, increasing consumer preference for convenience and comfort, and a rising demand for energy-efficient air conditioners. Additionally, the growing adoption of air conditioners featuring inverter and air purification technologies, coupled with advancements in HVAC systems, is generating significant opportunities for market players.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Consumer Preference for Convenience and Comfort
In today’s fast-paced, urbanized lifestyle, consumers are placing a higher premium on comfort, ease of use, and enhanced living experiences. This behavioral shift is significantly influencing the demand for air conditioners across residential, commercial, and even industrial sectors.
As temperatures rise due to climate change and urban heat island effects, maintaining optimal indoor environments has become a necessity rather than a luxury. Air conditioners are no longer seen as seasonal products—they’re now essential year-round solutions for personal comfort, productivity, and health.
Additionally, modern consumers expect smart, intuitive features that simplify their lives. This has led to growing demand for AC units with:
- Remote operation via mobile apps or voice control
- Programmable timers and smart scheduling
- Self-cleaning functions
- Energy-saving and eco-friendly modes
These features align with the broader trend of home automation and IoT integration, where convenience is a key value proposition.
Furthermore, rising disposable incomes and expanding middle-class populations—especially in emerging markets—are enabling more consumers to invest in premium, comfort-enhancing appliances like air conditioners. They are willing to pay more for silent operation, aesthetic design, and air purification capabilities, reflecting a shift from basic functionality to lifestyle enhancement.
Thus, the growing preference for hassle-free living, comfort optimization, and smart home integration is a strong driver of air conditioner market growth, pushing manufacturers to innovate and personalize offerings to meet evolving consumer expectations.
Rising Demand for Energy-efficient Air Conditioners
Air conditioners are highly energy-intensive, and high AC loads exacerbate power consumption, placing additional pressure on power generation and distribution infrastructure. Consequently, there is a growing demand for energy-efficient air conditioning systems.
To address this need, market players are partnering with public sector organizations to offer energy-efficient solutions. For example, in August 2022, Carrier Global Corporation (U.S.) teamed up with Gallipolis City School District (U.S.) to design and install a multi-building HVAC system aimed at improving indoor air quality (IAQ) and enhancing energy efficiency. By 2050, the average energy efficiency of air conditioners is projected to more than double. According to estimates from the European Union (EU) and Japan, global energy demand from air conditioners is anticipated to triple by 2050, necessitating new electricity capacity equivalent to the combined electricity capacity of the United States. The global stock of air conditioners in buildings is expected to rise to 5.13 billion by 2050, up from 1.6 billion in 2022, translating to the sale of 10 new AC units every second for the next 30 years. This increasing demand for energy-efficient air conditioners is driving the growth of the global air conditioning market, as it aims to reduce energy costs and alleviate the strain on energy infrastructure.
Table of contents
13 chapters · 126 sections · 310 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Split ACs | Centralized/ducted AC |
| By Tonnage | Up to 2 Ton | 2 ton |
| By Technology | While traditional ACs still | Smart ACs |
| By End User | Residential End Users | — |
By Type
- The Split ACs Segment to Dominate the Air Conditioners Market in 2025
- The split ACs segment is expected to account for the largest share of over 56.0% of this market.
- This segment's substantial market share can be attributed to the rising demand for energy-efficient and low-noise air conditioners.
- Additionally, the growing focus of key market players on delivering high-quality air conditioners and introducing innovative split AC models has further contributed to this market dominance.
- However, the centralized/ducted AC segment is expected to register the highest CAGR during the forecast period.
By Tonnage
- The Up to 2 Ton Segment to Dominate the Air Conditioners Market in 2025
- The up to 2 ton segment is expected to account for the largest share of over 66.0% of this market.
- The segment's major market share is driven by the growing demand for customizable air conditioners for small homes and office spaces and the increasing need for 2-ton air conditioners in emerging economies such as Japan, China, and India.
- However, the 2 ton to 5 segment is estimated to record the highest CAGR during the forecast period.
By Technology
- The Smart ACs Segment to Witness Rapid Growth in the Air Conditioners Market during the Forecast Period
- The traditional ACs segment is expected to account for the larger share of this market.
- The segment’s substantial market share can be attributed to their lower upfront cost, widespread availability, and consumer familiarity with basic cooling technology.
- However, smart ACs are witnessing rapid growth, particularly in urban, high-income, and tech-savvy markets.
- The surge in smart AC adoption is driven by rising energy efficiency demands, government regulations (like BEE star ratings), and the increasing integration of smart home ecosystems (Google Home, Alexa).
- Additionally, consumers are willing to pay a premium for features like remote control, AI-based cooling, and long-term cost savings through reduced electricity bills.
- While traditional ACs still lead in volume, the smart AC segment is expanding faster due to urbanization, rising disposable incomes, and environmental awareness, making it the future growth engine of the industry.
By End User
- The residential end users segment is expected to account for the largest share of over 80.5% of this market.
- The segment’s large market share can be attributed to the growing acceptance of smart home technology, the increasing trend among developers to offer air-conditioned apartments, and the rising need to enhance indoor air quality.
- Urbanization patterns play a crucial role, as growing middle-class populations in developing nations increasingly migrate to cities where apartment living and smaller spaces require compact cooling solutions.
- The improvement in living standards worldwide enables more households to afford what was once considered a premium appliance.
- Additionally, changing housing architecture with better insulation and smaller rooms makes residential spaces more conducive to air conditioning use.
- The residential segment also benefits from replacement cycles and technological upgrades, as consumers periodically swap older units for more energy-efficient models to reduce electricity costs.
- Government initiatives in many countries, including subsidies for energy-efficient models and tax incentives, further stimulate household adoption.
- Unlike commercial applications where cooling systems are often built into infrastructure, residential demand creates a continuous market for standalone units across various price points.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of over 48.0% of the air conditioners market. APAC’s large market share is attributed to several factors: key players' increased focus on launching innovative air conditioning systems, a growing emphasis on energy-efficient cooling solutions, expanding construction and development activities, rising demand for air conditioning driven by climate change, availability of cost-effective financing options for purchasing air conditioners, increasing need for space cooling, and rising income levels in the region. Moreover, the Asia-Pacific region is poised to record the highest CAGR during the forecast period.
Middle East & Africa
Furthermore, the Middle East and Africa represent a high-potential air conditioner market driven by unique climatic and socioeconomic factors. In the Gulf region, extreme summer temperatures routinely surpassing 50°C create non-discretionary demand for cooling solutions, particularly in rapidly developing urban centers. Governments are implementing ambitious construction programs alongside sustainability initiatives, creating opportunities for both conventional and energy-efficient systems. Across Africa, rapid urbanization and improving living standards are driving first-time AC adoption, particularly in major economic hubs. The continent's limited electrical infrastructure is simultaneously fostering innovation in alternative cooling solutions, including solar-powered and hybrid systems. Market growth is further supported by increasing commercial sector demand from hotels, offices, and retail spaces in developing business districts. The region presents distinct product requirements, with durability in harsh climates and energy efficiency becoming key purchasing factors. Manufacturers able to offer solutions tailored to local conditions - including high-temperature performance and power fluctuation resilience - stand to benefit significantly. Service models and financing solutions are also emerging as critical enablers for broader market penetration across income segments.
Competitive landscape
- March 2025
Japanese conglomerate Sharp Corporation, through its wholly-owned subsidiary Sharp Business Systems (India), on Tuesday announced its re-entry into the Indian air-conditioner market. The company made a comeback in the Indian AC Industry, which is growing in double digits, with the launch of Reiryou, Seiryo & Plasma Chill Series.
- January 2025
Samsung India launched its 2025 lineup of BESPOKE AI WindFree™ Air conditioners, a fusion of cutting-edge AI technology and premium design.
- April 2024
Mitsubishi Heavy Industries (Japan) Thermal Systems commenced mass production of its KXZ3 series of commercial multi-split air conditioners for global markets. The new series is scheduled to debut in the European market this summer, with subsequent launches planned for Australia, New Zealand, and Turkey.
- March 2024
Blue Star Ltd (India) introduced a new comprehensive range of room air conditioners, featuring both a 'best-in-class affordable' range and a 'flagship premium' range. The company launched over 100 models, encompassing inverter, fixed-speed, and window ACs across various price points to address the needs of every consumer segment.
- March 2023
LG Electronics, a leading consumer durable and air conditioner manufacturer in India, launched its new 2023 range of DUALCOOL Inverter air conditioners as part of its AI+, health, and hygiene portfolio. The latest range includes air conditioners equipped with features such as AI+, Plasmaster Ionizer++, hot and cold functionality, and LG ThinQ (Wi-Fi-enabled) technology, which allows for touch-free operation through voice commands.
- Daikin Industries, Ltd. · Japan
- Mitsubishi Electric Corporation · Japan
- Hitachi-Johnson Controls Air Conditioning · Japan
- Carrier Global Corporation (U.S.)
- Whirlpool Corporation (U.S.)
- Haier Smart Home Co. Ltd. · China
- LG Electronics · South Korea
- Voltas Limited · India
- Panasonic Corporation · Japan
- Robert Bosch GmbH · Germany
- Samsung Electronics Co., Ltd. · South Korea
- Fujitsu Limited · Japan
- Blue Star Ltd · India
- Toshiba Corporation · Japan
- Electrolux · Sweden
- Gree Electric Appliances Inc. · China
- Midea Group Co. Ltd · China
- American Standard Companies Inc. (U.S.)
Frequently asked questions
The air conditioners market study focuses on the market assessment and opportunity analysis through the sales of air conditioners across different regions and countries across different market segmentation; this study is also focused on competitive analysis for air conditioners based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2025). Air Conditioners Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRSE - 104700). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/air-conditioners-market-5384