Silicon Carbide Market (2025-2032)
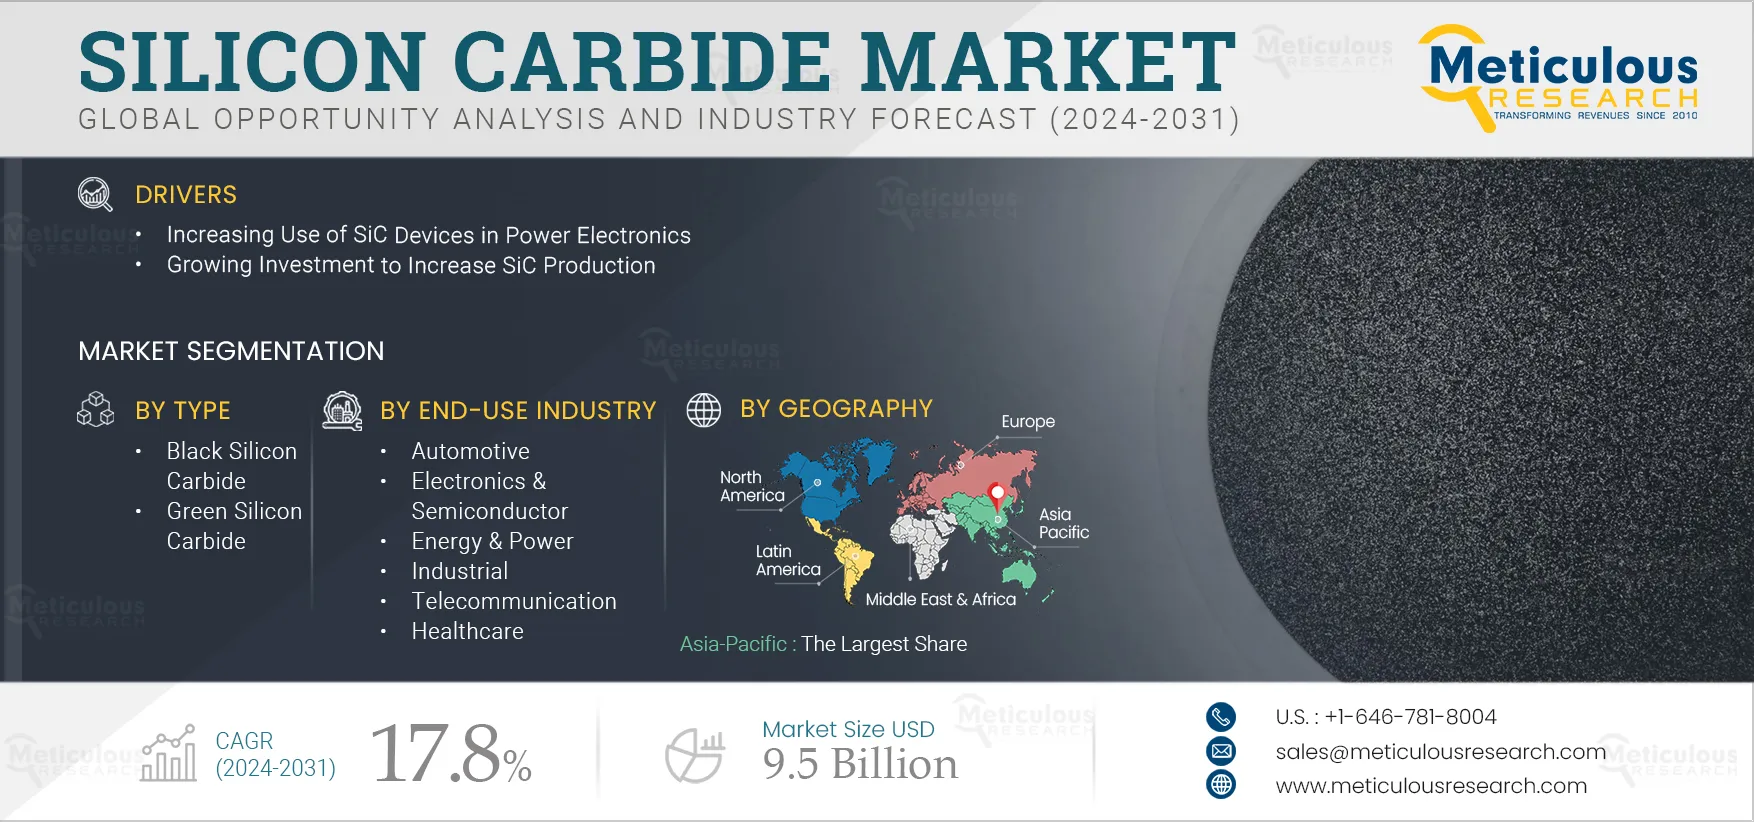
The Silicon Carbide Market is expected to reach $9.5 billion by 2032, at a CAGR of 17.8% from 2025 to 2032.
- Published
- Jan 2024
- Pages
- 200
- Format
- PDF + Excel
- Report ID
- MR-1282
- Base year
- 2024
- 2032 · FORECAST
- $9.50B
- 2032
- $9.50B
- CAGR 2025–2032
- 17.8%
2024 baseline · 2025–2032 forecast at 17.8% CAGR · hover a bar for the value
Key highlights
By Type: In 2025, the Black Silicon Carbide Segment to Dominate the Silicon Carbide Market
By Forming Method: In 2025, the Sintering Segment to Dominate the Silicon Carbide Market
By End-Use Industry: In 2025, the Electronics & Semiconductor Segment to Dominate the Silicon Carbide Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 200 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR | 17.8% |
| Market Size (Value) | USD 9.5 Billion by 2032 |
| Segments Covered | By Type · Black Silicon Carbide · Green Silicon Carbide · By Forming Method · Reaction Bonding · Sintering · Recrystallization · Other Methods · By End-use Industry · Automotive · Electronics & Semiconductor · Energy & Power · Industrial · Telecommunication · Healthcare · Other End-use Industries |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, Switzerland, Netherlands, and Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Singapore, Malaysia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and Middle East & Africa (UAE, Israel, Rest of Middle East & Africa). |
| Key Companies | AGSCO Corporation (U.S.), Carborundum Universal Limited (India), Washington Mills Electro Minerals Limited (U.S.), CoorsTek Inc. (U.S.), Entegris, Inc. (U.S.), ESD-SIC bv (Netherlands), Snam Abrasives Pvt. Ltd. (India), Morgan Advanced Materials (U.K.), Saint-Gobain (France), Schunk Group (Germany), Blasch Precision Ceramics, Inc. (U.S.), and Christy Refractories (U.S.). |
Report overview
Segments covered: type, forming method, end-use industry. Regions: North America, Europe, Asia-Pacific, Latin America.
Factors driving this market's growth include increased use of SiC devices in power electronics and increased investment in SiC manufacture. Furthermore, there should be room for market expansion due to the rising need for SiC in the oil and gas sector and its growing application in electric cars. The availability of substitute materials, however, may hinder the market's growth. The high cost of fabrication and raw materials presents challenges to the growth of this market.
Market dynamics
5 factors across 2 forcesIncreasing Use of SiC in Power Electronics
Silicon carbide is a compound semiconductor material made up of silicon and carbide atoms. SiC is transforming the way electricity is converted, managed, and distributed. Silicon has long been the dominating material used in power electrical devices due to its abundance and inexpensive cost. However, as these systems require increased efficiency, power density, and reliability, SiC has emerged as a better option.
SiC's superior material properties, including higher breakdown voltage and thermal conductivity, enable designing smaller and lighter power electronic systems. SiC devices let manufacturers achieve higher power densities, meaning more energy can be delivered using smaller and lighter components. Thus, the rising adoption of SiC in power electronics is expected to drive market growth in the forecast period.
Growing Investment to Increase SiC Production
Silicon carbide is a critical material for high-power, high-temperature applications and is extremely difficult to produce. In recent years, driven by the burgeoning development in applications such as new energy vehicles, 5G, solar energy, and photovoltaics, the demand for silicon carbide has shown massive growth. Given the promising market prospects, major silicon carbide-related companies worldwide are accelerating their strategic deployments and are investing to maximize the manufacturing and production efficiency of SiC.
Table of contents
11 chapters · 103 sections · 200 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Black Silicon Carbide | Green silicon carbide |
| By Forming Method | Sintering | Recrystallization |
| By End-Use Industry | Electronics & Semiconductor | Automotive |
By Type
- The black silicon carbide segment is expected to account for the larger share of 72% of the global silicon carbide market.
- Black silicon carbide contains about 98.5% SiC; its toughness is higher than that of green silicon carbide.
- This segment’s large market share is attributed to the rising use of black SiC for processing materials with low tensile strength, such as glass, ceramics, stone, refractory materials, cast iron, and non-ferrous metals.
- However, the green silicon carbide segment is expected to register the highest CAGR during the forecast period.
- Green silicon carbide is essentially the same as black silicon carbide, only the raw material and manufacturing process are different, the product is a green translucent body, and its hardness and purity are superior to black silicon carbide.
- The growth in this segment is driven by the rising demand for green SiC in refractory materials and various abrasive tool manufacturing.
By Forming Method
- The Sintering Segment to Dominate the Silicon Carbide Market
- The sintering segment is expected to account for the largest share of 28% of the global silicon carbide market.
- This segment’s large market share is attributed to its properties, such as high strength, hardness, and thermal conductivity, and the rising use of sintered SiC in applications such as tools, bearings, heat exchangers, combustion nozzles, and aerospace components.
- However, the recrystallization segment is expected to register the highest CAGR during the forecast period.
- This segment’s growth is due to its better thermal conductivity and thermal shock resistance compared with other prime production methods and the rising use of recrystallized SiC in structural materials, porous materials, heat exchangers, electrical functional materials, and composite materials.
By End-Use Industry
- The electronics & semiconductor segment is expected to account for the largest share of 23% of the global silicon carbide market.
- This segment’s large market share is attributed to its high voltage resistance, rising production of semiconductor devices using SiC, including Schottky diodes (also called Schottky barrier diodes, or SBDs), junction-gate FETs (or JFETs), and MOSFETs utilized in high-power switching applications.
- However, the automotive segment is expected to register the highest CAGR during the forecast period.
- This segment’s growth is driven by the rising demand for high quality, reliability, and efficiency in the automotive industry, the rising use of SiC to make automotive parts such as brake & engine components and suspension systems, rising demand to create increasingly efficient and high-performance electric vehicles and the potential of SiC to improve vehicle performance and efficiency while reducing environmental impact.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of 55% of the silicon carbide market. This region’s large market share is attributed to the rising adoption of advanced ceramics in various end-use industries, ongoing R&D activities focused on enhancing ceramic properties and manufacturing processes, and rising investment in manufacturing SiC components. Moreover, Asia-Pacific is also expected to register the highest CAGR of 18.4% during the forecast period. This region's rapid growth is primarily driven by the growing automotive industry, rising demand for electric vehicles, and rising efforts by market players to expand their business in the region. For example, in July 2024, Silicon Power Group (US) announced a 10-billion-rupee (USD 121.73 million) investment to establish a facility in India's Odisha state to manufacture 150-millimeter silicon carbide.
Competitive landscape
- June 2025
Onsemi (U.S.) announced plans to develop a vertically integrated silicon carbide (SiC) manufacturing facility in the Czech Republic with a multi-year brownfield investment of up to USD 2 billion as part of their long-term capital expenditure strategy.
- —
Mitsubishi Electric Corporation (Japan) declared in March 2024 that it would double an earlier stated investment plan to roughly 260 billion Yen (USD 1.61 billion) in the five years leading up to March 2026, primarily for building a new wafer plant to boost silicon carbide (SiC) power semiconductor production.
- —
Microchip Technology Inc. (U.S.) stated in February 2024 that it will invest USD 880 million over the course of the following few years to increase the production capacity of silicon (Si) and silicon carbide (SiC) at its Colorado Springs, Colorado, manufacturing facility.
- —
A capital investment in Fuji Electric Tsugaru Semiconductor Co., Ltd. (Japan) was made in January 2022 by Fuji Electric Co., Ltd. (Japan) in order to accelerate SiC power semiconductor production.
- November 2024
Mitsubishi Electric Corporation (Japan) collaborated with Nexperia B.V. (Netherlands) to develop SiC power semiconductors for the power electronics market. Mitsubishi Electric will use its wide-bandgap semiconductor capabilities to create and provide SiC MOSFET chips, which Nexperia will use to manufacture SiC discrete devices.
- June 2024
STMicroelectronics (Switzerland) and Sanan Optoelectronics (China) established a joint venture to manufacture silicon carbide in Chongqing. The initiative was estimated to cost over $3.2 billion, with approximately $2.4 billion in capital expenditure over the following five years.
- AGSCO Corporation (U.S.)
- Carborundum Universal Limited · India
- Washington Mills Electro Minerals Limited (U.S.)
- CoorsTek Inc. (U.S.)
- Entegris, Inc. (U.S.)
- ESD-SIC bv · Netherlands
- Snam Abrasives Pvt. Ltd. · India
- Morgan Advanced Materials (U.K.)
- Saint-Gobain · France
- Schunk Group · Germany
- Blasch Precision Ceramics, Inc. (U.S.)
- Christy Refractories (U.S.)
Frequently asked questions
The silicon carbide market study focuses on the market assessment and opportunity analysis through the sales of silicon carbide across different regions and countries across different market segmentations; this study is also focused on competitive analysis for silicon carbide based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2024). Silicon Carbide Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MR-1282). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/silicon-carbide-market-5965