Pea Starch Market (2022-2029)
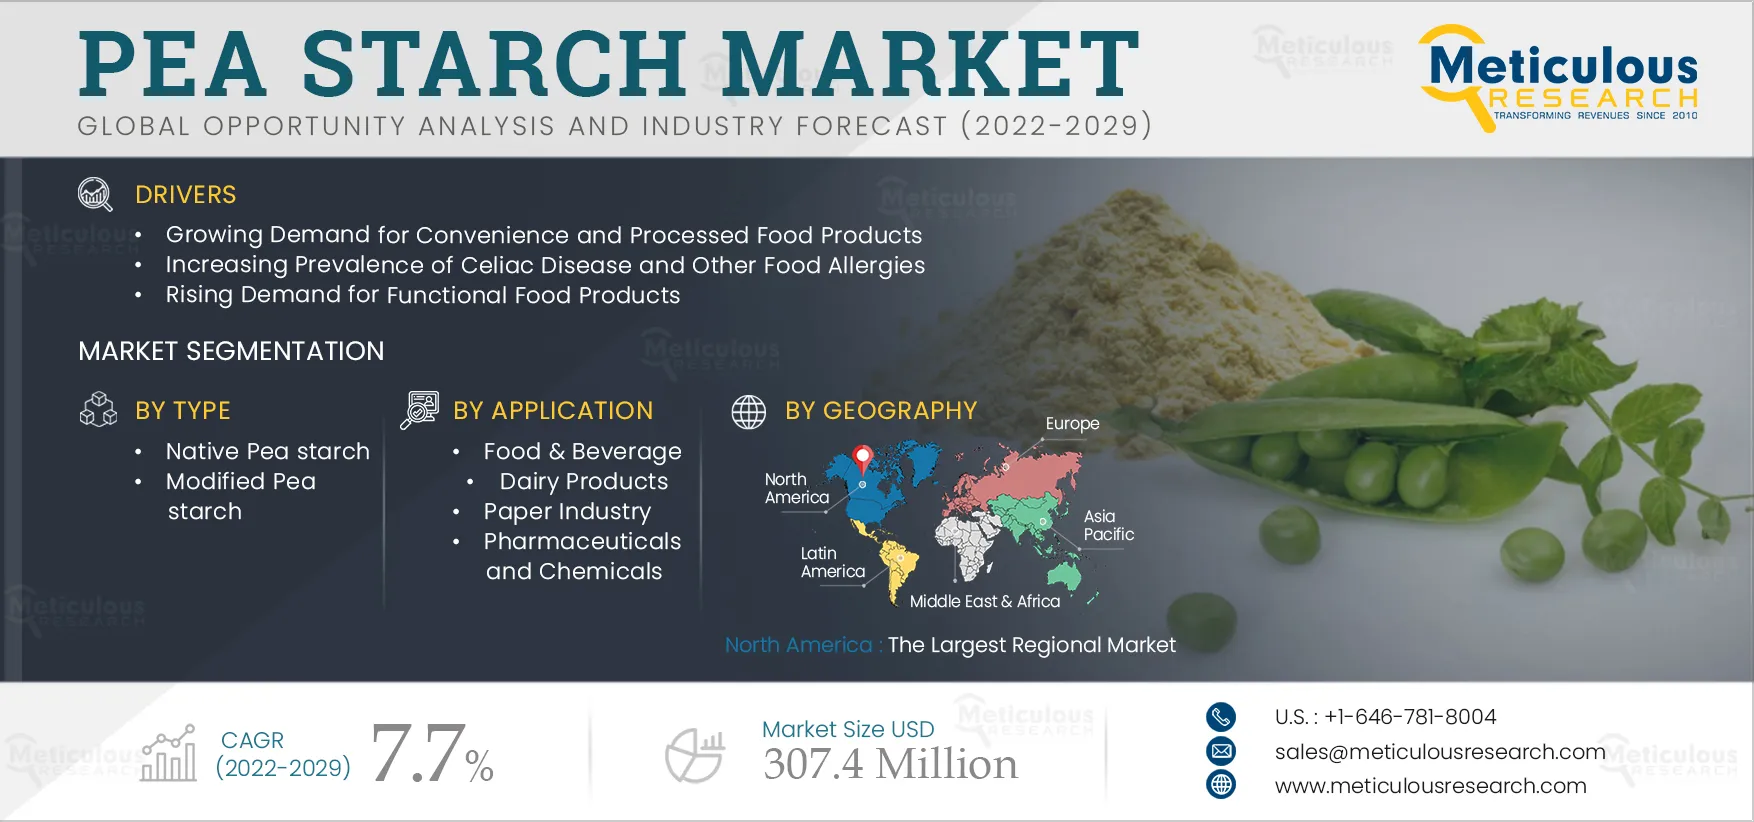
The Pea Starch Market is projected to reach $307.4 million by 2029, at a CAGR of 7.7% from 2022 to 2029.
- Published
- Jan 2023
- Pages
- 190
- Format
- PDF + Excel
- Report ID
- MRFB - 104705
- Base year
- 2021
- 2029 · FORECAST
- $307.4M
- 2029
- $307.4M
- CAGR 2022–2029
- 7.7%
2021 baseline · 2022–2029 forecast at 7.7% CAGR · hover a bar for the value
Key highlights
In 2022, the conventional segment is expected to account for the largest share of the market
The native segment is projected to record the fastest growth rate during the forecast period
In 2022, the thickener & gelling agent segment is expected to account for the largest share of the market
In 2022, the food & beverage segment is expected to dominate the pea starch market
North America: The Largest Regional Market
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2021 |
| Estimated Year | 2022 |
| Forecast Period | 2022–2029 |
| Market Size (2029) | USD 307.4 million |
| CAGR (2022–2029) | 7.7% |
| Format | PDF, Excel & Cloud Portal · 190 pages |
| Segments Covered | By Nature: Conventional Pea starch, Organic Pea starch · By Type: Native Pea starch, Modified Pea starch · By Function: Thickener & Gelling Agent, Binder, Stabilizer, Disintegrant, Other Functions · By Application: Food & Beverage Bakery & Confectionery Products, Dairy Products, Soups & Sauces and Savory & Prepared Food Products, Meat & Seafood Products, Other Food & Beverage Products |
| Countries Covered | North America (Canada), Europe (Germany, France, U.K., Italy, Spain, Rest of Europe), Asia-Pacific (China, Japan, India, Australia, Rest of Asia-Pacific), Latin America (Brazil) |
| Key Companies | Axiom Foods Inc., Dakota Dry Bean Inc., American Key Products, Inc., Shandong Jianyuan Foods Co., Ltd., Puris Proteins, LLC, Ebro Foods, S.A. |
Report overview
Segments covered: nature, type, function, application. Regions: North America, Europe, Asia-Pacific, Latin America.
Pea starch is extracted from dry peas and has a wide range of food & beverage applications. The growing demand for convenience and processed food products, increasing prevalence of celiac disease and other food allergies, rising demand for functional food products, and the growing vegan population are the key factors driving the growth of the pea starch market. However, the availability of alternative starches and a decrease in the production of dry peas are expected to hinder the growth of this market to a notable extent.
Furthermore, the future market for pea starch-based bioplastics and a rise in demand from the pet food industry will provide significant growth opportunities for pea starch manufacturers in the coming years.
The COVID-19 pandemic severely affected human health and well-being. To control the spread of the virus, governments worldwide announced partial or complete lockdowns, which severely impacted many industries, including food & beverage, pharmaceuticals, pulp & paper, home & personal care, dietary supplements, animal feed, and textile. The pandemic had both negative and positive effects on the pea starch market.
The COVID-19 outbreak created a severe public health emergency globally. Many countries worldwide announced complete nationwide, state-wide, or citywide lockdowns to combat and control the spread of this disease, halting travel, transport, manufacturing, and non-essential trade.
According to the United States Department of Agriculture (USDA), some major agricultural exporters, such as Russia, Ukraine, and Vietnam, introduced export quotas or outright bans of international shipments, primarily food products. Agricultural production was also hampered due to the low availability of labor during the COVID-19 pandemic. According to the European Parliament, due to the pandemic's impact on the agri-food sector, governments and commissions had to adopt various measures to support producers. People also preferred homemade food over dining out. Additionally, the food demand from hotels and restaurants was reduced due to social distancing practices, which impacted the demand for pea starch in the market.
According to the Organisation for Economic Co-operation and Development (OECD), imports and exports in many countries were stopped, and ports were closed due to regulations and restrictions. Several shipping containers were docked in Chinese ports, and restrictions on their movement led to a shortage that affected the cargo prices, demand for food products, and traffic volume. Air freight costs rose by about 30% in China and North America and 60% on some routes to Europe and North America. Hence, it affected the export market due to higher logistics costs and movement restrictions.
However, the demand and use of pea starch increased in industries such as food & beverage, pet food, and pharmaceuticals due to increased awareness of health & wellbeing. During the COVID-19 pandemic, the demand for ready-to-eat food products increased. The young generation preferred ready-to-cook or ready-to-eat products.
Moreover, there was a rise in the demand for functional & immunity-boosting products as people sought solutions to boost their overall health. During the COVID-19 pandemic, health-conscious customers turned to functional and gluten-free products. Hence, increasing health consciousness and the high demand for functional food products encouraged manufacturers and product formulators to focus on these products. The COVID-19 pandemic also spurred a shift toward healthy living, improving people's food habits. For instance, according to the Food Information Council survey 2021, in 2020, 85% of Americans changed their food habits, and in 2021, 39% followed specific diets. These changing food habits boosted the healthy living trend in the U.S., further driving the demand for functional products in the country. Therefore, strong demand for pharmaceuticals, food & beverage, cosmetics and home care support the growth of the pea starch market. Considering the overall impact of COVID-19 on various industries that use pea starch, the impact of the pandemic on the pea starch market was positive.
Report infographic
Market dynamics
1 factors across 1 forceGrowing Demand for Convenience and Processed Foods
Convenience foods require less or no time for preparation and cleanup. These are restaurant meals and ready-to-eat food from grocery stores. Most people in urban areas live busy lives and do not wish to spend much time preparing food. Due to greater time constraints from work, childcare, and commuting, they prefer convenience foods.
Consumer demand for processed and convenience food has grown substantially over the past decades. A greater need for convenience drives the processed food market due to hectic lifestyles, socioeconomic changes, and urbanization. In addition, consumers' rising buying power, growing awareness for healthy and readily available foods, and changing food habits and meal patterns drive the demand for processed and convenience food. According to Eating Better's Ready Meals Survey, in 2020, 88% of adults in the U.K. consumed ready-to-eat and ready-to-cook foods, and two in five people ate packaged meals weekly.
More than half of the world's population lives in urban areas. According to the United Nations World Urbanization Report, the world's urban population has grown rapidly from 439,498,772 in 2015 to 471,031,528 in 2019, which indicates that almost 55% of the world's population lives in urban areas. This proportion is expected to reach 68% by 2050. As a result, urban consumers are gaining exposure to a much wider choice and better food availability than those living in rural areas. This trend contributes significantly toward improved living standards and rising incomes, which influences the affordability of processed food to a greater extent. Hence, the growing consumer for convenience and processed food drives the growth of the pea starch market, as pea starch is a universal binder and thickener for many applications in the food industry.
Table of contents
13 chapters · 103 sections · 190 pages · click to expandSegmental analysis
| Segment | Largest share (2022) | Fastest growth (2022–2029) |
|---|---|---|
| By Nature | Conventional | — |
| By Type | — | Native pea starch |
| By Function | Thickener & gelling agent | — |
| By Application | Food & beverage | — |
By Nature
- The conventional segment is expected to account for the largest share of the market
- The conventional pea starch segment is expected to account for the largest share of the pea starch market.
- Key factors contributing to the large market share of this segment are the wide availability of crops grown through traditional harvesting methods (using chemical fertilizers), easy accessibility to cost-effective conventional peas, the longer shelf life of conventional pea starch, and the wide availability of substantial crop varieties.
By Type
- The native segment is projected to record the fastest growth rate during the forecast period
- The native pea starch segment is projected to register the highest CAGR during the forecast period.
- The fast growth of this segment is mainly attributed to the growing trend of sustainable and natural food and awareness about clean-label products, and a wide range of applications in the food and beverage industry due to its high functionality and support to non-GMO, gluten-free, grain-free, vegan, vegetarian, allergen-friendly, and kosher trend.
By Function
- The thickener & gelling agent segment is expected to account for the largest share of the pea starch market.
- The large market share of this segment is mainly attributed to the growing use of pea starch as a thickener and gelling agent in the food & beverage, pharmaceuticals, and pet food industries due to its enhanced functional properties.
- It primarily provides thickness and gelling texture in food products and maintains stable texture in various conditions.
By Application
- The food & beverage segment is expected to account for the largest share of the pea starch market.
- The dominant position of this segment is mainly attributed to the wide range of pea starch applications in the food & beverage industry due to its functionality and use in non-GMO, gluten-free, grain-free, vegan, vegetarian, allergen-friendly, clean-label, and kosher foods.
- Also, the rising demand for ready-to-eat and ready-to-cook food products, increasing consumer awareness regarding the consumption of food products with natural ingredients, and the growing consumer preference for clean label & healthy products further supports the growth of this segment.
Geographic analysis
North America
Largest shareThe pea starch market is divided into five regions: North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. In 2022, North America is expected to account for the largest share of the pea starch market due to the large-scale production of dry peas, the well-established food & beverage industry, rising demand for convenience and processed foods, increase in demand for gluten-free food products, and strong demand for organic and free from food. North America: The Largest Regional Market
Asia-Pacific
Fastest growthHowever, Asia-Pacific is projected to register the highest CAGR during the forecast period of 2022–2029.
Competitive landscape
- Axiom Foods Inc.
- Dakota Dry Bean Inc.
- American Key Products, Inc.
- Shandong Jianyuan Foods Co., Ltd.
- Puris Proteins, LLC
- Ebro Foods, S.A.
Frequently asked questions
The pea starch market is projected to reach $307.4 million by 2029, at a CAGR of 7.7% from 2022 to 2029.
Cite this report
Meticulous Research. (2023). Pea Starch Market - Global Opportunity Analysis and Industry Forecast (2022-2029) (Report No. MRFB - 104705). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/pea-starch-market-5389