Optical Coatings Market (2025-2032)
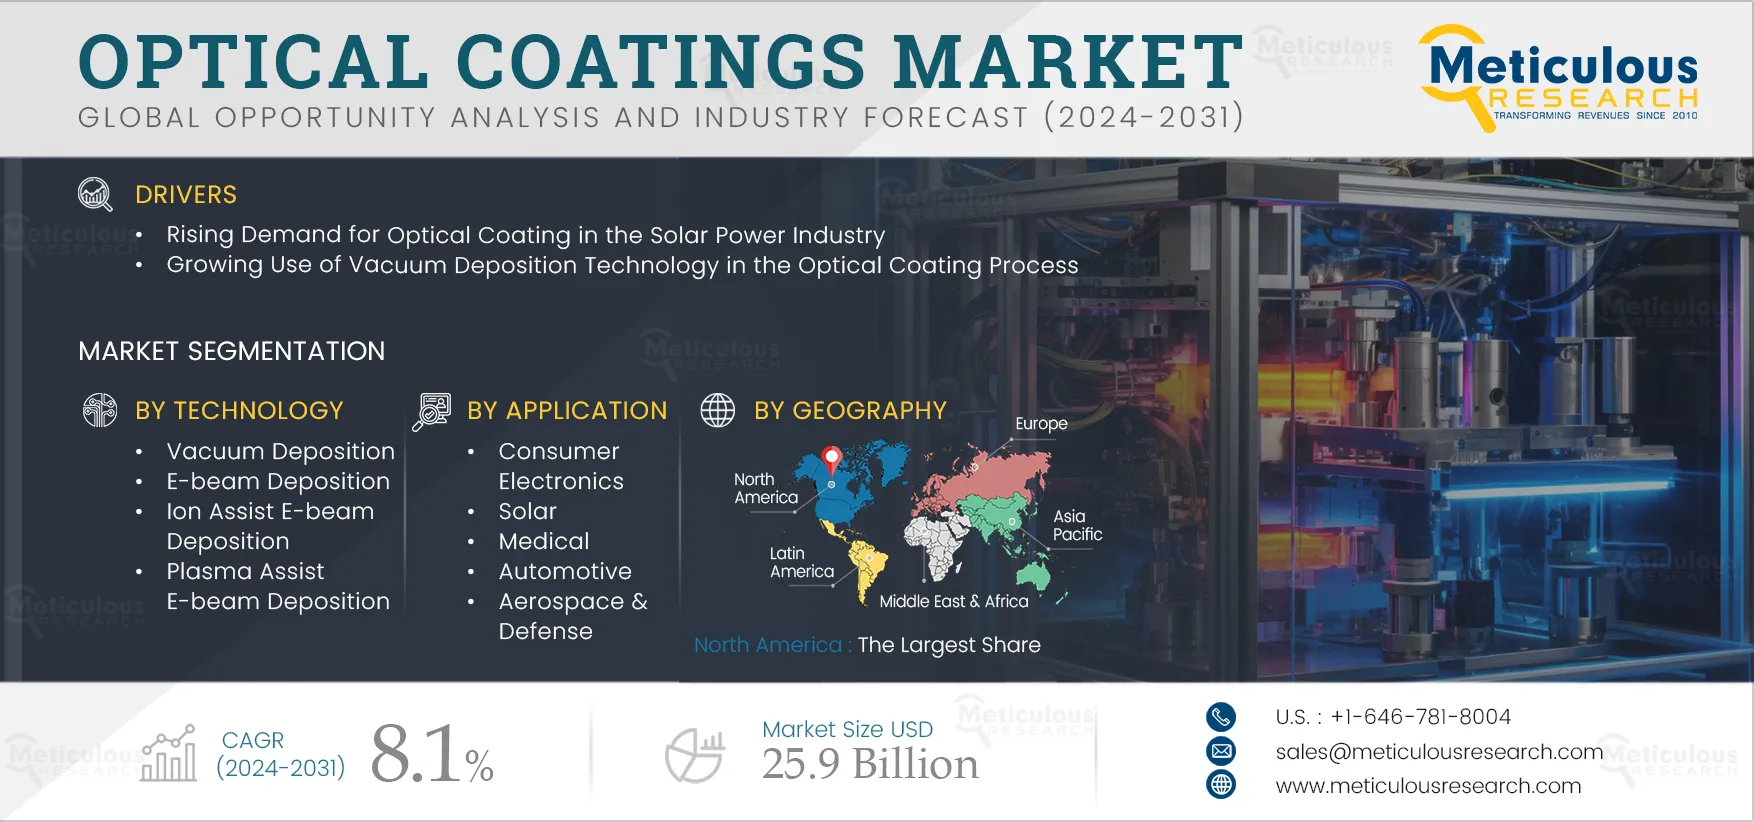
The Optical Coatings Market is projected to reach $25.9 billion by 2032, at a CAGR of 8.1% from 2025–2032.
- Published
- Sep 2024
- Pages
- 220
- Format
- PDF + Excel
- Report ID
- MRCHM - 1041272
- Base year
- 2024
- 2032 · FORECAST
- $25.90B
- 2032
- $25.90B
- CAGR 2025–2032
- 8.1%
2024 baseline · 2025–2032 forecast at 8.1% CAGR · hover a bar for the value
Key highlights
By Type: In 2025, the Anti-reflective Coatings Segment to Dominate the Optical Coatings Market
By Material: In 2025, the Silicon Dioxide Segment to Dominate the Optical Coatings Market
By Technology: In 2025, the Vacuum Deposition Segment to Dominate the Optical Coatings Market
By Application: In 2025, the Consumer Electronics Segment to Dominate the Optical Coatings Market
In 2025, North America to Dominate the Optical Coatings Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 220 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 8.1% |
| Market Size (Value) | $25.9 Billion by 2032 |
| Segments Covered | By Type · Anti-reflective Coatings · High-reflective Coatings · Filter Coatings · Beam Splitter Coatings · Transparent Conductive Coatings · Polarizing Coatings · Other Coatings · By Material · Silicon Dioxide · Titanium Dioxide · Magnesium Fluoride · Fluorides · Germanium · Metal Coatings · Dielectric Coatings · Other Coating Materials · By Technology · Vacuum Deposition · E-beam Deposition · Ion Assist E-beam Deposition · Plasma Assist E-beam Deposition · Advanced Plasma Sputtering · Other Coating Technologies · By Application · Consumer Electronics · Solar · Medical · Aerospace & Defense · Automotive · Telecommunication · Transportation · Other Applications |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Netherlands, Spain, Sweden, and Rest of Europe), Asia-Pacific (China, India, Japan, South Korea, Singapore, Australia & New Zealand, Indonesia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (Saudi Arabia, UAE, Israel, and Rest of the Middle East & Africa) |
| Key Companies | DuPont de Nemours, Inc. (U.S.), Carl Zeiss AG (Germany), Nippon Sheet Glass Co., Ltd. (Japan), Inrad Optics, Inc. (U.S.), PPG Industries, Inc. (U.S.), Newport Corporation (A Subsidiary of MKS Instruments, Inc.) (U.S.), Coherent Corp. (U.S.), ALLUXA, INC. (A Subsidiary of Enpro Inc.) (U.S.), Materion Corporation (U.S.), Reynard Corporation (U.S.), Chroma Technology Corp. (U.S.), Cascade Optical Corporation (U.S.), Abrisa Technologies (U.S.), Surface Optics Corporation (U.S.), and Optimax Systems, Inc. (U.S.) |
Report overview
Segments covered: type, material, technology, application. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The growth of the optical coatings market is driven by the rising demand for optical coating in the solar power industry and the increasing use of vacuum deposition technology. Furthermore, the increasing demand for optical coating for healthcare & biotechnology applications is expected to generate growth opportunities for the players operating in this market.
Report infographic
Market dynamics
3 factors across 2 forcesRising Demand of Optical Coatings in the Solar Power Industry
The solar power industry is experiencing rapid growth. Optical coatings play a vital role in improving solar panels by reducing reflectance and enhancing light absorption, resulting in increased electricity generation. The use of optical coatings in solar power lowers the total cost per unit of electricity generated, making solar energy more competitive compared to traditional fossil fuels. Optical coatings also protect solar panels from environmental variables such as moisture, dust, and UV radiation, extending their lifespan and lowering maintenance costs.
Additionally, technological advancements and innovations in coating materials and techniques, such as anti-soiling coatings that prevent dust buildup, contribute to improved performance. Furthermore, the growing shift toward renewable energy sources, fueled by increasing environmental concerns and regulatory mandates, is accelerating the implementation of solar power technologies. This surge in demand increases the need for high-performance optical coatings.
Growing utilization of Vacuum Deposition Technology in the Optical Coating Process
In recent years, vacuum deposition technology has been increasingly used in the optical coating process to produce high-performance optical coatings with low reflectance, a wide range of wavelengths, high reflectivity, and selective transmission.
Vacuum deposition techniques such as physical vapor deposition (PVD) and chemical vapor deposition (CVD), which offer control over the deposition process, are increasingly being adopted in optical coating processes. These techniques enable the development of thin films with highly uniform thickness and optical properties, which is crucial for achieving the appropriate optical qualities in coatings. Additionally, vacuum deposition processes can be used for specific optical functionalities such as anti-reflection, high reflectivity, or spectral filtering.
Moreover, vacuum deposition processes are scalable from small-scale laboratory applications to large-scale industrial manufacturing. Thus, vacuum deposition is becoming increasingly popular for optical coatings in industries such as solar energy, aerospace, telecommunications, and consumer electronics. Vacuum deposition technology enables the production of high-performance coatings that are crucial for the advancement of solar power and optics technologies.
Table of contents
12 chapters · 125 sections · 220 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Anti-reflective Coatings | Anti-reflective coatings |
| By Material | Silicon Dioxide | — |
| By Technology | Vacuum Deposition | Vacuum deposition |
| By Application | Consumer Electronics | Aerospace & defense |
By Type
- The anti-reflective coatings segment is expected to account for the largest share of over 37% of the global optical coatings market.
- This segment's large market share is attributed to the increasing utilization of AR coatings to enhance the durability and longevity of optical components and improve the contrast & clarity of images across various applications, including microscopy, photography, and display technologies.
- Additionally, by reducing surface reflections, AR coatings reduce ghosting (secondary images) and flare (unwanted bright spots).
- Moreover, the anti-reflective coatings segment is expected to register the highest CAGR during the forecast period.
By Material
- The Silicon Dioxide Segment to Dominate the Optical Coatings Market
- The silicon dioxide segment is expected to account for the largest share of the global optical coatings market.
- This segment's large market share is attributed to the increasing adoption of silicon dioxide for optical coatings to maintain high light transmission in lenses, filters, and mirrors and the growing use of silicon dioxide in both single-layer & multi-layer optical coatings to reduce surface reflections and improve light transmission.
- Furthermore, silicon dioxide enhances the mechanical strength of optical coatings, extending the lifespan of optical components.
By Technology
- The vacuum deposition segment is expected to account for the largest share of over 40% of the global optical coatings market.
- The segment's large market share is attributed to the increasing usage of vacuum deposition in optical coating processes.
- This technology enables precise control over layer thickness & composition during the optical coating process, which is crucial to ensure the consistent optical performance of lenses, mirrors, and electronic displays.
- Additionally, vacuum deposition facilitates low dispersion, high transmission efficiency, and minimal absorption in optical coatings, which contributes to their widespread adoption across various applications.
- These include anti-reflective coatings, reflective coatings, beam splitters, and optical filters.
- Moreover, the vacuum deposition segment is expected to register the highest CAGR during the forecast period.
By Application
- The consumer electronics segment is expected to account for the largest share of over 41% of the global optical coatings market.
- This segment's large market share is attributed to the increased use of optical coatings in consumer electronics to improve device performance and usability.
- Additionally, the application of optical coatings in consumer electronics significantly improves user experience by enhancing the visibility, durability, and functionality of screens.
- However, the aerospace & defense segment is expected to register the highest CAGR during the forecast period.
- This segment’s growth is attributed to the increasing adoption of optical coatings in aerospace components and defense equipment.
- These coatings are widely used in night vision devices and precision targeting & guidance systems to protect against moisture, dust, abrasion, and other environmental factors.
- Moreover, optical coatings are widely utilized in the aerospace & defense sector to enhance the performance, safety, and efficiency of aircraft, satellites, and military equipment.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of over 38% of the global optical coatings market. North America’s large market share can be attributed to the proliferation of manufacturing hubs for mid-scale and small-scale medical equipment, the presence of major companies specializing in instrumentation, microelectronics, biotechnology, and software development, and the rising demand for optical coatings, driven by the increasing use of reflective coatings in green buildings to retain heat and reduce energy consumption. In 2025, North America to Dominate the Optical Coatings Market
Asia-Pacific
Fastest growthHowever, the market in Asia-Pacific is expected to register the highest CAGR of over 9.5% during the forecast period. The growth of this regional market is driven by the increasing demand for optical coatings across numerous industries, including automotive, healthcare, and electronics. Furthermore, the rising demand for optical coatings in the automotive sector to enhance safety features is further propelling the market’s growth in this region.
Competitive landscape
- September 2024
PPG Industries, Inc. (U.S.) signed an agreement with Flo-optics (Israel), a developer of digital manufacturing technology for the ophthalmic industry, to apply PPG HI-GARD scratch-resistant coatings using Flō’s patented digital printing technology. This agreement will enable the first-ever digitized lens coating solutions using additive manufacturing (AM), also known as 3D printing technology.
- September 2024
HOYA Vision Care Europe Hoya Holdings N.V. (Austria) launched the Super HiVision Meiryo EX4—an anti-reflective (AR) lens coating technology treatment. The Super HiVision Meiryo EX4 is the latest AR technology in HOYA’s AR treatments (which include the SuperHiVision EX3 and Super High Vision EX3+). The treatment offers exceptional scratch resistance, being 2.5 times more durable than standard coatings. It also provides long-term cleanability and offers UV protection.
- DuPont de Nemours, Inc. (U.S.)
- Carl Zeiss AG · Germany
- Nippon Sheet Glass Co., Ltd. · Japan
- Inrad Optics, Inc. (U.S.)
- PPG Industries, Inc. (U.S.)
- Coherent Corp. (U.S.)
- Materion Corporation (U.S.)
- Reynard Corporation (U.S.)
- Chroma Technology Corp. (U.S.)
- Cascade Optical Corporation (U.S.)
- Abrisa Technologies (U.S.)
- Surface Optics Corporation (U.S.)
- Optimax Systems, Inc. (U.S.)
Frequently asked questions
This study focuses on market assessment and opportunity analysis by analyzing the sales of optical coatings across various regions and countries. This study also offers a competitive analysis of the optical coatings market based on an extensive assessment of the leading players' product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2024). Optical Coatings Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRCHM - 1041272). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/optical-coatings-market-5955