Neo and Challenger Bank Market (2025-2035)
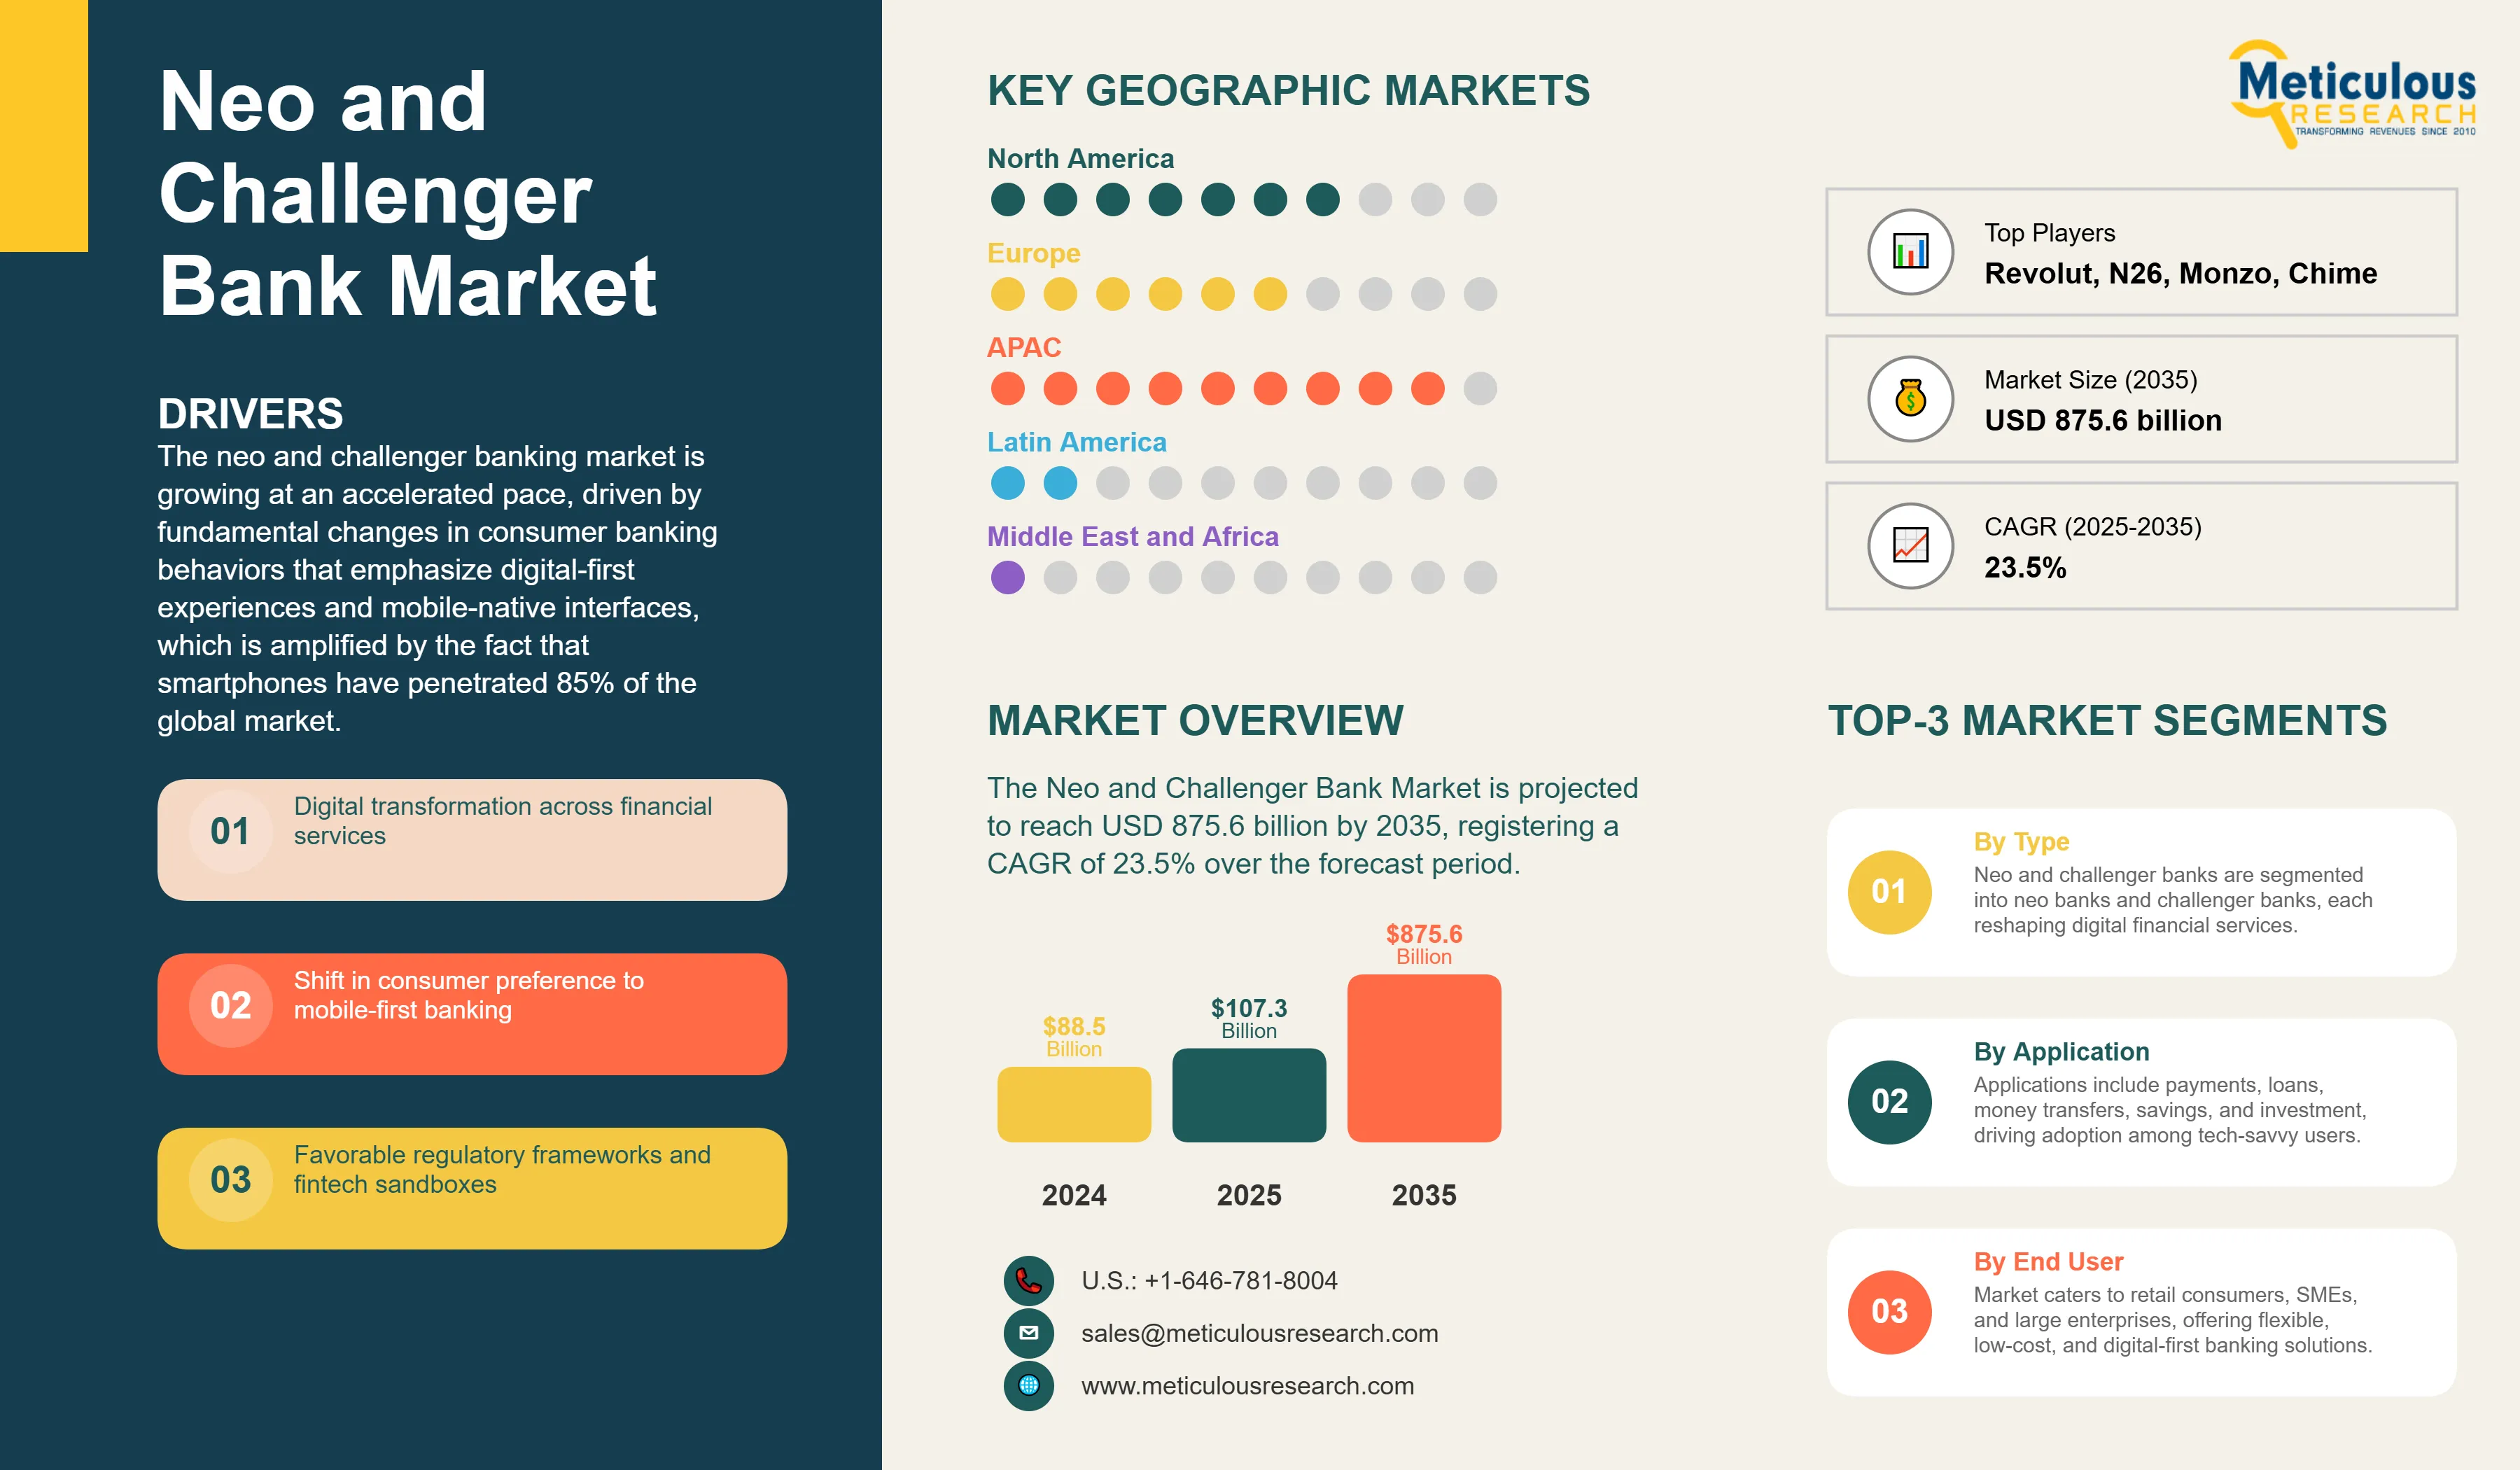
The Neo and Challenger Bank Market was worth USD 88.5 billion in 2024. The market is estimated to be valued at USD 107.3 billion in 2025 and is projected to reach USD 875.6 billion by 2035, registering a CAGR of 23.5% over the forecast period.
- Published
- Aug 2025
- Pages
- 230
- Format
- PDF + Excel
- Report ID
- MRICT - 1041565
- Base year
- 2024
- 2024 · BASELINE
- $88.50B
- 2035
- $875.6B
- CAGR 2025–2035
- 23.5%
2024 baseline · 2025–2035 forecast at 23.5% CAGR · hover a bar for the value
Key highlights
China's Super-App Ecosystem Drives 28.3% CAGR Leadership (2025-2035)
India's Digital India Initiative Propels Neo and Challenger Bank Market at a CAGR of 27.8% from 2025 to 2035
U.S. Neo Banks Capture 18.2% Growth Through Innovation and Venture Funding
Report summary
| Particulars | Details |
|---|---|
| Metric | Value |
| Market Value (2025) | USD 107.3 billion |
| Market Value (2035) | USD 875.6 billion |
| CAGR (2025-2035) | 23.5% |
| Format | PDF, Excel & Cloud Portal · 230 pages |
| Largest Business Model | Digital-only Banks (65-70% share) |
| Fastest Growing Service | Embedded Finance & BaaS (25.3% CAGR) |
| Leading Service Category | Payments & Money Transfers (30-40% share) |
| Dominant End-User | Retail Consumers (70-75% share) |
| Fastest Growth Region | Asia-Pacific (26.4% CAGR) |
| Top Country by Users | China |
| Market Concentration | Top 10 players hold 30-40% share |
Report overview
The neo and challenger banking market is growing at an accelerated pace, driven by fundamental changes in consumer banking behaviors that emphasize digital-first experiences and mobile-native interfaces, which is amplified by the fact that smartphones have penetrated 85% of the global market. 78% of millennials and 67% of Gen Z prefer mobile banking to an actual storefront bank visit, creating a multi-trillion-dollar addressable market for digital-only banking services.
The growth of the neo and challenger banks is also propelled by regulatory support, such as open-banking mandates like PSD2 in Europe and similar controls in Asia-Pacific, which have established API-driven ecosystems and tripled fintech-bank partnerships since 2021. Neo banks operate at 60-70% lower costs than traditional banks, allowing them to offer fee-free accounts, a higher savings rate, and instant account offerings and services that appeal to price-sensitive and digitally literate customers.
The COVID-19 pandemic created lasting changes in banking behavior, with digital account openings increasing 200% during the years of 2020-2024, while 40% of traditional bank branches closed globally. Technology innovations, such as AI-based personalization, real-time payments, and embedded finance capabilities, allow neo banks to better serve their clients and provide a superior customer experience, allowing clients 24/7 access and account opening processes of less than a minute. Neo banks' progress towards providing a comprehensive financial products and services ecosystem will advance growth in the market by expansion into underserved markets, small, medium and enterprise (SME) banking services and Banking-as-a-Service platforms. Neo banks are evolving away from simple payment applications to a comprehensive financial ecosystem.
Digital-only banks make up 65-70% of the overall neo and challenger market based on business model, and they have the ability to provide complete banking services, without physical branches, through the use of mobile and web applications. Digital banks have operational costs at least 60-70% lower than traditional banks with a cost-to-income ratio of between 35-40%, while traditional banks are roughly 55-65%. Low costs enable digital banks to provide competitively priced and often free products and services to cost-sensitive consumers.
Digital banks have improved customer experience (CX). The account opening is less than 5 minutes, they offer cards instantly, both virtual and physical, and provide real time notifications to keep consumers informed and alerts for fraud and budgetary constraints for example. They offer financial insights using AI that typically would take fully qualified human advisors to deliver. Unless traditional incumbents work fast, they will continue to lose market share to digital-only banks.
Market leaders like Revolut serve over 60 million customers globally as of 2025, while Chime has serviced around 12 million accounts in the US by offering features such as early paycheck access, zero-fee overdrafts, and automated savings, which resonate strongly with financially stressed consumers.
As regulatory frameworks mature and consumers become more accustomed to trusting digital-only banking (one study found that 65% rated their neo bank experience better than a traditional bank), this segment will continue to lead the market growth in terms of new products & geo expansion.
Based on services, payments and money transfers hold the largest share of the overall neo and challenger bank market with a 35%-40% revenue share in 2025, being the most commonly used services and the primary engagement channel for acquisition and retention. Neo banks process over 10 billion transactions annually, and average transaction volumes increased by 45% YOY. Everyday spend has shifted for millions of users to digital platforms, including the introduction of real-time payments, split bills, and instant peer-to-peer transfers.
The neo and challenger bank market is on the rise, with an expanding landscape due to digital transformation in financial services, a shift towards mobile-first banking preferences, supportive regulatory frameworks, and technological advancements that improve customer experiences. Moreover, the advantages of lower costs, financial inclusion efforts, and ecosystem partnerships enhance competitive advantage.
Neo and challenger banks market is experiencing significant growth as digital transformation is transforming the way financial services are delivered and consumed. Digital banking has emerged as part of the massive digital transformation taking place in many sectors. With 85% of the world utilizing smartphones and 5 billion mobile internet users, neo banks are taking advantage of the shift to a mobile-first banking experience, particularly among millennials and Gen Z who approximately execute 89% of their banking activity through mobile apps. Digital natives require speed and seamless service, which traditional banks aren't able to provide due to legacy systems and branches.
Neo banks operate with modern technology stacks, mainly built on microservices, that allow them to bring new features to life in days versus months, with continuous deployment practice that allows for 50+ updates a week compared to quarterly changes at traditional financial institutions. The experiences these digital banks provide, through easy-to-use designs, personalized insights, and gamification, yield 4.8 stars as an average app store rating compared to 3.2 stars on traditional bank apps. These banks have decreased customer acquisition costs by 40% via viral referral programs and social marketing. For instance, Revolut is acquiring 2 million customers a month at USD 20 per user compared to traditional banks acquiring customers at USD 200/300 per user.
The pandemic accelerated digital adoption by 5-7 years, with branch visits declining 60% permanently while digital engagement increased 200%, creating an inflection point where digital-only banking became mainstream rather than niche. As 5G networks enable richer mobile experiences and younger demographics inherit USD 68 trillion in wealth transfers, neo banks are positioned to capture this generational shift toward fully digital financial lives.
Globally, regulatory frameworks are actively promoting competition and innovation in banking through open banking mandates, digital banking licenses, and fintech sandboxes that lower barriers to entry. The European Union's PSD2 directive, requiring banks to share customer data via APIs with consent, has enabled 500+ fintechs to launch innovative services, while similar frameworks in Australia, Singapore, and Brazil create global momentum for banking transformation. These regulations level the playing field, allowing neo banks to access customer data from incumbent banks and offer account aggregation, financial management, and switching services.
A digital banking license - which is currently offered in more than 40 countries - allows neo banks to offer banking functionalities (deposit-taking and lending) without the requirements of a bank branch, reducing the capital requirements for a new bank by 70%. A regulatory sandbox, such those offered in the UK, Singapore, and UAE, permits neo banks to trial novel products with real customers, and under loosened regulatory obligations, thereby shortening the time to market by 12-18 months. while standardizing APIs through open banking generates network effects so that for each additional participant in the ecosystem, the value for all ecosystem actors increases.
Government support for financial inclusion and competition have led to processes faster to license digital banks, sometimes referencing 2-3 years historically, but in recent years licensing has taken as little as 6-9 months. Given regulators believe neo banks can improve access and reduce systemic risk from diversified digital banks, regulators continue to enact policies that create access, including proportional regulation (risk profile, and/or activities, rather than institutions's type) that that will drive competition in the market.
The neo and challenger bank market is estimated to grow globally at a CAGR of 23.5% during 2025-2035, with the Asia-Pacific region anticipated to see the fastest growth from a massive unbanked population and a mobile-first consumer base. The neo and challenger bank market across Asia-Pacific will be led by China at a CAGR of 28.3% driven by super app platforms that are integrating banking services such as WeChat by Tencent and Alipay by Ant Group which is enabling integrated online banking services for 1 billion users in China. India is next at a CAGR of 27.8% with 190 million adults are now banked for the first time with digital banking services over the last few years.
Report infographic
Market dynamics
9 factors across 1 forceDiversifying revenue streams
Premium subscriptions
Lending products
Regulatory compliance
Deposit insurance
Biometric authentication
Partnership models
White-label solutions
Compliance automation
Table of contents
13 chapters · 166 sections · 230 pages · click to expandGeographic analysis
Asia-Pacific
The neo banking sector in China experienced a growth from 20.8% CAGR in 2020-2024. This market is further expected to grow at a CAGR of 28.3% from 2025-2035 as technology firms such as Tencent and Alibaba integrate financial services into their ecosystems with billions of users. WeBank has used social and behavioral data to score customers for AI-enforced micro-loans, making about USD 1,500 on average and serving 320 million users; this resulted in default rates of <1.5%. MYbank leverages automated decisioning and processes 5 million loans a day for SMEs, providing an approval decision in 3 seconds, 0% human. Banking's place within super-app ecosystems creates an engagement like never before; WeChat users use their banking services 15 times daily, getting paid on the app, shopping, and performing banking services like paying at restaurants. Government support with the digital yuan product and policies that focus on financial inclusion has perpetuated the penetration of digital banking; the government is looking for 95% penetration by 2030! India's neo banking market is expected to flourish from 2025 to 2035, with a CAGR of 27.8%, largely attributed to government-led digitization initiatives and a growing user base of 650 million smartphone users looking for easy access to financial services. The JAM trinity (Jan Dhan accounts, Aadhaar identification, and Mobile connected) has established digital foundations that enabled fast KYC and onboarding of over 400 million erstwhile unbanked citizens. Neo banks such as Paytm Payments Bank brought 60 million users onto their platform while Jupiter and Fi are targeting richer millennials looking for custom wealth management services. RBI's digital banking licenses and ubiquity of the UPI payment rails that process over 10 billion transactions every month, provide a ready basis for growth for neo banks. The roadmap for a USD 5 trillion economy by the year 2030 may require financial inclusion and neo banks are positioned to provide easy access to credit through new and alternative underwriting aspects. China's Super-App Ecosystem Drives 28.3% CAGR Leadership (2025-2035) India's Digital India Initiative Propels Neo and Challenger Bank Market at a CAGR of 27.8% from 2025 to 2035
North America
The U.S. neo banking market is projected to grow at a CAGR of 19.2% from 2025 to 2035. This is powered by USD 5 billion annually in venture investments and consumer dissatisfaction, with 50 million Americans currently dissatisfied with the current bank services and fees. In addition to 12 million customers, Chime saves customers up to USD 500 a year in no-fee accounts and early direct deposit, while Varo Bank has a national charter that offers full-stack banking featuring USD 1 billion in loan origination. While the CFPB continues to work on an open banking framework, state-level charters for fintech help to lower regulatory barriers to market, which helps neo banks scale. Community banks and neo banks can leverage partner models to attract and retain customers while pushing the envelope on innovation, achieving compliance, and providing FDIC insurance. Neo banks meet the needs created by the student debt crisis and growing wealth inequality in the U.S. by offering more accessible financial services through lower costs and less discriminatory underwriting. U.S. Neo Banks Capture 18.2% Growth Through Innovation and Venture Funding
Competitive landscape
The neo and challenger banks market features intense competition between pure-play digital banks, licensed challengers, and digital subsidiaries of incumbents, where differentiation is made based on user experience, product innovation and expansion into new geographies. Leading players like Revolut (more than 60 million users), Nubank (around 70 million users) and Chime (12-15 million users) have achieved scale with some aggressive growth plans and have raised billions in venture funding at unicorn valuations of around USD 10 billion and up.
Mergers and acquisitions (M&A) activity continues to accelerate due to revenue pressures from profitability and funding challenges. At least 25+ acquisitions will take place in 2024. Current acquired Till Financial and Monzo merged with ClearScore. Geographic expansion is still a significant growth strategy. European neo banks are entering the U.S. market, while Asian super-apps are expanding their financial services offerings, and incumbent banks are acquiring/pursuing neo banks to accelerate their transformational journey to digitalization rather than building those capabilities in-house.
- 2024
Nubank expanded its Latin American footprint by launching operations in Mexico and Colombia through acquisitions and organic growth, now serving approximately five countries in the region, including Brazil, Mexico, Colombia, Argentina, and Peru.
- Late 2024
Chime filed confidentially for an IPO targeting a valuation in the range of USD 34-40 billion, which would make it one of the largest fintech public offerings since 2021.
Frequently asked questions
The global neo and challenger bank market is estimated to be valued at USD 107.3 billion in 2025.
Cite this report
Meticulous Research. (2025). Neo and Challenger Bank Market - Global Opportunity Analysis And Industry Forecast (2025-2035) (Report No. MRICT - 1041565). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/neo-and-challenger-bank-market-6248