Medical Consumables Market (2026-2036)
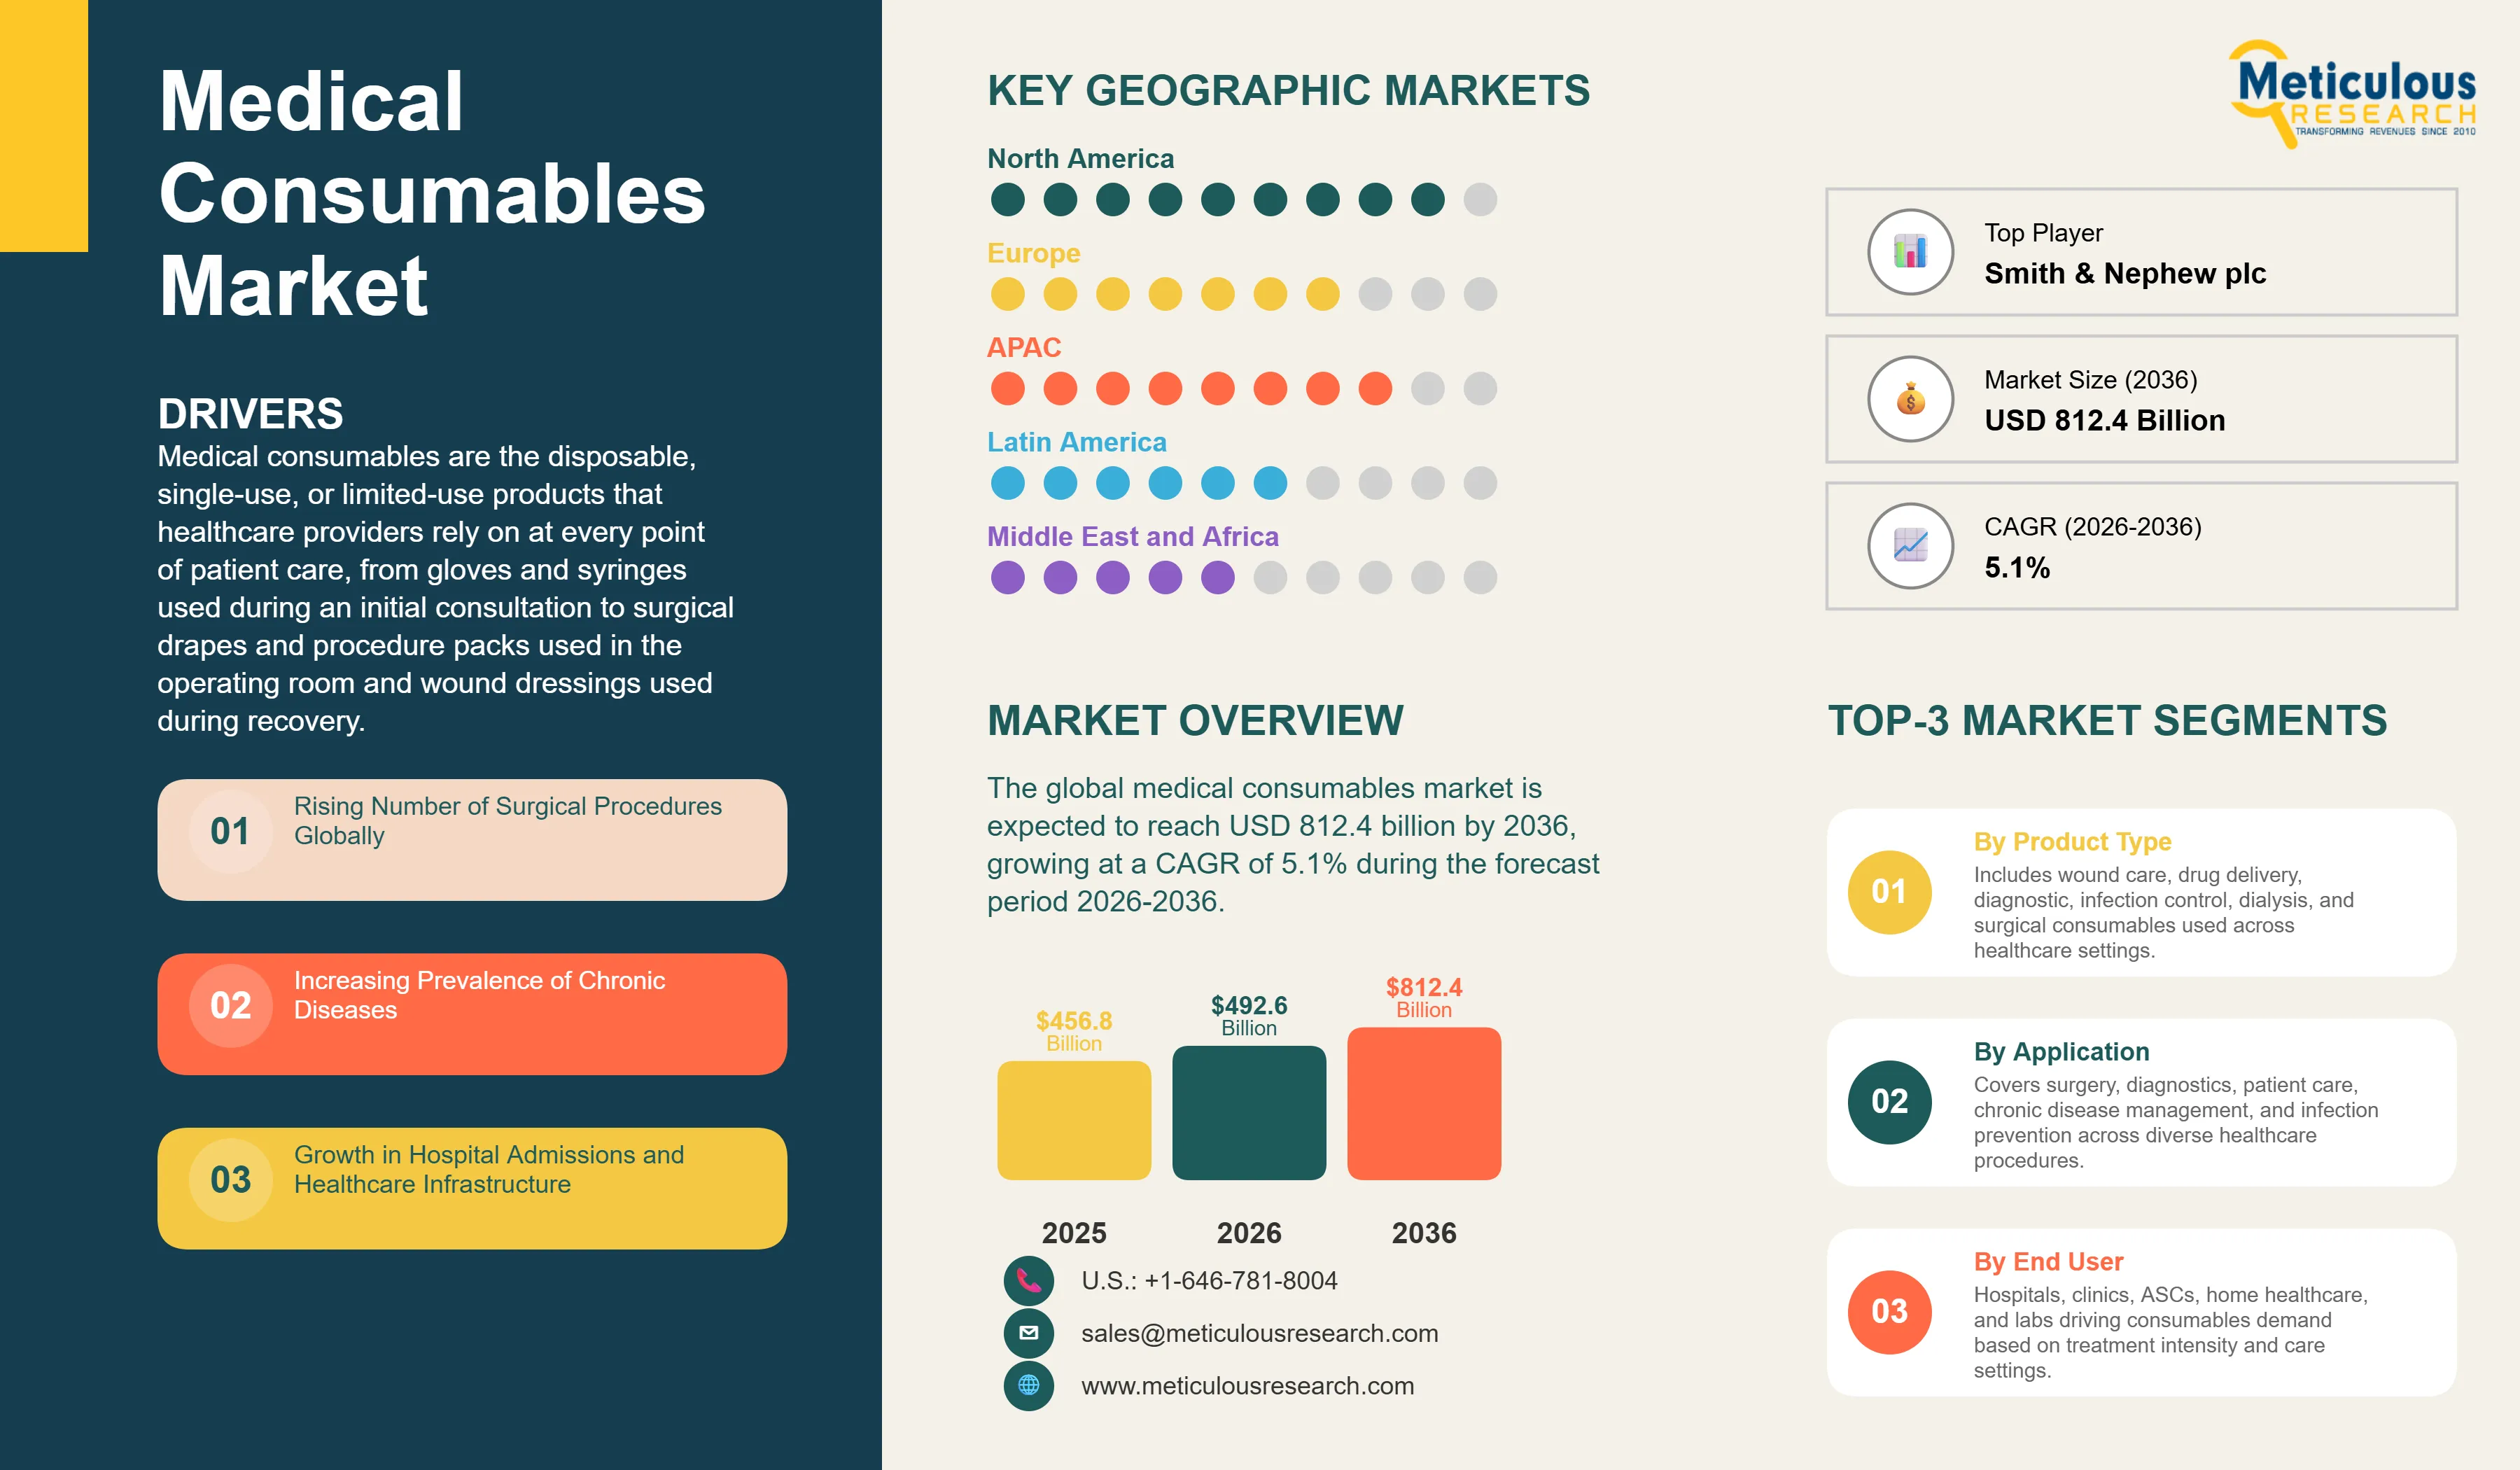
The global medical consumables market was valued at USD 456.8 billion in 2025. This market is expected to reach USD 812.4 billion by 2036 from an estimated USD 492.6 billion in 2026, growing at a CAGR of 5.1% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 280
- Format
- PDF + Excel
- Report ID
- MRHC - 1041944
- Base year
- 2025
- 2025 · BASELINE
- $456.8B
- 2036
- $812.4B
- CAGR 2026–2036
- 5.1%
2025 baseline · 2026–2036 forecast at 5.1% CAGR · hover a bar for the value
Key highlights
The global medical consumables market is projected to reach USD 812.4 billion by 2036.
The market is expected to grow at a CAGR of 5.1% during the forecast period 2026-2036.
The global market for medical consumables was valued at USD 456.8 billion in 2025 and is estimated to reach USD 492.6 billion in 2026.
North America is expected to dominate the global medical consumables market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By product type, the infection control consumables segment is expected to hold the largest share of the market in 2026, while the diagnostic consumables segment is projected to register the highest CAGR during the forecast period.
By application, the surgery segment is expected to hold the largest share in 2026, while the chronic disease management segment is projected to register the highest CAGR during the forecast period.
By end user, the hospitals segment is expected to hold the largest share in 2026, while the home healthcare segment is projected to register the highest CAGR during the forecast period.
By distribution channel, the distributors and wholesalers segment is expected to hold the largest share in 2026, while the online channels segment is projected to register the highest CAGR during the forecast period.
By material type, the plastics and polymers segment is expected to hold the largest share in 2026, while the nonwoven materials segment is projected to register the highest CAGR during the forecast period.
By sterilization type, the pre-sterilized consumables segment is expected to hold the largest share in 2026, while the non-sterilized consumables segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 812.4 Billion |
| Market Size in 2026 | USD 492.6 Billion |
| Market Size in 2025 | USD 456.8 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 5.1% |
| Format | PDF, Excel & Cloud Portal · 280 pages |
| Dominating Product Type | Infection Control Consumables |
| Fastest Growing Product Type | Diagnostic Consumables |
| Dominating Application | Surgery |
| Fastest Growing Application | Chronic Disease Management |
| Dominating End User | Hospitals |
| Fastest Growing End User | Home Healthcare |
| Dominating Distribution Channel | Distributors and Wholesalers |
| Fastest Growing Distribution Channel | Online Channels |
| Dominating Material Type | Plastics and Polymers |
| Fastest Growing Material Type | Nonwoven Materials |
| Dominating Sterilization Type | Pre-Sterilized Consumables |
| Fastest Growing Sterilization Type | Non-Sterilized Consumables |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: product type, application, end user, distribution channel.
According to the World Health Organization, over 313 million surgical procedures are performed globally every year, each requiring a defined set of sterile single-use consumables, making surgical volume one of the most reliable and measurable demand indicators for this market.
Medical consumables are the disposable, single-use, or limited-use products that healthcare providers rely on at every point of patient care, from gloves and syringes used during an initial consultation to surgical drapes and procedure packs used in the operating room and wound dressings used during recovery. These products are replaced after each patient contact to prevent cross-infection and maintain the sterile conditions that modern medicine requires. According to Becton Dickinson, one of the world's largest medical device companies, approximately 16 billion injections are administered globally each year using disposable syringes and needles, a single product subcategory that illustrates the extraordinary scale of recurring demand in this market.
The market is growing because healthcare utilization is increasing across every major indicator. According to the World Health Organization, global surgical volumes are growing at approximately 5% annually in developing countries as healthcare infrastructure expands. The International Diabetes Federation reported in 2023 that 537 million adults globally are living with diabetes, a number projected to reach 783 million by 2045, with each patient requiring daily or weekly consumables for blood glucose monitoring, insulin delivery, and related care. The Global Kidney Health Atlas published by the International Society of Nephrology estimates that over 850 million people worldwide have some form of kidney disease, with approximately 3.5 million requiring regular dialysis that consumes significant volumes of dialysis-specific consumables per session. These chronic disease populations are growing every year, creating an ever-expanding baseline of recurring consumables demand that does not diminish between economic cycles.
Two key opportunities are reshaping the market's trajectory. Home healthcare is the fastest-growing care setting globally, with the American Hospital Association projecting that home-based care will account for a growing share of total healthcare delivery as payers and patients alike seek alternatives to costly hospital stays. This shift is driving demand for consumables specifically designed for patient self-administration including prefilled syringes, easy-to-use wound care kits, and continuous glucose monitoring supplies. In parallel, the healthcare industry's sustainability agenda is creating commercial pull for biodegradable and plant-based polymer consumables, with major hospital groups in Europe and North America issuing procurement sustainability requirements that are beginning to reshape material specifications across the supply chain.
Report infographic
Market dynamics
7 factors across 3 forcesRising Number of Surgical Procedures Globally
According to the Lancet Commission on Global Surgery, approximately 313 million surgical procedures are performed worldwide each year, but the commission also estimates that at least 143 million additional procedures are needed annually to address unmet surgical need in low and middle-income countries. As healthcare infrastructure expands in these markets, the gap between current and needed surgical volumes will progressively narrow, driving significant increases in surgical consumables demand. In developed markets, the aging of populations is driving growing volumes of elective procedures including joint replacements, cataract surgeries, and cardiac procedures. According to the American Joint Replacement Registry, total hip and knee replacement procedures in the U.S. alone exceeded 1 million in 2022 and are projected to grow substantially through 2030 as the baby boomer generation ages into the peak age for these procedures. Each procedure consumes a substantial kit of single-use surgical consumables including drapes, gowns, prep kits, sutures, staples, and instrument covers.
Increasing Prevalence of Chronic Diseases
According to the International Diabetes Federation's Diabetes Atlas 2023, 537 million adults aged 20 to 79 years are currently living with diabetes, representing 10.5% of the adult population globally, and this number is expected to rise to 783 million by 2045. Each person with diabetes who uses insulin requires syringes, pen needles, or insulin pump infusion sets on a daily basis, and those who monitor their blood glucose require test strips or continuous glucose monitoring sensors on an ongoing basis. According to the World Health Organization's 2023 data, cardiovascular diseases remain the number one cause of death globally, accounting for approximately 17.9 million deaths per year, and the large patient population with cardiovascular disease consumes significant volumes of catheters, IV consumables, and monitoring consumables during hospitalization and ongoing care. The growing global chronic disease burden creates a permanent, recurring, and growing demand for consumables that persists throughout each patient's disease management journey.
Table of contents
14 chapters · 192 sections · 280 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Infection Control Consumables | Diagnostic consumables |
| By Application | Surgery | Chronic disease management |
| By End User | Hospitals | Home healthcare |
By Product Type
- Infection Control Consumables to Dominate
- The infection control consumables segment is expected to account for the largest share of the global medical consumables market.
- Gloves, masks, gowns, and disinfectants are used in every clinical encounter across every healthcare setting globally, generating the highest aggregate consumption volumes of any consumables category.
- According to the World Health Organization's hand hygiene guidelines, healthcare workers are recommended to perform hand hygiene procedures up to 100 times per 12-hour shift in high-risk settings, and gloves are integral to many of these interactions.
- The sheer frequency and universality of infection control consumables use makes this the largest segment by volume and by revenue.
- However, the diagnostic consumables segment is projected to register the highest CAGR during the forecast period.
- The expansion of molecular diagnostics, point-of-care testing, and direct-to-consumer testing is driving very rapid growth in test strips, sample collection kits, and reagent volumes.
- According to the In Vitro Diagnostics Association, the global IVD market is growing at approximately 5 to 6% annually, and diagnostic consumables represent the recurring revenue stream that supports this growth, as every diagnostic test consumes a defined quantity of single-use consumables regardless of the platform used.
By Application
- Surgery to Hold the Largest Share
- The surgery segment is expected to account for the largest share of the global medical consumables market.
- Surgical procedures are the highest-intensity consumers of single-use medical consumables, with a single complex surgical case consuming drapes, gowns, gloves, sutures, staples, surgical tapes, procedure packs, and numerous specialized consumables that together can represent several hundred dollars in consumables cost per procedure.
- According to the American College of Surgeons, hospital supply costs including consumables account for approximately 30 to 40% of total surgery costs, making surgical consumable spend a major component of hospital operating expenses and a large and stable demand segment.
- However, the chronic disease management segment is projected to register the highest CAGR during the forecast period.
- The International Diabetes Federation's projection of 783 million people with diabetes by 2045, combined with the growing kidney disease patient population requiring dialysis, creates a very large and rapidly expanding recurring consumables demand base in this segment.
- Unlike surgical consumables that are consumed in discrete procedure episodes, chronic disease consumables generate daily or weekly recurring demand per patient across multi-year or lifetime disease management periods, making this an exceptionally durable and predictable growth segment.
By End User
- Hospitals to Hold the Largest Share
- The hospitals segment is expected to account for the largest share of the global medical consumables market.
- Hospitals are the most intensive users of medical consumables per facility, combining inpatient care, surgical suites, emergency departments, intensive care units, and diagnostic laboratories under one roof, each generating significant consumables consumption.
- According to the American Hospital Association, U.S. hospitals alone spent over USD 250 billion on supplies and services in 2022, with medical consumables representing a large share of this total.
- The global hospital sector, which includes over 140,000 hospitals worldwide according to WHO estimates, is the largest and most concentrated procurement channel in the market.
- However, the home healthcare segment is projected to register the highest CAGR during the forecast period.
- The shift of care toward home settings, driven by the aging of populations, the preference of patients for home-based care, and payer pressure to reduce expensive hospitalization, is generating rapid growth in home-specific consumables from a smaller current base.
- The U.S. home health market is expected to grow at above-average rates through the forecast period according to the Centers for Medicare and Medicaid Services, driving corresponding growth in home healthcare consumables procurement.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global medical consumables market, led by the United States, which remains the world’s largest market for medical consumables. The U.S. continues to record the highest per-capita healthcare expenditure globally, exceeding $13,000 per capita in 2024, according to the Centers for Medicare & Medicaid Services, reflecting a highly intensive healthcare system with strong and recurring demand for consumables. The country is also home to leading medical device and consumables companies such as Becton Dickinson, Cardinal Health, Baxter International, and Medtronic, all of which generate significant revenues from consumables portfolios.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific medical consumables market is expected to grow at the fastest CAGR during the forecast period. According to the World Health Organization, the Asia-Pacific region accounts for nearly 60% of the global population and is witnessing rapid growth in healthcare utilization, driven by rising incomes, urbanization, and expanding healthcare infrastructure. In China, ongoing healthcare reforms continue to strengthen access and capacity; data from the National Health Commission of China indicates that the number of hospital beds exceeded 9.8 million by 2023, reflecting sustained infrastructure expansion and continuous demand for consumables. In India, the Ayushman Bharat program remains a key growth driver, covering over 550 million beneficiaries as of 2024, according to the National Health Authority of India, significantly increasing hospitalization rates and demand for medical consumables. Furthermore, the International Diabetes Federation (IDF Atlas 2024) estimates that China and India remain the two largest diabetes populations globally, with approximately 148 million and 89 million adults respectively, creating a substantial and recurring demand for diabetes-related consumables such as test strips and insulin delivery devices. Japan also contributes significantly to regional demand due to its rapidly aging population; according to the Statistics Bureau of Japan, nearly 30% of the population is aged 65 years and above as of 2024, resulting in high per capita healthcare utilization and sustained consumption of medical supplies.
Europe
Europe is a large and well-established medical consumables market with high per-capita consumption, sophisticated procurement standards, and strong regulatory frameworks that ensure product quality and safety. Germany, France, the UK, and Italy are the largest European markets, each with universal or near-universal health insurance coverage that ensures broad access to hospital care and the associated consumables demand. The European medical device regulation that came into full effect in 2021 has significantly raised the clinical evidence and post-market surveillance requirements for medical consumables, increasing compliance costs but also raising quality standards.
Latin America
Latin America and the Middle East and Africa are earlier-stage but growing markets, with Brazil's large and growing healthcare sector, Saudi Arabia and UAE's healthcare infrastructure investment under Vision 2030, and South Africa's expanding private healthcare sector all contributing to growing regional consumables demand.
Competitive landscape
- Medtronic plc · Ireland
- Becton Dickinson and Company (U.S.)
- Cardinal Health Inc. (U.S.)
- 3M Company (U.S.)
- Baxter International Inc. (U.S.)
- B. Braun Melsungen AG · Germany
- Johnson & Johnson/Ethicon (U.S.)
- Fresenius Medical Care AG & Co. KGaA · Germany
- Smith & Nephew plc (UK)
- Boston Scientific Corporation (U.S.)
- Owens & Minor Inc. (U.S.)
- Terumo Corporation · Japan
- Halyard Health/Owens & Minor (U.S.)
- Molnlycke Health Care AB · Sweden
- Ansell Limited · Australia
Frequently asked questions
The global medical consumables market is expected to reach USD 812.4 billion by 2036 from an estimated USD 492.6 billion in 2026, at a CAGR of 5.1% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Medical Consumables Market - Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1041944). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/medical-consumables-market-6627