India VNA and PACS Market (2024-2031)
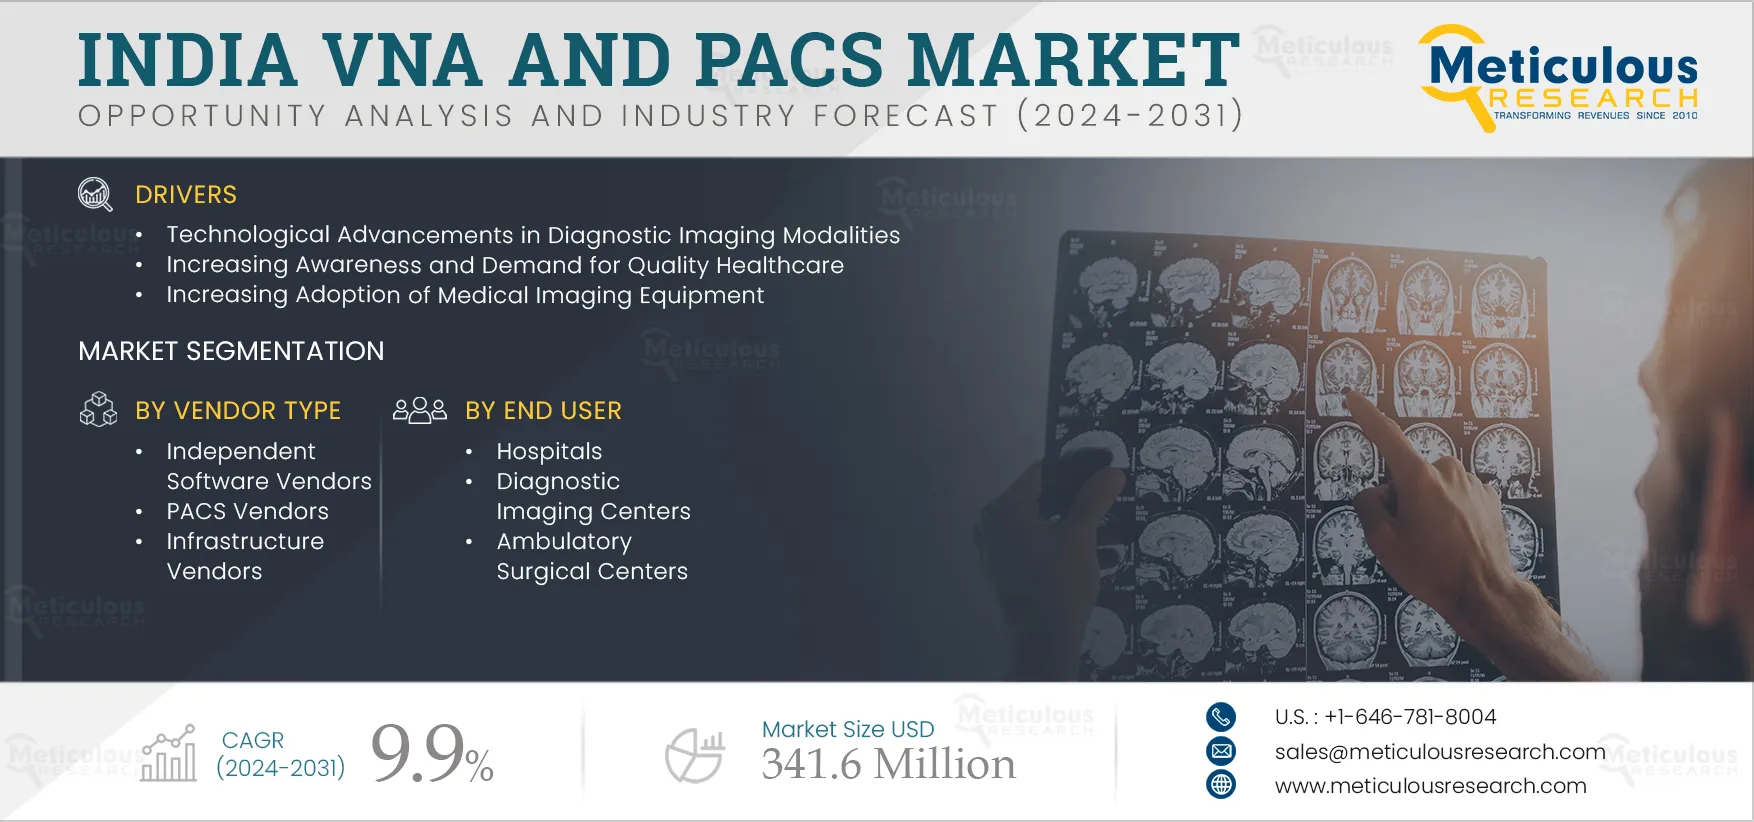
The India VNA and PACS Market was valued at $160.8 million in 2023. It is expected to reach $341.6 million by 2031 from an estimated $176.5 million in 2024, at a CAGR of 9.9% during the forecast period from 2024 to 2031. India VNA and PACS Market Size & Forecast The growth of this market can be attributed
- Published
- Sep 2024
- Pages
- 220
- Format
- PDF + Excel
- Report ID
- MRHC - 104260
- Base year
- 2024
- 2023 · HISTORICAL
- $160.8M
- 2031
- $341.6M
- CAGR 2024–2031
- 9.9%
2023 baseline · 2024–2031 forecast at 9.9% CAGR · hover a bar for the value
Key highlights
The Picture Archive Communication Systems (PACS) Segment to Dominate the India VNA and PACS Market in 2024
The Departmental PACS Segment to Dominate the India PACS Market in 2024
The On-premise Segment to Dominate the India PACS Market in 2024
The Enterprise VNA Segment to Dominate the India VNA Market in 2024
The On-Premise VNA Segment to Dominate the India VNA Market in 2024
The Computed Tomography (CT) Segment to Dominate the India VNA & PACS Market in 2024
The Independent Software Vendors Segment to Dominate the India VNA & PACS Market in 2024
The Hospitals Segment to Dominate the India VNA & PACS Market in 2024
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 220 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2024 |
| CAGR (Value) | 9.9% |
| Market Size (Value) | USD 341.6 million by 2031 |
| Segments Covered | India VNA & PACS Market Assessment, by Type · Picture Archive Communication Systems (PACS) · Vendor Neutral Archive (VNA) · India PACS Market Assessment, by Procurement Model · Departmental PACS · Radiology PACS · Cardiology PACS · Mammography PACS · Dental PACS · Other Departmental PACS · Enterprise PACS · (Note: Other departmental PACS include pathology, ophthalmology, and orthopedics PACS) · India PACS Market Assessment —by Delivery Mode · On-premise PACS · Web/Cloud-based PACS · India VNA Market Assessment—by Procurement Model · Enterprise VNA · Multi-departmental VNA · Multi-site VNA · Departmental VNA · India VNA Market Assessment—by Delivery Mode · On-premise VNA · Hybrid VNA · Web/Cloud-based VNA · India VNA & PACS Market Assessment—by Imaging Modality · Computed Tomography (CT) · X-ray & Angiography · Mammography · Magnetic Resonance Imaging (MRI) · Ultrasound · India VNA & PACS Market Assessment—by Vendor Type · Independent Software Vendors · PACS Vendors · Infrastructure Vendors · India VNA & PACS Market Assessment—by End User · Hospitals · Diagnostic Imaging Centers · Ambulatory Surgical Centers · Other End Users · (Note: Other end users include universities/education centers, government & non-government organizations, and academic research institutes.) |
| Key Companies | GE HealthCare Technologies Inc. (U.S.), Siemens Healthineers AG (Germany), Fujifilm Holdings Corporation (Japan), Agfa-Gevaert NV (Belgium), Carestream Health, Inc. (U.S.), Koninklijke Philips N.V. (Netherlands), Amrita Technologies (India), SoftTeam Solutions Pvt Ltd. (India), Medsynaptic Pvt. Ltd. (India), INFINITT Healthcare Co., Ltd. (South Korea), and Merative L.P. (U.S.). |
Report overview
Segments covered: procurement, imaging, delivery, vendor type.
The growth of this market can be attributed to several factors, including advancements in diagnostic imaging technologies, heightened awareness and demand for quality healthcare, increased adoption of medical imaging equipment, a rising need for a filmless environment, growing adoption of health IT and Electronic Health Records (EHR), and an expanding geriatric population. However, budget constraints and a shortage of skilled professionals may restrain the market’s growth.
In addition, the integration of artificial intelligence (AI) in medical imaging and the rapidly growing telehealth market are expected to generate growth opportunities for market stakeholders. However, inadequate infrastructure and high out-of-pocket expenses resulting from gaps in health insurance coverage are challenges that impede the market's growth.
Additionally, the rising adoption of cloud-based solutions and the emphasis on developing diagnostic imaging centers are prominent trends in the India VNA and PACS market.
Report infographic
Market dynamics
5 factors across 3 forcesTechnological Advancements in Diagnostic Imaging Modalities
The increasing demand for imaging services is driven by the need to enhance diagnosis and treatment while avoiding unnecessary surgical procedures. Imaging, once primarily a diagnostic tool, is now leveraged for the treatment, management, and prediction of various illnesses. It has become essential for a wide range of major medical conditions, including cancer, cardiovascular diseases, trauma, and neurological disorders.
Technological advancements in modalities such as MRI, PET, CT, and Ultrasound have significantly transformed modern healthcare. The integration of 3D and 4D technologies has further improved image quality, facilitating better diagnostics in radiology. In addition, advancements in automation, reproducibility, and portability have increased complexity and generated vast amounts of data, necessitating advanced solutions for effective data management.
Technological advancements like Digital Breast Tomosynthesis (DBT), or 3D mammography, have become the new standard in breast imaging due to their significant improvements in lesion visibility and early cancer detection. Additionally, the evolution of Digital Radiography (DR) has increasingly transitioned into mobile applications, allowing healthcare providers to conduct imaging exams anywhere by equipping digital X-ray systems on mobile carts. These advancements in imaging modalities are anticipated to drive the demand for efficient data storage solutions, such as PACS and VNA, in India.
Growing Digitalization in India
The IT revolution in India has significantly enhanced cellular coverage and wireless connectivity in urban and many rural areas, creating an ideal platform for the development of telehealth services and improving healthcare accessibility across the country. This growth in telehealth services enables faster turnaround times in outpatient departments and patient wards. However, these digital healthcare services require immediate access to a chronological series of archived images during patient follow-ups, necessitating robust archiving systems like PACS and VNA.
In December 2022, the Government of India launched the Digital India plan, aimed at transforming the country into a digitally empowered society and a knowledge-based economy through enhanced digital access, inclusion, and efforts to bridge the digital divide. This initiative focuses on three key areas: governance and on-demand services, digital infrastructure as a fundamental utility for all citizens, and empowering digital citizens. Ultimately, the goal is to ensure that digital technologies enhance the lives of all individuals, drive investment and job creation, expand India's digital economy, and develop digital skills across the nation.
As a result, the ongoing technological advancement and digitalization in the healthcare sector are expected to create significant growth opportunities for various digital healthcare technologies, including Electronic Health Records (EHR), Electronic Medical Records (EMR), PACS, and VNA. This will facilitate the effective management of medical images in healthcare organizations, thereby strengthening the PACS and VNA market in India.
Table of contents
15 chapters · 118 sections · 220 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | Picture Archive Communication Systems (PACS) | — |
| By Procurement Model | Departmental PACS | — |
| By Delivery Mode | On-premise | — |
| By Imaging Modality | Computed Tomography (CT) | — |
| By Vendor Type | Independent Software Vendors | — |
| By End User | Hospitals | — |
By Type
- The Picture Archive Communication Systems (PACS) segment is expected to account for the larger share of 79.2% of the India VNA and PACS market.
- The substantial market share of this segment is primarily driven by its widespread adoption in radiology, cardiology, and other departments, as it replaces traditional film-based methods for image retrieval, distribution, and display.
By Procurement Model
- The departmental PACS segment is expected to account for the largest share of the India PACS market.
- This segment's significant market share is primarily attributed to the growing adoption of PACS for processing large volumes of images.
- Radiology departments leverage these systems to address radiology-related challenges by digitizing traditional workflows, enhancing efficiency, ensuring data privacy and security, and improving image accessibility.
- Most PACS include built-in image viewing and annotation tools that facilitate accurate conclusions and treatment planning, further driving their widespread adoption.
- The Enterprise VNA Segment to Dominate the India VNA Market in 2024
- The enterprise VNA segment is expected to account for a larger share of the India VNA market.
- The substantial market share of this segment can be attributed to the growing need to aggregate data across multiple sites to enhance care coordination.
- The emergence of Integrated Delivery Networks (IDNs), Accountable Care Organizations (ACOs), and Health Information Exchanges (HIEs), along with rapid globalization and consolidation, further drives the demand for collaborative care and seamless access to shared data across healthcare settings.
- Additionally, the connection of multiple hospitals to central repositories and the mobility of patients between local hospitals and centers are expected to boost the growth of the multi-site VNA market.
By Delivery Mode
- The On-premise Segment to Dominate the India PACS Market in 2024
- The on-premise segment is expected to account for a larger share of the market.
- This segment's substantial market share is primarily attributed to the numerous advantages of on-premise PACS, including enhanced security, greater control over images, and lower latency compared to web/cloud-based PACS.
- These factors significantly contribute to the segment's dominance in the market.
- The On-Premise VNA Segment to Dominate the India VNA Market in 2024
- The on-premise VNA segment is expected to account for the largest share of 14.7% of the India VNA market.
- On-premise VNA enables a multi-vendor architecture that mitigates the risk of data breaches and external attacks.
- This model also allows buyers complete control over the timing of software upgrades, providing them the opportunity to test new features and train employees accordingly.
- Factors driving the growth of this segment include the ability to reuse existing servers and storage hardware, lower latency compared to cloud storage, and enhanced security and control over image data.
By Imaging Modality
- The Computed Tomography (CT) segment is expected to account for the largest share of the India VNA & PACS market.
- The substantial market share of this segment can be attributed to the increasing demand for imaging services and technological advancements in CT, which have significantly enhanced image resolution, quality, and diagnostic capabilities.
- These improvements have established CT scanning as an essential tool in medical imaging, leading to heightened demand for storage and management solutions such as VNA and PACS.
By Vendor Type
- The independent software vendors segment is expected to account for the largest share of 11.0% of the India VNA & PACS market.
- The substantial market share of this segment can be attributed to the growing number of hospitals, community centers, and diagnostic imaging centers turning to independent software vendors, such as Merge Healthcare (IBM), Dejarnette Research Systems, Hyland Software (Acuo), and TeraMedica (Fujifilm).
- These vendors are favored for their extensive experience and the superior functionality, scalability, integration, and support they offer for VNA solutions.
By End User
- The Hospitals Segment to Dominate the India VNA & PACS Market in 2024
- The hospitals segment is expected to account for the largest share of the India VNA & PACS market.
- The substantial market share of this segment can be attributed to the increase in patient visits and admissions, effective management of patient data, and initiatives aimed at implementing advanced technologies.
Competitive landscape
- November 2023
Koninklijke Philips N.V. (Netherlands) introduced Philips HealthSuite Imaging, a cloud-based PACS, alongside a Mobile MRI System for diagnostic readings. This launch also included AI tools designed to streamline clinical workflows and reduce turnaround times.
- August 2021
GE HealthCare Technologies Inc. (U.S.) launched Edison True PACS, an AI-enabled, cloud-based PACS designed to support radiologists in addressing high rates of employee burnout and retirement. This solution aims to enhance their effectiveness and accuracy while optimizing capital and IT resource management.
- GE HealthCare Technologies Inc. (U.S.)
- Siemens Healthineers AG · Germany
- Fujifilm Holdings Corporation · Japan
- Agfa-Gevaert NV · Belgium
- Carestream Health, Inc. (U.S.)
- Koninklijke Philips N.V. · Netherlands
- Amrita Technologies · India
- SoftTeam Solutions Pvt Ltd. · India
- Medsynaptic Pvt. Ltd. · India
- INFINITT Healthcare Co., Ltd. · South Korea
- Merative L.P. (U.S.)
Frequently asked questions
This study offers a detailed assessment of the India VNA and PACS market. It analyzes market sizes and forecasts based on procurement model, delivery mode, imaging modality, vendor type, and end user. It also involves the value analysis of various segments and subsegments of the VNA and PACS market at the regional and country levels.
Cite this report
Meticulous Research. (2024). India VNA and PACS Market - Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRHC - 104260). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/india-vna-and-pacs-market-4961