Europe IVD Market (2025-2032)
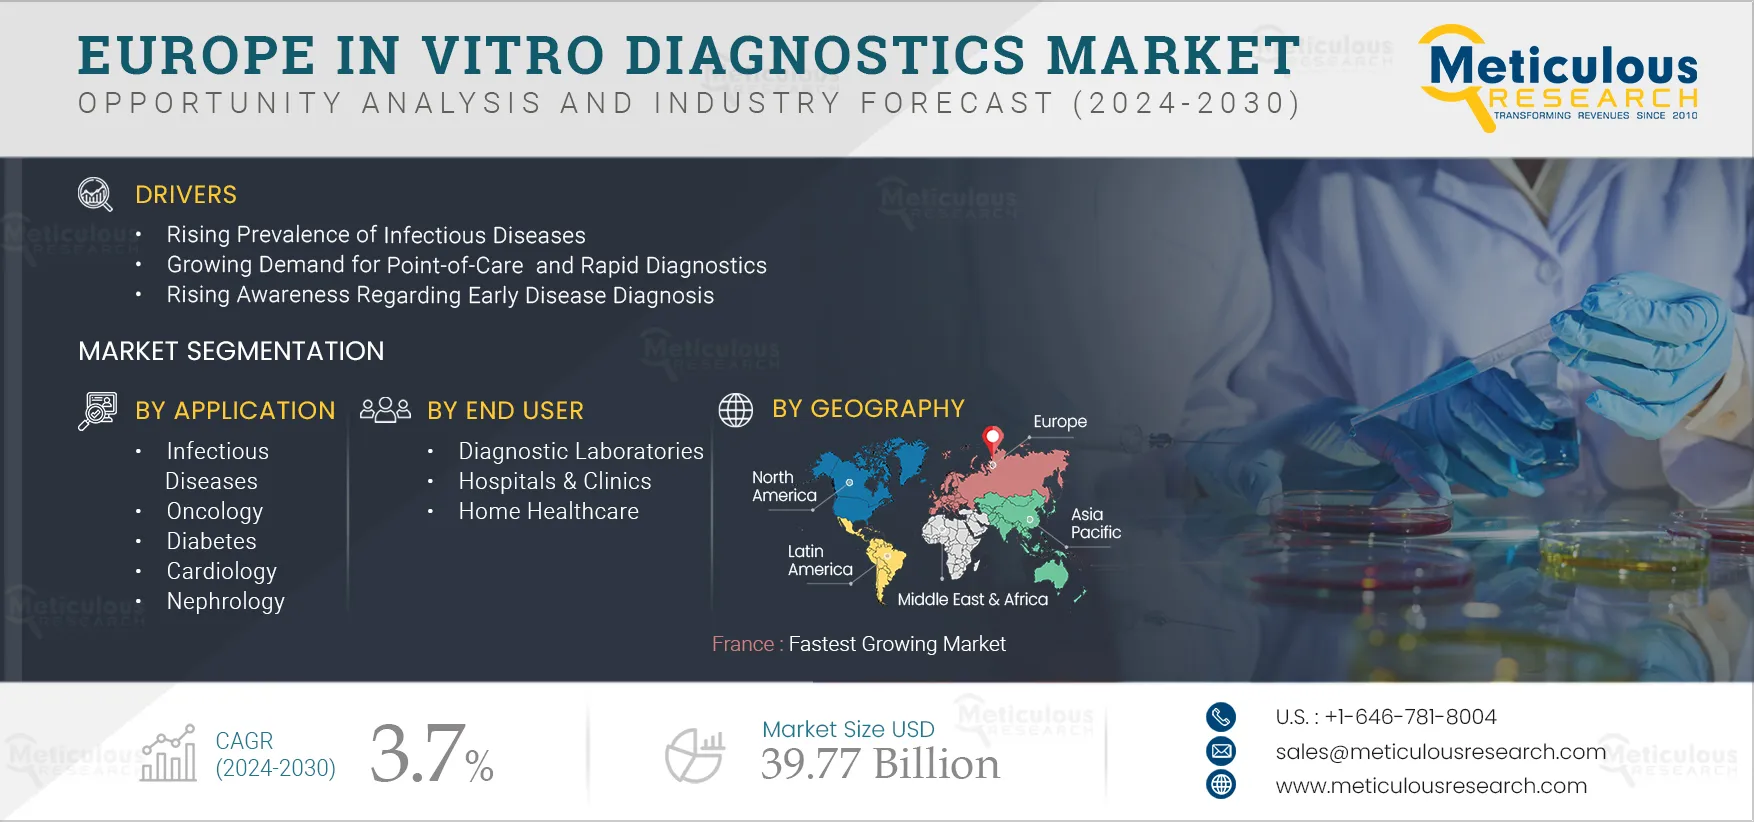
The Europe IVD Market is expected to reach $39.77 billion by 2032 at a CAGR of 3.7% from 2025 to 2032.
- Published
- Jan 2025
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRHC - 1041035
- Base year
- 2024
- 2032 · FORECAST
- $39.77B
- 2032
- $39.77B
- CAGR 2025–2032
- 3.7%
2024 baseline · 2025–2032 forecast at 3.7% CAGR · hover a bar for the value
Key highlights
In 2025, the Kits & Reagents Segment is Expected to Dominate this Market
In 2025, the Molecular Diagnostics Segment is Expected to Account for the Largest Share of the Market
The Cardiology Segment Is Projected to Register the Highest CAGR During the Forecast Period
In 2025, the Laboratory Testing Segment is Expected to Dominate this Market
The Hospitals & Clinics Segment Is Projected to Register the Highest CAGR During the Forecast Period
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2024 |
| Estimated Year | 2025 |
| Forecast Period | 2025–2032 |
| Market Size (2032) | USD 39.77 billion |
| CAGR (2025–2032) | 3.7% |
| Format | PDF, Excel & Cloud Portal · 250 pages |
| Segments Covered | By Offering: Kits & Reagents, Instruments, Software & Services · By Technology: Molecular Diagnostics Polymerase Chain Reaction (PCR), Hybridization, Isothermal Nucleic Acid Amplification Technology, DNA Sequencing & Next-generation Sequencing, Microarrays, Mass Spectrometry, Lateral Flow Assays/Rapid Tests, POC Molecular Diagnostics, Other PoC Products, Enzyme-linked Immunosorbent Assays (ELISA), Radioimmunoassays, Western Blotting, Enzyme-Linked Immunospot Assays, Immunohistochemistry (IHC) · By Application: Infectious Diseases COVID-19 Testing, Sexually Transmitted Diseases (STD) Testing, Healthcare-associated Infections (HAIs), Hepatitis, HIV, Tropical Diseases, Respiratory Infections (Excluding Influenza), Influenza · By Diagnostic Approach: Lab Testing, OTC/Self-testing, Point of Care Testing · By End User: Diagnostic Laboratories, Hospitals & Clinics, Home Healthcare, Other End Users |
| Countries Covered | Europe (Germany, U.K., France, Italy, Spain, Switzerland, Netherlands, Denmark, Rest of Europe) |
| Key Companies | Abbott Laboratories (U.S.), Becton, Dickinson and Company (U.S.), Bio-Rad Laboratories, Inc. (U.S.), Danaher Corporation (U.S.), F. Hoffmann-La Roche Ltd., Illumina, Inc. (U.S.), QIAGEN N.V., Shenzhen Mindray Bio-Medical Electronics Co., Ltd, Siemens Healthineers AG, Thermo Fisher Scientific Inc. (U.S.), QuidelOrtho Corporation (U.S.), Agilent Technologies Inc. (U.S.), DiaSorin S.p.A |
Report overview
Segments covered: offering, technology, application, diagnostic approach, end user. Regions: Europe.
In vitro diagnostics (IVD) are tests performed on biological samples such as blood, saliva, and other tissues taken from the human body to detect a wide range of diseases. IVD tests are used to screen biological samples to monitor individuals’ health and prevent or diagnose diseases. These consist of various tests based on techniques such as enzyme-linked immunosorbent assay (ELISA), radioimmunoassay, polymerase chain reaction (PCR), isothermal nucleic acid amplification, and next-generation sequencing. These tests can be performed in laboratories, homes, and healthcare facilities.
The growth of the Europe IVD market is attributed to the rising prevalence of chronic diseases coupled with the increasing geriatric population, the rising prevalence of infectious diseases, the growing demand for point-of-care (PoC) and rapid diagnostics, rising awareness regarding early disease diagnosis, rising healthcare expenditures, and increasing funding for research activities.
However, stringent technical requirements and regulatory processes for high/moderate-complexity tests and the variance in test results observed in rapid IVD tests restrain the growth of the IVD market. The increasing inclination toward personalized medicine and advancements in genomics and proteomics are expected to create growth opportunities for the players operating in this market. However, the evolving regulatory landscape is a major challenge for market growth.
Report infographic
Market dynamics
1 factors across 1 forceRising Awareness Regarding Early Disease Diagnosis is Driving the Market
Early diagnosis of infectious diseases leads to better treatment and future care. It helps healthcare professionals and patients make important medical decisions regarding care and support. There is a growing awareness about early disease diagnosis due to its advantages. Diagnosing a disease in its early stages can help patients save significantly on treatment costs. For instance, according to the WHO, studies conducted in some high-income countries have revealed that the treatment of cancer patients diagnosed early leads to cost savings by two to four times. Additionally, early diagnosis can be lifesaving for patients with critical diseases such as cancer.
Laboratory examination is one of the most effective and popularly practiced testing techniques for disease diagnosis. Immunoassays, biochemical characterization, polymerase chain reaction, isothermal nucleic acid amplification, and next-generation sequencing are performed to identify a comprehensive range of chronic and infectious diseases. Organizations are undertaking initiatives to promote early diagnosis and prevent/eradicate mortalities associated with infectious diseases.
Table of contents
13 chapters · 292 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Offering | Kits & Reagents | — |
| By Technology | Molecular Diagnostics | — |
| By Application | — | Cardiology |
| By Diagnostic Approach | Laboratory Testing | — |
| By End User | — | Hospitals & clinics |
By Offering
- The kits & reagents segment is expected to account for the largest share of the market.
- The large market share of this segment is attributed to the frequent use of reagents and kits in the detection of various chronic diseases, the commercial availability of a diverse range of reagents and consumables for the diagnosis of various diseases, the increase in the volume of testing for infectious diseases such as COVID-19 and influenza, and the growing awareness about self-testing among the general population.
By Technology
- The molecular diagnostics segment is expected to account for the largest share of the market.
- The segment’s large share is mainly attributed to the technological innovations and the advantages of molecular diagnostics tests, such as cost-effectiveness, rapid results, and high sensitivity and specificity over laboratory tests.
- Additionally, the growing prevalence of infectious diseases is also increasing the demand for molecular diagnostics.
- In Europe, several factors driving the growth in the genomic sector increase the adoption of molecular diagnostic products.
- For instance, the establishment of national programs or pan-European programs, such as the “1+ Million Genomes” initiative, which involves 23 countries across Europe and aims to improve the uptake of genomics by healthcare systems and in personalized healthcare.
By Application
- The Cardiology Segment Is Projected to Register the Highest CAGR During the Forecast Period
- The cardiology segment is expected to register the highest CAGR during the forecast period.
- Cardiovascular diseases (CVD) remain the leading cause of death globally.
- According to the American Heart Association, in 2020 highest mortality rates due to cardiovascular diseases were reported in Eastern Europe and Central Asia.
- Thus, the high prevalence of cardiovascular diseases is increasing the demand for IVD testing in the region.
- IVD testing is used for the biomarker measurement.
- The early-stage biomarkers of CVD can potentially save many lives and help alleviate the global burden of CVD.
By Diagnostic Approach
- The laboratory testing segment is expected to account for the largest share of the market.
- The laboratory testing approach for IVD has many advantages over other approaches.
- It has higher accuracy and reliability when compared to point-of-care testing.
- The laboratory equipment and analyzers have a high sensitivity and specificity.
- Unlike point-of-care testing, laboratory testing can be performed on all IVD tests.
- Such factors support the large market share of the segment.
By End User
- The hospitals & clinics segment is expected to register the highest CAGR during the forecast period.
- The highest CAGR of this segment is attributed to the increasing number of hospitalizations due to various diseases requiring molecular diagnosis and the proliferation of hospitals and clinics in the region, leading to growth in the utilization of molecular diagnostic products.
Geographic analysis
Europe
Fastest growthFrance is expected to register the highest CAGR during the forecast period. The highest CAGR of this regional market is attributed to the increasing prevalence of infectious diseases, growth in the geriatric population, rising prevalence of cancer, and government initiatives to improve healthcare infrastructure in France. For instance, in June 2021, the Government of France launched the Health Innovation Plan to improve the healthcare system of France with a total budget of USD 6.2 billion (EUR 7.5 billion). Of this, USD 0.8 billion (EUR 1 billion) is allocated to R&D infrastructures, cross-cutting research support, attracting high-level scientists, clusters, and translational research. The fund of USD 1.2 billion (EUR 1.5 billion) was allocated for national projects and an Important Project of Common European Interest (IPCEI) to accelerate the development of healthcare innovations. Additionally, USD 1.9 billion (EUR 2.4 billion) for improving medical technologies, biotherapies, emerging infectious diseases, digital health, and CBRN (Chemical, Biological, Radiological, Nuclear) sectors. France: Fastest Growing Market
Competitive landscape
- Abbott Laboratories (U.S.)
- Becton
- Dickinson and Company (U.S.)
- Bio-Rad Laboratories, Inc. (U.S.)
- Danaher Corporation (U.S.)
- F. Hoffmann-La Roche Ltd. · Switzerland
- Illumina, Inc. (U.S.)
- QIAGEN N.V. · Netherlands
- Shenzhen Mindray Bio-Medical Electronics Co., Ltd · China
- Siemens Healthineers AG · Germany
- Thermo Fisher Scientific Inc. (U.S.)
- QuidelOrtho Corporation (U.S.)
- Agilent Technologies Inc. (U.S.)
- DiaSorin S.p.A · Italy
Frequently asked questions
The Europe IVD market is segmented based on product & solution (reagents & kits, systems, and software & services) and a wide range of technologies (immunoassay/immunochemistry, biochemistry/clinical chemistry, molecular diagnostics, microbiology, hematology, coagulation/hemostasis, urinalysis, and other technologies) offered by key companies to various end users, such as diagnostic laboratories, hospitals & clinics, home healthcare, and other end users. The Europe IVD market studied in this report involves the value analysis of various segments and sub-segments of in-vitro diagnostics at regional and country levels.
Cite this report
Meticulous Research. (2025). Europe IVD Market - Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 1041035). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/europe-ivd-market-5718