Antibody-Drug Conjugates (ADC) Market (2026-2036)
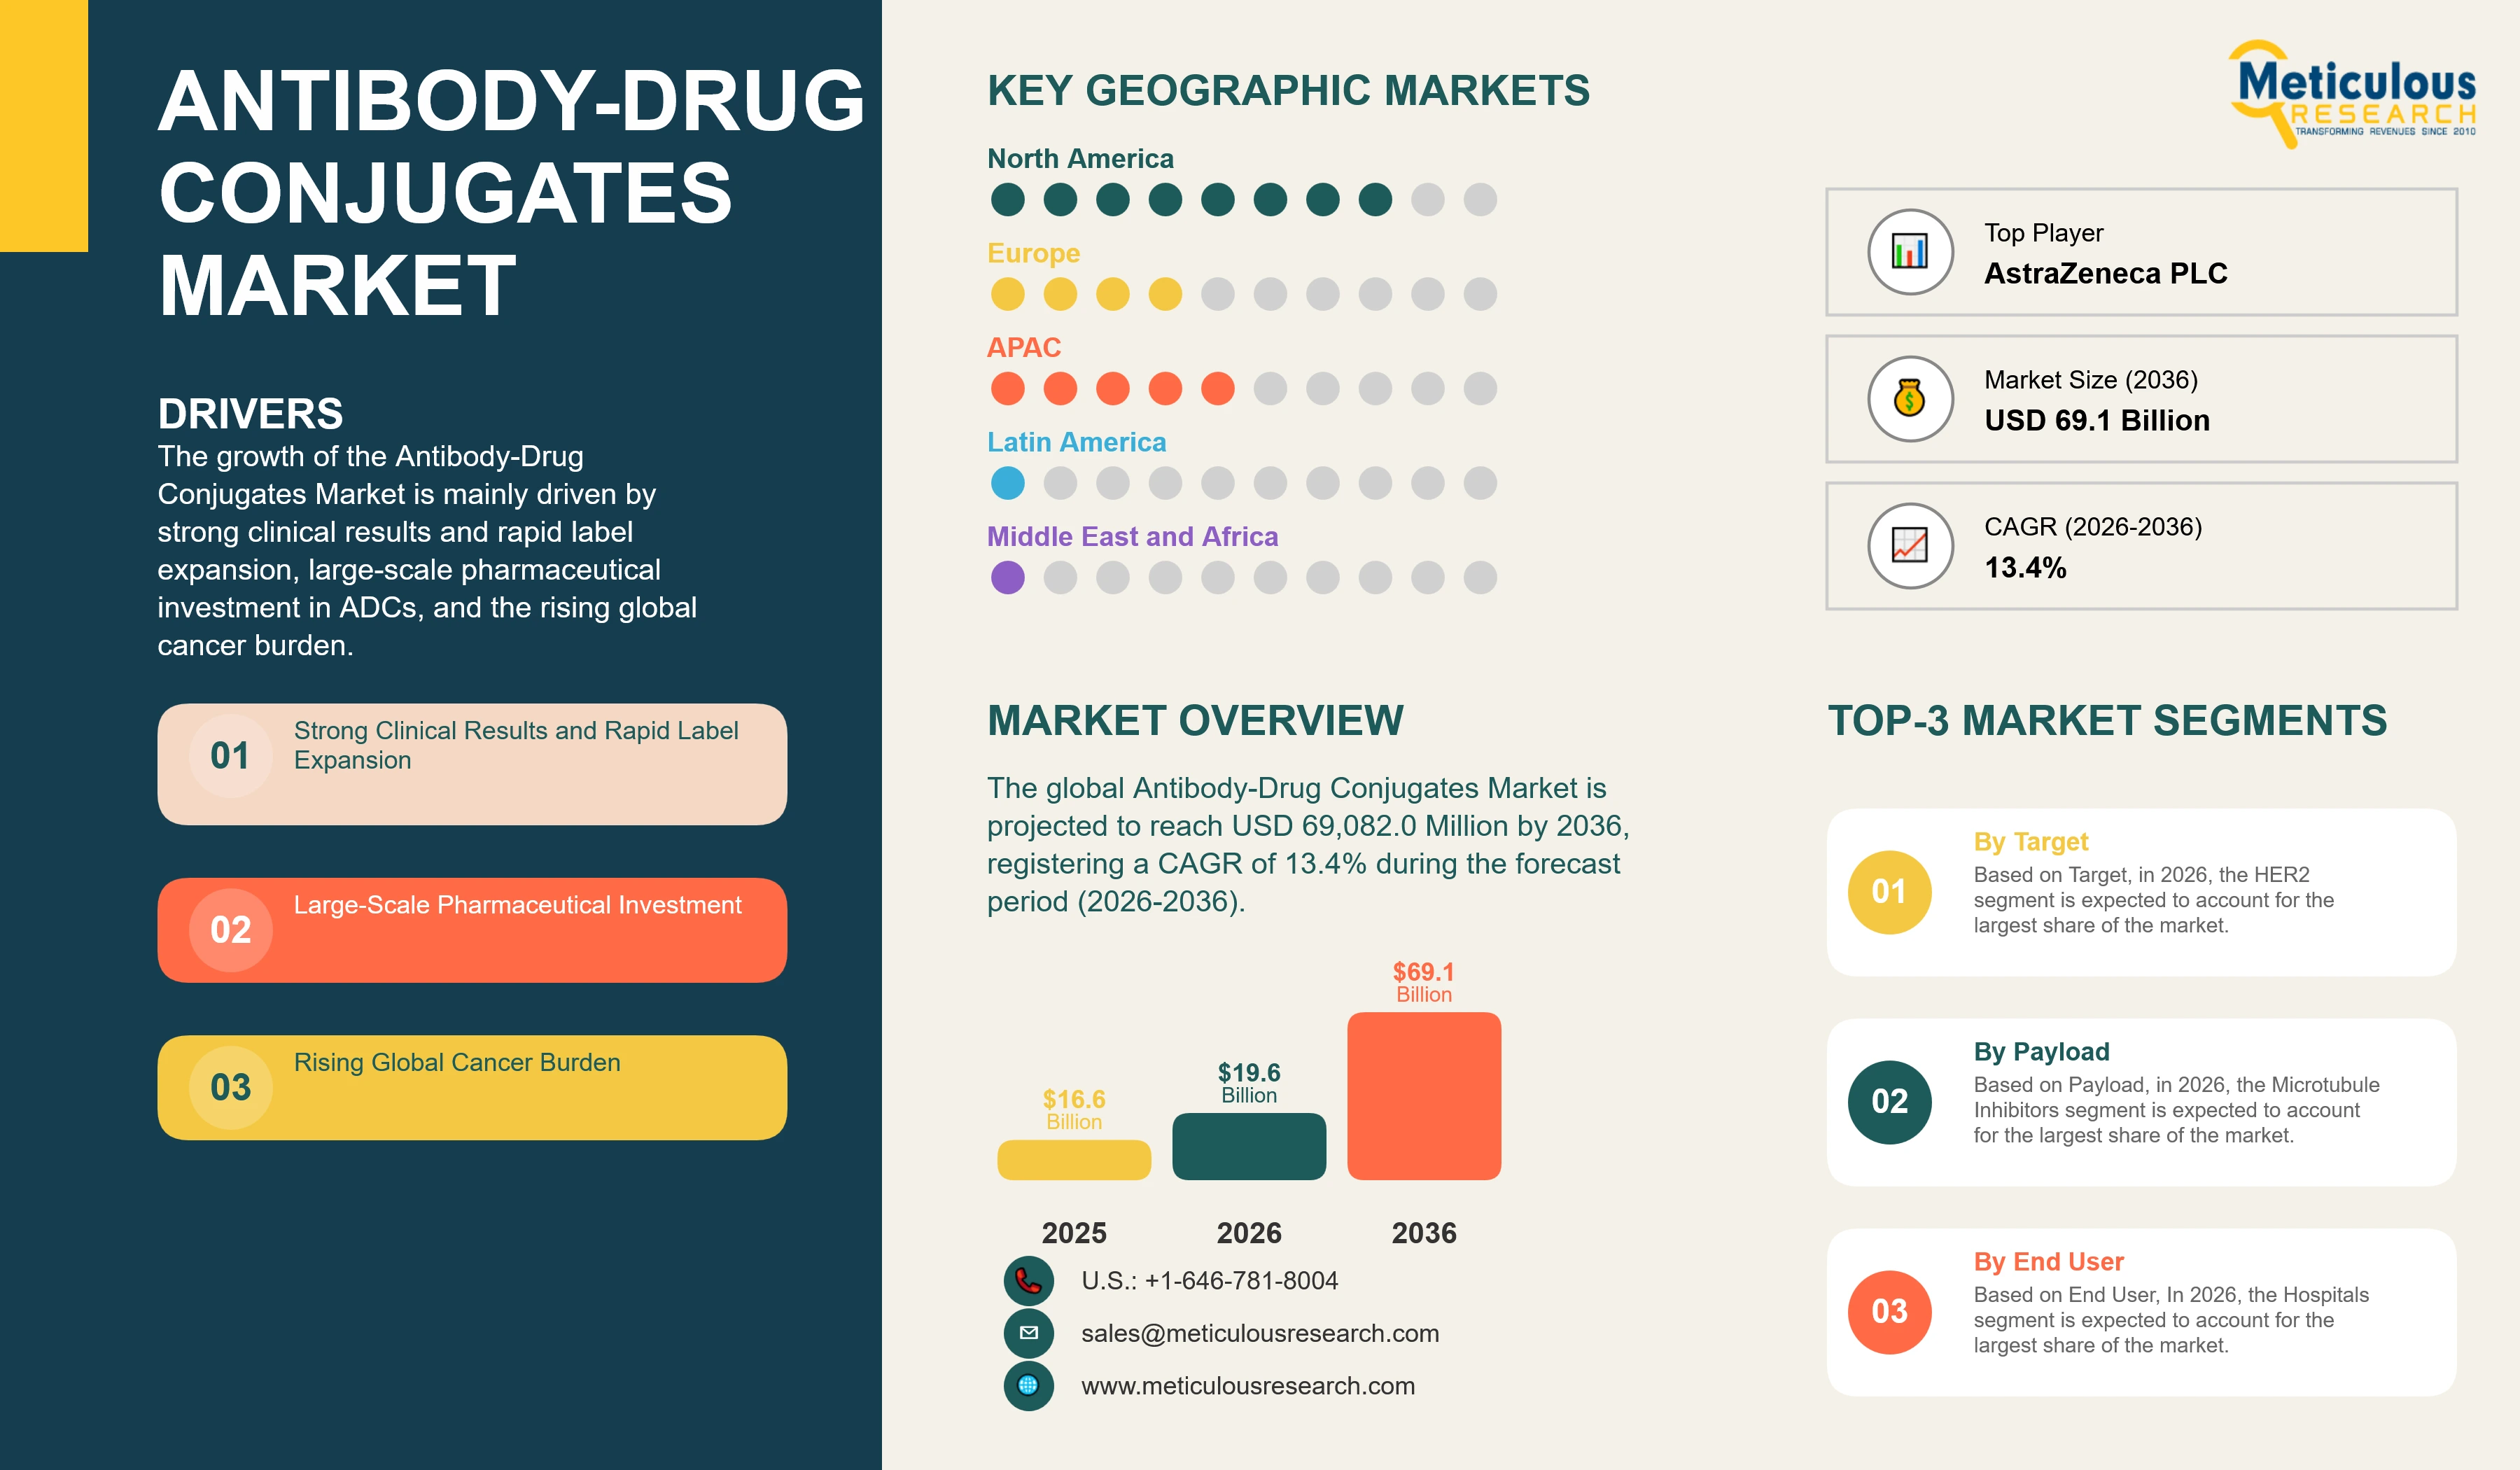
The global Antibody-Drug Conjugates Market was valued at USD 16,633.6 million in 2025. This market is expected to reach USD 69,082.0 million by 2036 from an estimated USD 19,622.0 million in 2026, at a CAGR of 13.4% during the forecast period (2026-2036).
- Published
- Nov 2026
- Pages
- 310
- Format
- PDF + Excel
- Report ID
- MRHC - 1042182
- Base year
- 2025
- 2024 · HISTORICAL
- $13.96B
- 2036
- $69.08B
- CAGR 2026–2036
- 13.4%
2024–2025 baseline · 2026–2036 forecast at 13.4% CAGR · hover a bar for the value
Key highlights
The global Antibody-Drug Conjugates Market is projected to reach USD 69, 082.0 million by 2036 from an estimated USD 19,622.0 million in 2026, at a CAGR of 13.4%. The market grew from USD 13,960.3 million in 2024 to USD 16,633.6 million in 2025, led by new indications for Enhertu, Padcev, and Polivy.
Annual growth was 19.1% in 2025 and is expected to be 18.0% in 2026. Growth stays high until the early 2030s as pipeline ADCs launch, and then eases to 6.9% by 2036 as older products lose exclusivity.
By target, HER2 is expected to account for the largest share of 45.5% in 2026, while emerging targets are projected to register the highest CAGR of 51.6%. Among established targets, TROP2 grows fastest, at a CAGR of 20.7%.
By payload, microtubule inhibitors are expected to account for the largest share of 54.3% in 2026, while novel payloads are projected to register the highest CAGR of 76.1%. Topoisomerase I inhibitors become the largest payload segment from 2028 and reach a share of 71.2% by 2036.
By linker, cleavable linkers are expected to account for the larger share of 86.7% in 2026 and to register the higher CAGR of 14.4%. By format, monospecific ADCs hold 99.8% of the market in 2026, while bispecific ADCs register the highest CAGR of 67.8%.
By indication, breast cancer is expected to account for the largest share of 47.4% in 2026, while other indications are projected to register the highest CAGR of 40.2%. Among the major cancer types, lung cancer grows fastest, at a CAGR of 37.9%. By end user, hospitals hold the largest share of 60.2%, while specialty cancer centers grow fastest, at a CAGR of 13.7%.
North America is expected to account for the largest share of 57.0% of the market in 2026, and the U.S. is the largest country market in every year. Asia-Pacific is projected to register the highest CAGR of 16.8%, led by China, and India is the fastest-growing country, at a CAGR of 22.4%.
The alliance of AstraZeneca and Daiichi Sankyo is estimated to have led the market in 2025 with a share of 30.7%, followed by F. Hoffmann-La Roche Ltd (25.3%) and Pfizer Inc. (20.0%). The 19 profiled companies announced 64 verified developments between January 2024 and November 2026, led by 40 approvals.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Historical Year | 2024 |
| CAGR (2026-2036) | 13.4% |
| Format | PDF, Excel & Cloud Portal · 310 pages |
| Market Size in 2025 | USD 16,633.6 Million |
| Market Size in 2026 | USD 19,622.0 Million |
| Market Size in 2036 | USD 69,082.0 Million |
| Segments Covered | By Target: HER2, TROP2, Nectin-4, Hematologic Targets (CD30, CD79b, CD22/CD33 & Other Hematologic Targets, BCMA), FRα, Emerging Targets (B7-H3, HER3, c-Met, Other Emerging Targets). By Payload: Microtubule Inhibitors (Auristatins [MMAE/MMAF], Maytansinoids [DM1/DM4]), Topoisomerase I Inhibitors (Deruxtecan [DXd], SN-38 & Other Camptothecins), DNA-Damaging Agents (Calicheamicin, PBD & Other DNA Alkylators), Novel Payloads. By Linker: Cleavable Linkers, Non-Cleavable Linkers. By Format: Monospecific ADCs, Bispecific ADCs, Dual-Payload ADCs. By Indication: Breast Cancer (HER2-Positive, HER2-Low & HER2-Ultralow, Triple-Negative & HR+/HER2-), Urothelial Cancer, Lung Cancer, Lymphoma, Leukemia & Multiple Myeloma, Gastric Cancer, Gynecologic Cancers (Ovarian, Cervical, Endometrial), Other Indications. By End User: Hospitals, Specialty Cancer Centers, Other End Users. |
| Countries Covered | North America: U.S., Canada. Europe: Germany, France, U.K., Italy, Spain, Switzerland, Rest of Europe. Asia-Pacific: China, Japan, South Korea, India, Australia, Rest of Asia-Pacific. Latin America: Brazil, Mexico, Argentina, Rest of Latin America. Middle East & Africa: Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa. |
| Key Companies | AstraZeneca, Daiichi Sankyo, Pfizer, Astellas Pharma, Roche, Gilead Sciences, AbbVie, Takeda, GSK, Merck & Co., Johnson & Johnson, Bristol Myers Squibb, Genmab, BioNTech, Kelun-Biotech, Hengrui, RemeGen, ADC Therapeutics, and Sichuan Biokin. |
Report overview
Segments covered: target, payload, linker, format, indication, end user.
The growth of this market is mainly driven by strong clinical results and rapid label expansion, large-scale pharmaceutical investment in ADCs, and the rising global cancer burden. However, dose-limiting toxicities, manufacturing complexity and cost, high prices and reimbursement barriers, and late-stage clinical setbacks restrain the growth of this market.
Furthermore, bispecific and dual-payload ADCs, novel payload classes, and the use of ADCs in earlier lines of therapy and with immunotherapies are expected to offer growth opportunities for the players operating in this market. However, crowding around validated targets, resistance and treatment sequencing, geopolitically exposed supply chains and partners, and emerging biosimilar competition are major challenges. The shift toward topoisomerase I inhibitor payloads, the rise of China as an ADC innovation hub, consolidation through large acquisitions, and the expansion of specialized ADC manufacturing capacity are prominent trends in this market.
Antibody-drug conjugates (ADCs) combine a monoclonal antibody that binds to a target on cancer cells with a highly potent drug, called the payload, joined by a chemical linker. The antibody carries the payload to the tumor, which allows the use of drugs too toxic to give as standard chemotherapy. As of June 2026, 23 ADCs had been approved worldwide, including products that were later withdrawn, according to Biochempeg.
The market covers the sales of approved ADCs for cancer at manufacturer selling prices, and market value is assigned to the country where the drugs are sold. Enhertu, the largest ADC, reached combined sales of about USD 4.98 billion in 2025, up 33% from USD 3.75 billion in 2024, according to AstraZeneca and Daiichi Sankyo. Kadcyla, Padcev, Polivy, Adcetris, and Trodelvy are the other large products.
ADCs are moving into earlier lines of therapy, where patients are treated for longer. In 2025 and 2026, the FDA approved ADCs in first-line HER2-positive metastatic breast cancer, early breast cancer, first-line triple-negative breast cancer (TNBC), and muscle-invasive bladder cancer. China approved iza-bren, an EGFR and HER3 bispecific ADC from Sichuan Biokin, in June 2026, the first approval of a bispecific ADC in the world.
The next phase of growth depends on new targets, new payloads, and new formats. Most new ADCs use topoisomerase I inhibitor payloads, and late-stage programs target TROP2, B7-H3, HER3, c-Met, and other antigens. At the same time, toxicity, manufacturing complexity, high prices, and crowding around HER2 and TROP2 shape which products succeed.
“ADCs are now part of first-line care in HER2-positive and triple-negative breast cancer. My main question is what to give after progression, because the three leading ADCs in breast cancer use similar payloads.”
This reflects why earlier-line use drives growth and why resistance and treatment sequencing remain a major challenge.
“ADCs are among the most expensive drugs we buy, and each new indication adds patients and treatment cycles. We also need staff time to monitor lung and eye side effects.”
This reflects the large share of hospitals and the restraints from high prices and dose-limiting toxicities.
“Health technology assessment bodies ask for strong survival data and confidential discounts. Reimbursement can take years, even after approval by the European Commission.”
This reflects why high prices and reimbursement barriers restrain the market outside the U.S.
“Most of the new assets we review come from China, often with bispecific designs or new payloads. Global partners pay for the speed of Chinese clinical development, but they also study supply and policy risks closely.”
This highlights the rise of China as an ADC innovation hub and the growth of bispecific ADCs and novel payloads.
Report infographic
Market dynamics
18 factors across 5 forcesStrong Clinical Results and Rapid Label Expansion
Strong survival results in large Phase 3 trials are the main driver of the ADC market. In the DESTINY-Breast09 trial, Enhertu with pertuzumab gave a median progression-free survival of 40.7 months in first-line HER2-positive metastatic breast cancer, compared to 26.9 months with the previous standard regimen. In the EV-303 trial, Padcev with Keytruda reduced the risk of death by 50% compared to surgery alone in muscle-invasive bladder cancer. Each label expansion adds patients and extends treatment duration without the cost of developing a new drug.
Large-Scale Pharmaceutical Investment
Large pharmaceutical companies have invested heavily in ADCs through acquisitions, licensing deals, and manufacturing. Pfizer acquired Seagen for USD 43 billion in December 2023, and AbbVie completed the acquisition of ImmunoGen for about USD 10.1 billion in February 2024. Gilead agreed to acquire Tubulis in April 2026 for USD 3.15 billion upfront. Roche, including its Genentech unit, signed five ADC licensing deals with Chinese companies between January 2025 and October 2026. This flow of capital funds clinical trials beyond the reach of most small developers.
Rising Global Cancer Burden
The number of people diagnosed with cancer is rising as populations grow and age. According to IARC, there were about 20 million new cancer cases worldwide in 2022, and new cases are projected to reach 35 million by 2050. Breast cancer and lung cancer, the two largest indications for ADCs, accounted for about 2.3 million and 2.5 million new cases in 2022, respectively. Wider testing for HER2-low, HER2-ultralow, and other biomarkers also increases the number of patients eligible for ADCs.
Table of contents
14 chapters · 191 sections · 310 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Target | HER2 | Emerging Targets |
| By Payload | Microtubule Inhibitors | Novel Payloads |
| By Linker | — | Bispecific ADCs |
| By Format | Monospecific ADCs | Bispecific ADCs |
| By Indication | Breast Cancer | Other Indications |
| By End User | Hospitals | Specialty Cancer Centers |
By Target
- The HER2 segment is expected to account for the largest share of 45.5% of the market, valued at USD 8,920.2 million.
- The large share of this segment is mainly due to the sales of Enhertu and Kadcyla in breast and gastric cancer and to new Enhertu approvals in earlier lines of breast cancer.
- However, the Emerging Targets segment is projected to register the highest CAGR of 51.6% during the forecast period.
- This growth is mainly driven by late-stage ADCs against B7-H3, HER3, c-Met, CDH6, and other antigens, including iza-bren.
- TROP2 grows fastest, at a CAGR of 20.7%, supported by first-line TNBC approvals for Datroway and Trodelvy.
By Payload
- The Microtubule Inhibitors segment is expected to account for the largest share of 54.3% of the market, valued at USD 10,655.1 million.
- The large share of this segment is mainly due to the use of MMAE, MMAF, DM1, and DM4 in Padcev, Kadcyla, Polivy, Adcetris, and most first- and second-generation ADCs.
- However, the Novel Payloads segment is projected to register the highest CAGR of 76.1% during the forecast period, from a very small base.
- This growth is mainly driven by immune-stimulating, degrader, and other new payloads.
- Topoisomerase I inhibitors grow at a CAGR of 19.2% and become the largest payload segment from 2028, as most new ADCs use these payloads.
By Linker
- The Cleavable Linkers segment is expected to account for the larger share of 86.7% of the market, valued at USD 17,020.3 million.
- The large share of this segment is mainly due to the use of cleavable linkers in nearly all marketed and late-stage ADCs.
- This segment is also projected to register the higher CAGR of 14.4% during the forecast period.
- This growth is mainly driven by the bystander effect of cleavable linkers, which release the payload in and around tumor cells and help treat tumors with uneven target expression.
By Format
- The Monospecific ADCs segment is expected to account for the largest share of 99.8% of the market, valued at USD 19,592.0 million.
- The large share of this segment is mainly due to the fact that all ADCs approved before June 2026 used monospecific antibodies.
- However, the Bispecific ADCs segment is projected to register the highest CAGR of 67.8% during the forecast period.
- This growth is mainly driven by iza-bren, approved in China in June 2026 and in global development by Bristol Myers Squibb, and by HER2 biparatopic and EGFR and c-Met bispecific ADCs.
By Indication
- The Breast Cancer segment is expected to account for the largest share of 47.4% of the market, valued at USD 9,310.3 million.
- The large share of this segment is mainly due to the use of HER2 and TROP2 ADCs across all major breast cancer subtypes.
- However, the Other Indications segment is projected to register the highest CAGR of 40.2% during the forecast period, from a small base.
- This growth is mainly driven by pipeline ADCs in prostate, head and neck, esophageal, and other solid tumors.
- Lung cancer grows fastest, at a CAGR of 37.9%, as TROP2, B7-H3, HER3, and c-Met ADCs reach the market.
By End User
- The Hospitals segment is expected to account for the largest share of 60.2% of the market, valued at USD 11,805.8 million.
- The large share of this segment is mainly due to the central role of hospitals in cancer care in Europe and Asia-Pacific and the need to manage infusions and side effects.
- However, the Specialty Cancer Centers segment is projected to register the highest CAGR of 13.7% during the forecast period.
- This growth is mainly driven by the shift of infused cancer therapy to outpatient cancer centers in the U.S. and Europe and the growth of private cancer hospital chains in emerging markets.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of 57.0% of the market, valued at USD 11,178.9 million, and to grow at a CAGR of 11.4%. The large share of this region is mainly due to the size of the U.S. market, where most ADCs launch first and prices are highest. The U.S. accounted for USD 2,446 million of Enhertu sales in 2025, according to AstraZeneca and Daiichi Sankyo. North America
Asia-Pacific
Fastest growthAsia-Pacific is expected to account for a share of 20.1% of the market in 2026, valued at USD 3,941.9 million, and to register the highest CAGR of 16.8% during the forecast period. This growth is mainly driven by China, where domestic ADCs from Kelun-Biotech, Hengrui, RemeGen, and Sichuan Biokin are reaching the market and the NRDL is expanding access. China is the second-largest country market in the report, and India is the fastest-growing country, at a CAGR of 22.4%. Asia-Pacific
Europe
Europe is expected to account for a share of 19.2% of the market in 2026, valued at USD 3,765.3 million, and to grow at a CAGR of 14.2%. Access is shaped by national health technology assessment and pricing rules, and the EU HTA Regulation introduced joint clinical assessments for new cancer medicines from January 2025. Germany is the largest country market in the region, as new medicines can be sold at launch prices while their added benefit is assessed. Europe
Latin America
Latin America is expected to account for a share of 2.1% of the market in 2026, valued at USD 404.5 million, and to grow at a CAGR of 16.3%. Most ADC use takes place in private hospitals and cancer centers, as public health systems have limited budgets for high-cost cancer drugs. Brazil is the largest country market, and its regulator ANVISA takes part in Project Orbis. Latin America
Middle East & Africa
The Middle East & Africa is expected to account for a share of 1.7% of the market in 2026, valued at USD 331.4 million, and to grow at a CAGR of 16.5%. Gulf countries such as Saudi Arabia and the UAE have high health spending and fast-track pathways for drugs approved by the FDA or EMA. Access in most of Africa, however, is very limited. Saudi Arabia is the largest country market in the region in 2026. Middle East & Africa
Competitive landscape
The global Antibody-Drug Conjugates Market is concentrated, as a small number of products account for most sales. The alliance of AstraZeneca and Daiichi Sankyo is estimated to have led the market in 2025 with a share of 30.7%, based on Enhertu and Datroway. It was followed by F. Hoffmann-La Roche Ltd (25.3%), Pfizer Inc. (20.0%), Gilead Sciences, Inc. (8.4%), Takeda Pharmaceutical Company Limited (5.4%), and AbbVie Inc. (4.2%), while other players accounted for 6.0%.
Between January 2024 and November 2026, the 19 companies profiled in the report announced 64 verified developments related to ADCs. Approvals (40) were the most common type of development, followed by licensing deals (11), acquisitions (5), partnerships (4), investments (2), agreements and contracts (1), and market access decisions (1). Approvals focused on earlier lines of therapy in breast and bladder cancer and on new ADCs in China, while licensing deals focused on next-generation ADCs from Chinese developers.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Antibody-Drug Conjugates Market. The key players profiled in the report include AstraZeneca PLC (U.K.), Daiichi Sankyo Company, Limited (Japan), Pfizer Inc. (U.S.), Astellas Pharma Inc. (Japan), F. Hoffmann-La Roche Ltd (Switzerland), Gilead Sciences, Inc. (U.S.), AbbVie Inc. (U.S.), Takeda Pharmaceutical Company Limited (Japan), GSK plc (U.K.), Merck & Co., Inc. (U.S.), Johnson & Johnson (U.S.), Bristol Myers Squibb Company (U.S.), Genmab A/S (Denmark), BioNTech SE (Germany), Sichuan Kelun-Biotech Biopharmaceutical Co., Ltd. (China), Jiangsu Hengrui Pharmaceuticals Co., Ltd. (China), RemeGen Co., Ltd. (China), ADC Therapeutics SA (Switzerland), and Sichuan Biokin Pharmaceutical Co., Ltd. (China).
- AstraZeneca
- Daiichi Sankyo
- Pfizer
- Astellas Pharma
- Roche
- Gilead Sciences
- AbbVie
- Takeda
- GSK
- Merck & Co.
- Johnson & Johnson
- Bristol Myers Squibb
- Genmab
- BioNTech
- Kelun-Biotech
- Hengrui
- RemeGen
- ADC Therapeutics
- Sichuan Biokin
Expert perspectives
The market is in a period of strong growth, as new indications for marketed ADCs and new launches add patients each year. Annual growth of 18.0% in 2026 is expected to remain high until the early 2030s. It then eases to 6.9% by 2036, as Kadcyla, Adcetris, and other older products lose exclusivity and face biosimilars.
The structure of the market shifts from HER2 and microtubule inhibitor payloads toward a wider mix of targets and topoisomerase I inhibitor payloads. HER2 falls from 45.5% of the market in 2026 to 31.4% in 2036, while TROP2 rises from 11.2% to 20.7% and emerging targets reach 28.4%. Lung cancer rises from 3.5% of the market in 2026 to 24.7% in 2036.
Geography also shifts, as Asia-Pacific raises its share from 20.1% in 2026 to 27.1% in 2036, led by China, while North America falls from 57.0% to 47.5%. In a bear case with more late-stage failures and tighter price controls, the market would reach about USD 56,736.4 million by 2036. In a bull case with faster success of new targets and bispecific ADCs, it would reach about USD 78,630.9 million.
For drug developers, the strongest positions are likely to belong to companies that combine differentiated payloads or formats with manageable toxicity and a path into earlier lines of therapy. Access to Chinese innovation through licensing, secure manufacturing capacity, and a clear sequencing strategy in breast cancer will separate winners from crowded followers.
Customer perspectives
Primary interviews were held with medical oncologists and hematologists, hospital and cancer center pharmacy directors, market access and pricing experts, and business development and R&D executives at ADC developers and contract manufacturers. The views below are summarized from these interviews and attributed to generic roles.
Frequently asked questions
The global Antibody-Drug Conjugates Market is estimated at USD 19,622.0 million in 2026, up from USD 16,633.6 million in 2025.
Cite this report
Meticulous Research. (2026). Antibody-Drug Conjugates (ADC) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1042182). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/antibody-drug-conjugates-market-6865