Ambulatory EHR Market (2024-2031)
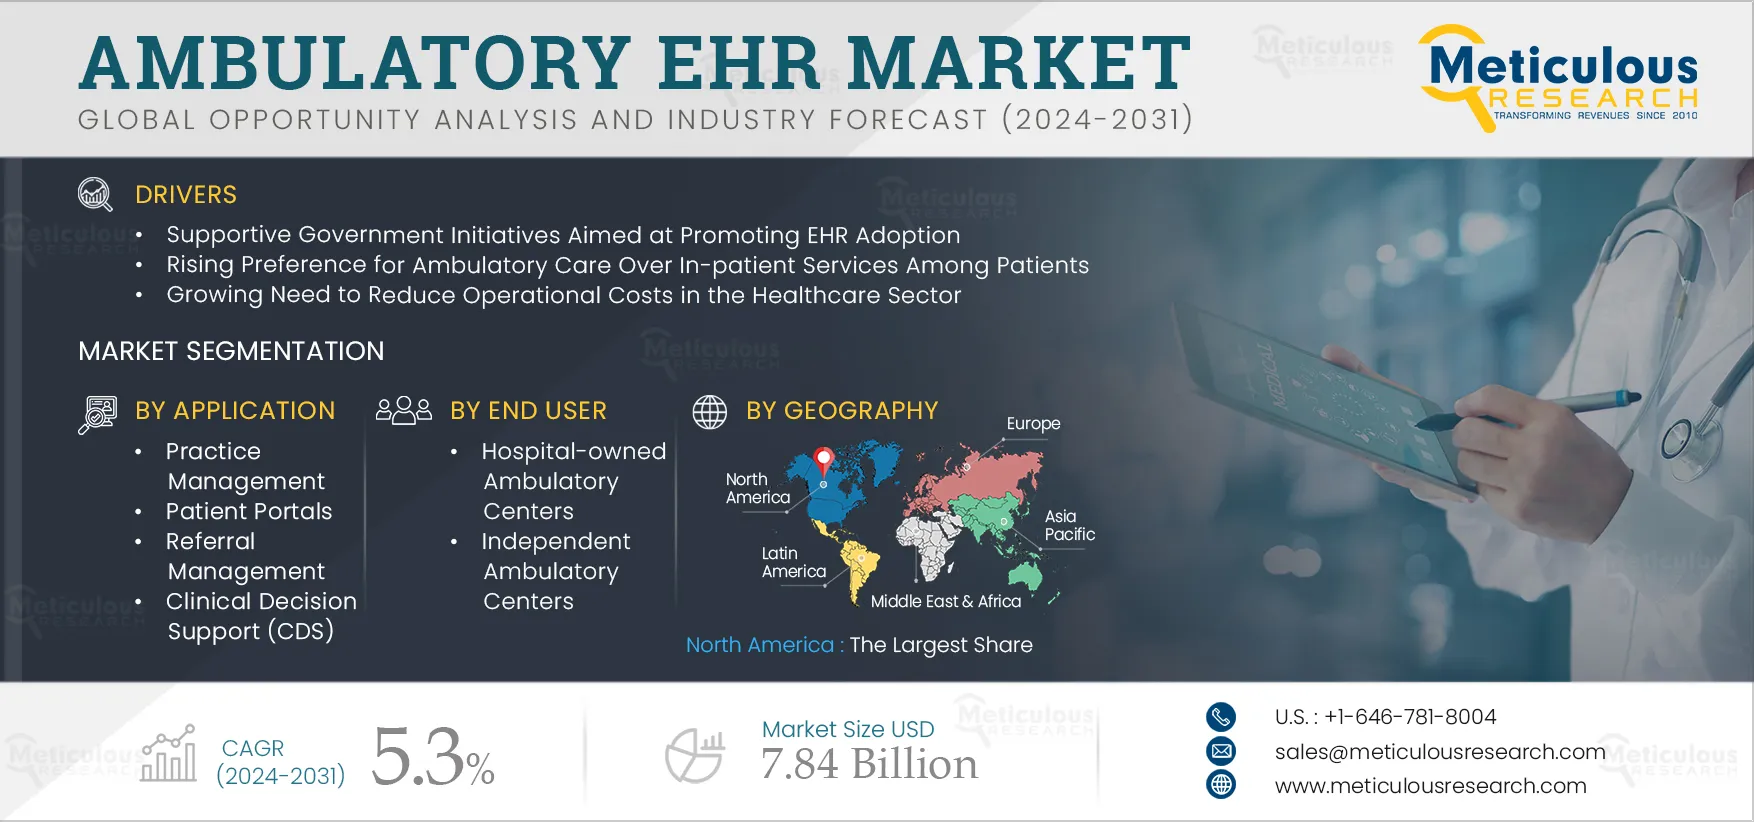
The Ambulatory EHR Market was valued at $5.2 billion in 2023. This market is expected to reach $7.84 billion by 2031, from an estimated $5.47 billion in 2024, at a CAGR of 5.3% during the forecast period 2024-2031. Ambulatory EHR Market Size & Forecast The growth of the ambulatory EHR market is
- Published
- May 2024
- Pages
- 185
- Format
- PDF + Excel
- Report ID
- MRHC - 104496
- Base year
- 2023
- 2023 · BASELINE
- $5.20B
- 2031
- $7.84B
- CAGR 2024–2031
- 5.3%
2023 baseline · 2024–2031 forecast at 5.3% CAGR · hover a bar for the value
Key highlights
By Deployment Mode: In 2024, the Cloud/Web-based Deployment Mode Segment to Dominate the Ambulatory EHR Market
By Type: In 2024, the All-in-One Segment to Dominate the Ambulatory EHR Market
By Practice Size: In 2024, the Large Practices Segment to Dominate the Ambulatory EHR Market
By Application: In 2024, the Practice Management Segment to Dominate the Ambulatory EHR Market
By End User: in 2034, the Hospital-owned Ambulatory Centers Segment to Dominate the Ambulatory EHR Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 185 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 5.3% |
| Market Size (Value) | USD 7.84 Billion by 2031 |
| Segments Covered | By Deployment Mode · Cloud/Web-based Ambulatory EHR · On-premise Ambulatory EHR · By Type · All-in-one Ambulatory EHR · Modular Ambulatory EHR · By Practice Size · Large Practices · Small to Medium-sized Practices · Solo Practices · By Application · Practice Management · Computerized Physician Order Entry (CPOE) · Patient Portals · Clinical Decision Support (CDS) · Referral Management · Population Health Management · Other Applications · (Note: Other applications include mobile solutions, health analytics, billing solutions, and telehealth) · By End User · Hospital-owned Ambulatory Centers · Independent Ambulatory Centers |
| Countries Covered | North America (U.S., Canada), Europe (U.K., Germany, France, Italy, Spain, Denmark, Netherlands, Sweden, Ireland, Belgium, Rest of Europe), Asia-Pacific (China, Japan, India, and Rest of Asia-Pacific), Middle East & Africa and Latin America |
| Key Companies | Epic Systems Corporation (U.S.), Cerner Corporation (U.S.), Medical Information Technology, Inc. (U.S.), Computer Programs and Systems, Inc. (U.S.), Allscripts Healthcare Solutions, Inc. (U.S.), athenahealth, Inc. (U.S.), NextGen Healthcare, Inc (U.S.), eClinicalWorks (U.S.), Greenway Health, LLC (U.S.), CureMD Healthcare (US), and AdvancedMD, Inc. (U.S.) |
Report overview
Segments covered: practice. Regions: North America, Europe, Asia-Pacific.
The growth of the ambulatory EHR market is driven by supportive government initiatives aimed at promoting EHR adoption, the rising preference for ambulatory care over in-patient services among patients, and the growing need to reduce operational costs in the healthcare sector. Additionally, the integration of artificial intelligence (AI) and machine learning (ML) technologies with ambulatory EHRs and the evolving technological landscape in developing countries are expected to create market growth opportunities.
Report infographic
Market dynamics
5 factors across 3 forcesSupportive Government Initiatives Aimed at Promoting EHR Adoption
Governments worldwide are increasingly promoting the adoption of EHR solutions due to their benefits over traditional paper-based health records. This support has resulted in the widespread implementation of EHRs, providing several advantages for both patients and ambulatory practices. These benefits include enhanced patient treatment, improved care coordination, quick access to records, enhanced practice efficiency, cost savings through reduced paperwork, increased patient participation & transparency, and improved diagnostic accuracy, leading to better patient outcomes.
According to the National Coordinator for Health Information Technology, EHR adoption in medical practices has doubled since 2008. As of 2021, nearly 4 in 5 office-based physicians have adopted a certified EHR. Additionally, over 50% of upper-middle-income and high-income countries have implemented national EHR systems. Numerous country-level and regional initiatives have been launched to facilitate the implementation of EMR/EHR systems.
Rising Preference for Ambulatory Care Over In-patient Services Among Patients
Many patients opt for outpatient care over in-patient care due to its convenience. The adoption of ambulatory EHR has surged significantly over the past decade, largely driven by the preference for outpatient treatments among patients. Ambulatory surgical centers enable patients to be discharged within 23 hours of care, thereby reducing the risk of hospital-acquired infections. Costs in ambulatory settings are lower for both patients and payers due to reduced expenses associated with staffing, space, and supplies. These factors have led to the proliferation of ambulatory care centers, with patients increasingly favoring ambulatory care over in-patient alternatives.
According to the Ambulatory Surgery Center Association (U.S.), As of 2022, there were approximately 6,200 Medicare-certified Ambulatory Surgery Centers (ASCs) in the U.S. Additionally, in recent years, there has been a notable increase in patient preference for ambulatory care. This shift is primarily attributed to advancements in clinical technology, the healthcare system's transition towards value-based care, and the shorter duration of hospital stays in ambulatory care settings.
Table of contents
13 chapters · 100 sections · 185 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Deployment Mode | Cloud/Web-based Deployment Mode | — |
| By Type | All-in-One | — |
| By Practice Size | Large Practices | — |
| By Application | Practice Management | Referral management |
| By End User | Hospital-owned Ambulatory Centers | — |
By Deployment Mode
- The cloud/web-based deployment mode segment is expected to account for the larger share of 77.5% of the ambulatory EHR market.
- Cloud/web-based solutions are increasingly being adopted as they facilitate the exchange and integration of data from multiple locations or systems in real time.
- This segment's large market share can be attributed to several factors, including the growing preference for cloud-based deployment due to its numerous benefits, including flexibility, real-time monitoring capabilities, data security features, and lower implementation costs compared to on-premises deployment.
By Type
- The All-in-One Segment to Dominate the Ambulatory EHR Market
- The all-in-one ambulatory EHR segment is expected to account for the larger share of 66.3% of the ambulatory EHR market.
- This segment's large market share can be attributed to the benefits offered by all-in-one ambulatory EHRs, such as ease of use, comprehensive functionalities, absence of compatibility issues, and seamless integration of software and hardware.
By Practice Size
- The Large Practices Segment to Dominate the Ambulatory EHR Market
- The large practices segment is expected to account for the largest share of the ambulatory EHR market.
- Large practices are typically conducted within sizable organizations housing over 50-100 physicians.
- This segment's large market share can be attributed to the rising need for efficient administration and coordination within such extensive setups and equitable distribution of costs and tasks among staff.
By Application
- The practice management segment is expected to account for the largest share of 25.9% of the ambulatory EHR market.
- Practice management typically encompasses appointment scheduling, patient demographics, visual resource planning, document management, billing, and claim management—all essential components utilized in the daily operations of ambulatory practices.
- This segment's large market share can be attributed to factors such as the widespread adoption by ambulatory surgical centers, primarily due to the advanced features offered by these EHRs, including efficient patient scheduling and streamlined management of billings and claims.
- However, the referral management segment is projected to register the highest CAGR of 9.7% during the forecast period.
- A referral management system serves as a vital tool for healthcare providers to oversee patient referrals.
- It facilitates the smooth transition of patients to the next stage of their care process.
- The primary objective of referral management is to streamline communication among primary care physicians, specialists, and other healthcare professionals involved in a patient's care.
By End User
- The Hospital-owned Ambulatory Centers segment is expected to account for the larger share of the market.
- Hospital-owned ambulatory centers, integrated within hospitals, represent a prevalent clinical model in integrated healthcare systems.
- They typically adhere to higher hospital accreditation standards compared to outpatient clinics, ensuring the delivery of high-quality care.
- This segment's large market share can be attributed to factors such as the robust financial capabilities of these centers, facilitating significant investments in advanced EHRs.
- Additionally, the increasing need to streamline unstructured healthcare data further drives the adoption of ambulatory EHRs within these centers.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 51.2% of the ambulatory EHR market, followed by Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America's significant market share can be attributed to the region's well-established healthcare system, supportive government initiatives aimed at promoting EHR adoption, the growing geriatric population, and the rising preference for ambulatory care over in-patient care among patients. By Geography: North America to Dominate the Ambulatory EHR Market in 2024
Asia-Pacific
Fastest growthHowever, the market in Asia-Pacific is projected to register the highest CAGR of 7.0% during the forecast period. The growth of this regional market can be attributed to the increasing need to organize unstructured healthcare data, supportive government initiatives aimed at promoting EHR adoption, and evolving technological landscapes in developing countries within the region.
Competitive landscape
- September 2023
The Georgian Bay Information Network (GBIN), a partnership of six Ontario healthcare organizations, announced its plans to expand the utilization of Oracle Corporation's (U.S.) EHRs by integrating new capabilities for advanced clinical services, optimized medicine administration, and oncology specialty support.
- March 2023
NextGen Healthcare, Inc. (U.S.) launched Mirth Cloud Connect, a cloud-based solution offering interoperability as a managed service.
- October 2021
United Surgical Partners International (U.S.), a subsidiary of Tenet Healthcare Corporation (U.S.), acquired nine ambulatory surgery centers (ASCs) from Compass Surgical Partners (U.S.).
- Epic Systems Corporation (U.S.)
- Cerner Corporation (U.S.)
- Medical Information Technology, Inc. (U.S.)
- Computer Programs and Systems, Inc. (U.S.)
- Allscripts Healthcare Solutions, Inc. (U.S.)
- NextGen Healthcare, Inc (U.S.)
- eClinicalWorks (U.S.)
- Greenway Health, LLC (U.S.)
- CureMD Healthcare (US)
- AdvancedMD, Inc. (U.S.)
Frequently asked questions
This market study covers the market sizes & forecasts of the ambulatory EHR based on deployment mode, type, practice size, application, end user, and geography. This market study also provides the value analysis of various segments and sub-segments of the global ambulatory EHR market at the country level.
Cite this report
Meticulous Research. (2024). Ambulatory EHR Market - Global Opportunity Analysis And Industry Forecast (2024-2031) (Report No. MRHC - 104496). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/ambulatory-ehr-market-5190