3D Printing Materials Market (2024-2031)
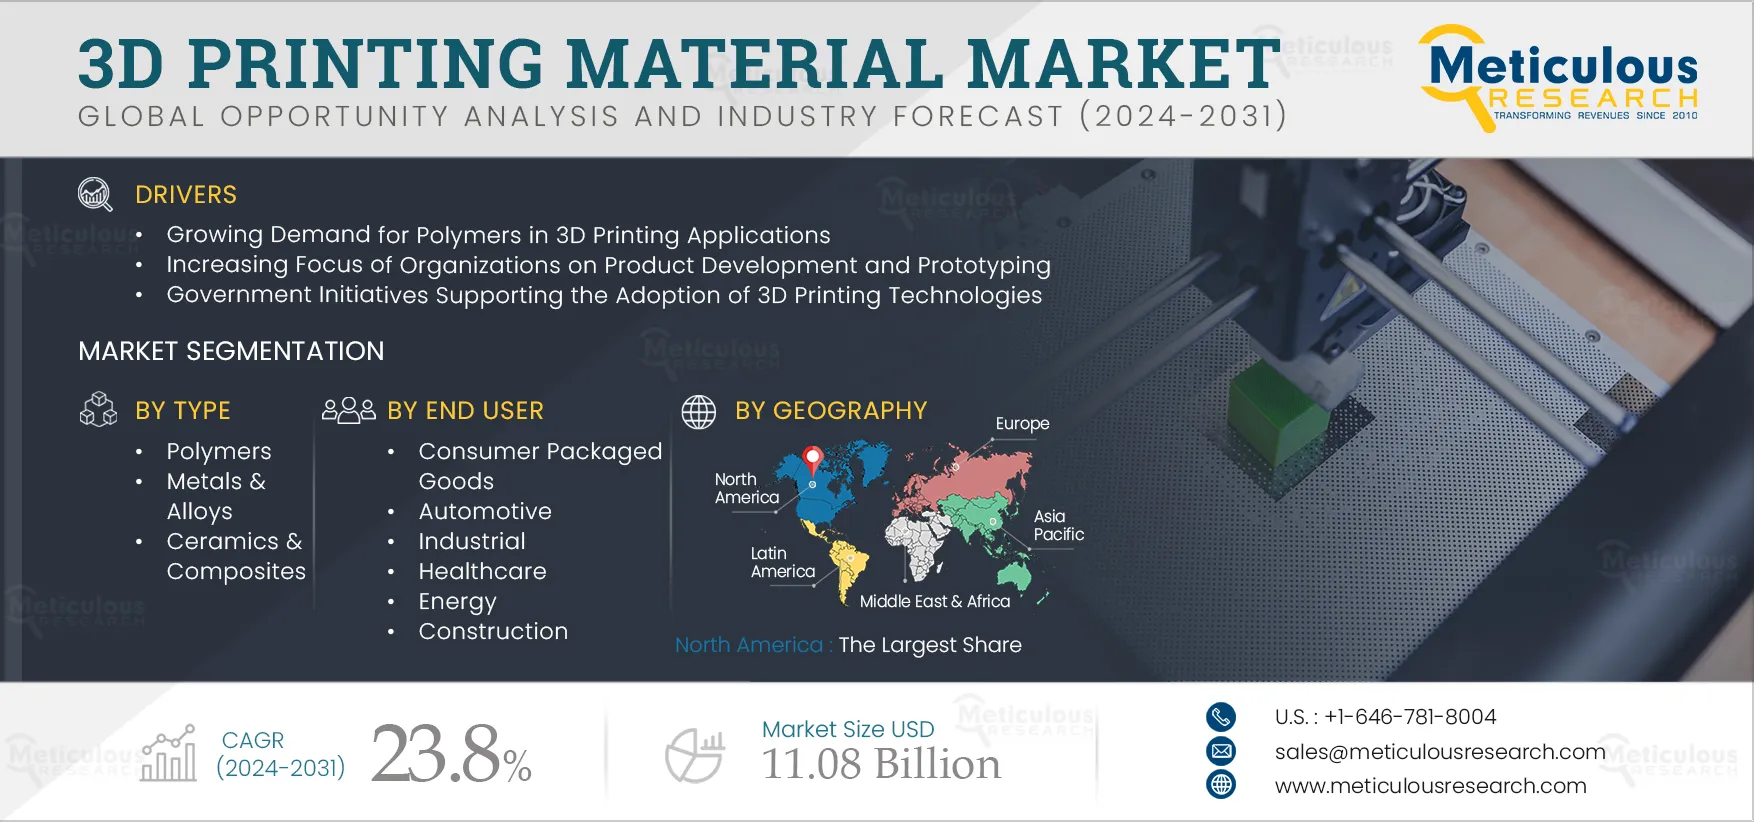
The 3D Printing Materials Market is projected to reach $11.08 billion by 2031, at a CAGR of 23.8% from 2024 to 2031.
- Published
- Apr 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRCHM - 104384
- Base year
- 2023
- 2031 · FORECAST
- $11.08B
- 2031
- $11.08B
- CAGR 2024–2031
- 23.8%
2023 baseline · 2024–2031 forecast at 23.8% CAGR · hover a bar for the value
Key highlights
The Ceramics & Composites Segment is Expected to Register Highest CAGR
The Filament Segment is Expected to Register Highest CAGR
The Electron Beam Melting (EBM) Segment is Expected to Register Highest CAGR
The Industrial Segment is Expected to Register the Highest CAGR
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2024-2031 |
| Base Year | 2023 |
| CAGR | 23.8% |
| Estimated Market Size (Value) | $11.08 billion by 2031 |
| Segments Covered | By Type · Polymers · Photopolymers · Polyamide (PA) · Polylactic Acid · Acrylic Styrene Acrylonitrile (ASA) · Polycarbonates (PC) · Polypropylene (PP) · Thermoplastic Elastomers (TPE) · Other Polymers · Metals & Alloys · Steel · Titanium · Nickel · Aluminum · Copper · Cobalt-Chrome · Other Metals · Ceramics & Composites · By Form · Powders · Filaments · Liquids · By Technology · Fused Deposition Modeling (FDM) · Selective Laser Sintering (SLS) · Stereolithography (SLA) · Direct Metal Laser Sintering (DMLS) · Polyjet · Multi Jet Fusion (MJF) · Digital Light Processing (DLP) · Electron Beam Melting (EBM) · Other Technologies · By End User · Consumer Packaged Goods · Electronic Appliances · Jewelry & Artistic Items · Other Applications · Automotive · Industrial · Equipment & Machines · Goods & Material · Healthcare · Implants · Dental · Medical Devices · Aerospace & Defense · Prototype · Body & Spare Parts · Energy · Construction · Other End Users |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Italy, Spain, Russia, Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Rest of Asia-Pacific), Latin America (Brazil, Mexico, Rest of Latin America), and the Middle East & Africa (Israel, UAE, Rest of Middle East & Africa). |
| Key Companies | Markforged, Inc. (U.S.), Sculpteo (France), Stratasys Ltd. (U.S.), Evonik Industries AG (Germany), Zortrax (Poland), 3D Systems, Inc. (U.S.), Proto Labs, Inc. (U.S.), MATERIALISE NV (Belgium), The ExOne Company (U.S.), IC3D, Inc. (U.S.), Desktop Metal, Inc. (U.S.), EOS GmbH (Germany), Tethon3D (U.S.), Lithoz GmbH (Germany), and Formlabs (U.S.). |
Report overview
Segments covered: type, form, technology. Regions: North America, Europe, Asia-Pacific, Latin America.
The growth of this market is driven by the growing demand for polymers in 3D printing applications, organizations' increasing focus on product development and prototyping, and government initiatives supporting the adoption of 3D printing technologies. However, the high costs of 3D printing material restrain the growth of this market.
The growth of this segment is attributed to the rising use of electron beam melting (EBM) technology for metals and the increasing adoption of EBM 3D printing technology in the aerospace, motorsports, and medical industries to produce turbine blades and engine parts, medical implants, and prostheses.
Report infographic
Market dynamics
1 factors across 1 forceGrowing Demand for Polymers in 3D Printing Applications is Expected to Drive 3D Printing Materials Market
Polymers are the most widely used 3D printing material as they serve applications such as the fabrication of high-tech industrial (aerospace, medical/dental, automotive, and electronics) and consumer (home, fashion, and entertainment) products. Advancements in polymeric material continue to offer new possibilities for manufacturing industries. In addition, prototyping remains one of the primary application areas of polymer 3D printing. The recyclability and reusability of 3D printing polymers have encouraged many industries to develop in-house additive manufacturing (AM) capabilities.
3D printing with polymers helps businesses reduce the cost of manufacturing by eliminating the need for tooling and assembly. Polymers can be easily blended with other material to manufacture high-performance engineering products. The companies are focusing on the advancement of polymer for the application of 3D printing. For instance, in March 2024, HP Inc. (U.S.) launched a new polymer material, HP 3D HR PA 12 S, enabled by Arkema (France), establishing a new benchmark in surface finish with a lower cost per part. The new PA 12 S material sets the standard for surface aesthetics while reducing costs for customers using HP’s Jet Fusion 5200 Series 3D printing solutions.
In addition, companies operating in the 3D printing market are also focusing on the development of polymer 3D printing technology. For instance, in October 2023 , Desktop Metal, Inc. (U.S.) launched the ETEC Pro XL — an Industrial Polymer 3D Printer that delivers extreme accuracy, resolution, and surface finish in a large build area with high throughput speeds. Additional updates to ETEC Pro XL include a 4K ultra-high-definition projector and proven HyperPrint technology for continuous, isotropic printing. Thus, advancements in polymer-based 3D printing technologies and the growing use of polymers for 3D printing applications across various industries are expected to boost the growth of the 3D printing material market during the forecast period.
Table of contents
12 chapters · 141 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | — | — |
| By Form | — | — |
| Other segments | Growth of this | — |
By Type
- The Ceramics & Composites Segment is Expected to Register Highest CAGR
- The growth of this segment is attributed to the rising adoption of ceramic material for 3D printing vases, bowls, sculptures, and other artistic items and the increasing use of composite material in 3D printing processes to produce parts and components with improved strength and durability.
- Moreover, several companies are focusing on advancing ceramic 3D printing.
- For instance, in February 2024, Lithoz GmbH (Austria) established a technology network to advance ceramic 3D printing.
- The network will consist of an initial three Japanese ceramic companies: AS ONE (Japan), Mitsui Kinzoku ACT (Japan), and Yugyokuen Ceramics (Japan).
By Form
- The Filament Segment is Expected to Register Highest CAGR
- The growth of this segment is attributed to the growing use of 3D printing filaments for manufacturing commercial and military aircraft and the increasing use of filament material for the application of prototyping.
- Moreover, several key players are focusing on the development of material in filament form for the 3D printing of medical implants.
- For instance, in October 2023 , Evonik Industries AG (Germany) launched a new carbon-fiber-reinforced PEEK filament, which the company claims is the 'world's first' for use in 3D printed medical implants.
Other segments
- The Industrial Segment is Expected to Register the Highest CAGR
- The growth of this segment is attributed to the growing use of 3D printing for mass production in industrial manufacturing, the increasing focus of manufacturers on reducing cost and lead times, and the increasing use of 3D-printed composite material in industrial applications.
- In addition, manufacturing companies are increasing the use of 3D printing.
- For instance, in November 2023 , Velo3D, Inc. (U.S.) announced that Atomic Industries (U.S.) purchased a fully integrated metal additive manufacturing solution to provide its customers with 3D-printed tooling and dies.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of the global 3D printing material market. The large market share of this segment is attributed to the presence of key market players in the region and the growing demand for customized 3D-printed products in the region across the healthcare, consumer electronics, aerospace & defense, and automotive sectors; growing adoption of industrialization 4.0, and increasing collaborations and investments by enterprises for the development of advanced 3D printing & its material. For instance, in October 2023 , 3D Systems, Inc. (U.S.) launched its new MJP 300W 3D printer and VisiJet Wax Jewel Ruby material. North America: Largest Regional Market
Asia-Pacific
Fastest growthMoreover, Asia-Pacific is expected to record the highest CAGR during the forecast period. Several companies in this region are installing automated storage systems to optimize space use and cut unnecessary rental costs. For instance, in August 2021, Neoperl Group AG (Switzerland), an international company with global production and sales locations, implemented Swisslog Holding AG (Switzerland) AutoStore automated solution at its site in China. The modular design, high-density storage, and flexible robotic systems are the main factors that have attracted Neoperl operations in China.
Competitive landscape
Some of the key players operating in the 3D printing material market are Markforged, Inc. (U.S.), Sculpteo (France), Stratasys Ltd. (U.S.), Evonik Industries AG (Germany), Zortrax (Poland), 3D Systems, Inc. (U.S.), Proto Labs, Inc. (U.S.), MATERIALISE NV (Belgium), The ExOne Company (U.S.), IC3D, Inc. (U.S.), Desktop Metal, Inc. (U.S.), EOS GmbH (Germany), Tethon3D (U.S.), Lithoz GmbH (Germany), and Formlabs (U.S.).
- Markforged, Inc. (U.S.)
- Sculpteo · France
- Stratasys Ltd. (U.S.)
- Evonik Industries AG · Germany
- Zortrax · Poland
- 3D Systems, Inc. (U.S.)
- Proto Labs, Inc. (U.S.)
- MATERIALISE NV · Belgium
- ExOne Company (U.S.)
- IC3D, Inc. (U.S.)
- Desktop Metal, Inc. (U.S.)
- EOS GmbH · Germany
- Tethon3D (U.S.)
- Lithoz GmbH · Germany
- Formlabs (U.S.)
Frequently asked questions
The global 3D printing material market is projected to reach $11.08 billion by 2031, at a CAGR of 23.8% during the forecast period.
Cite this report
Meticulous Research. (2024). 3D Printing Materials Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRCHM - 104384). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/3d-printing-material-market-5083