Protein Bar Market (2026-2036)
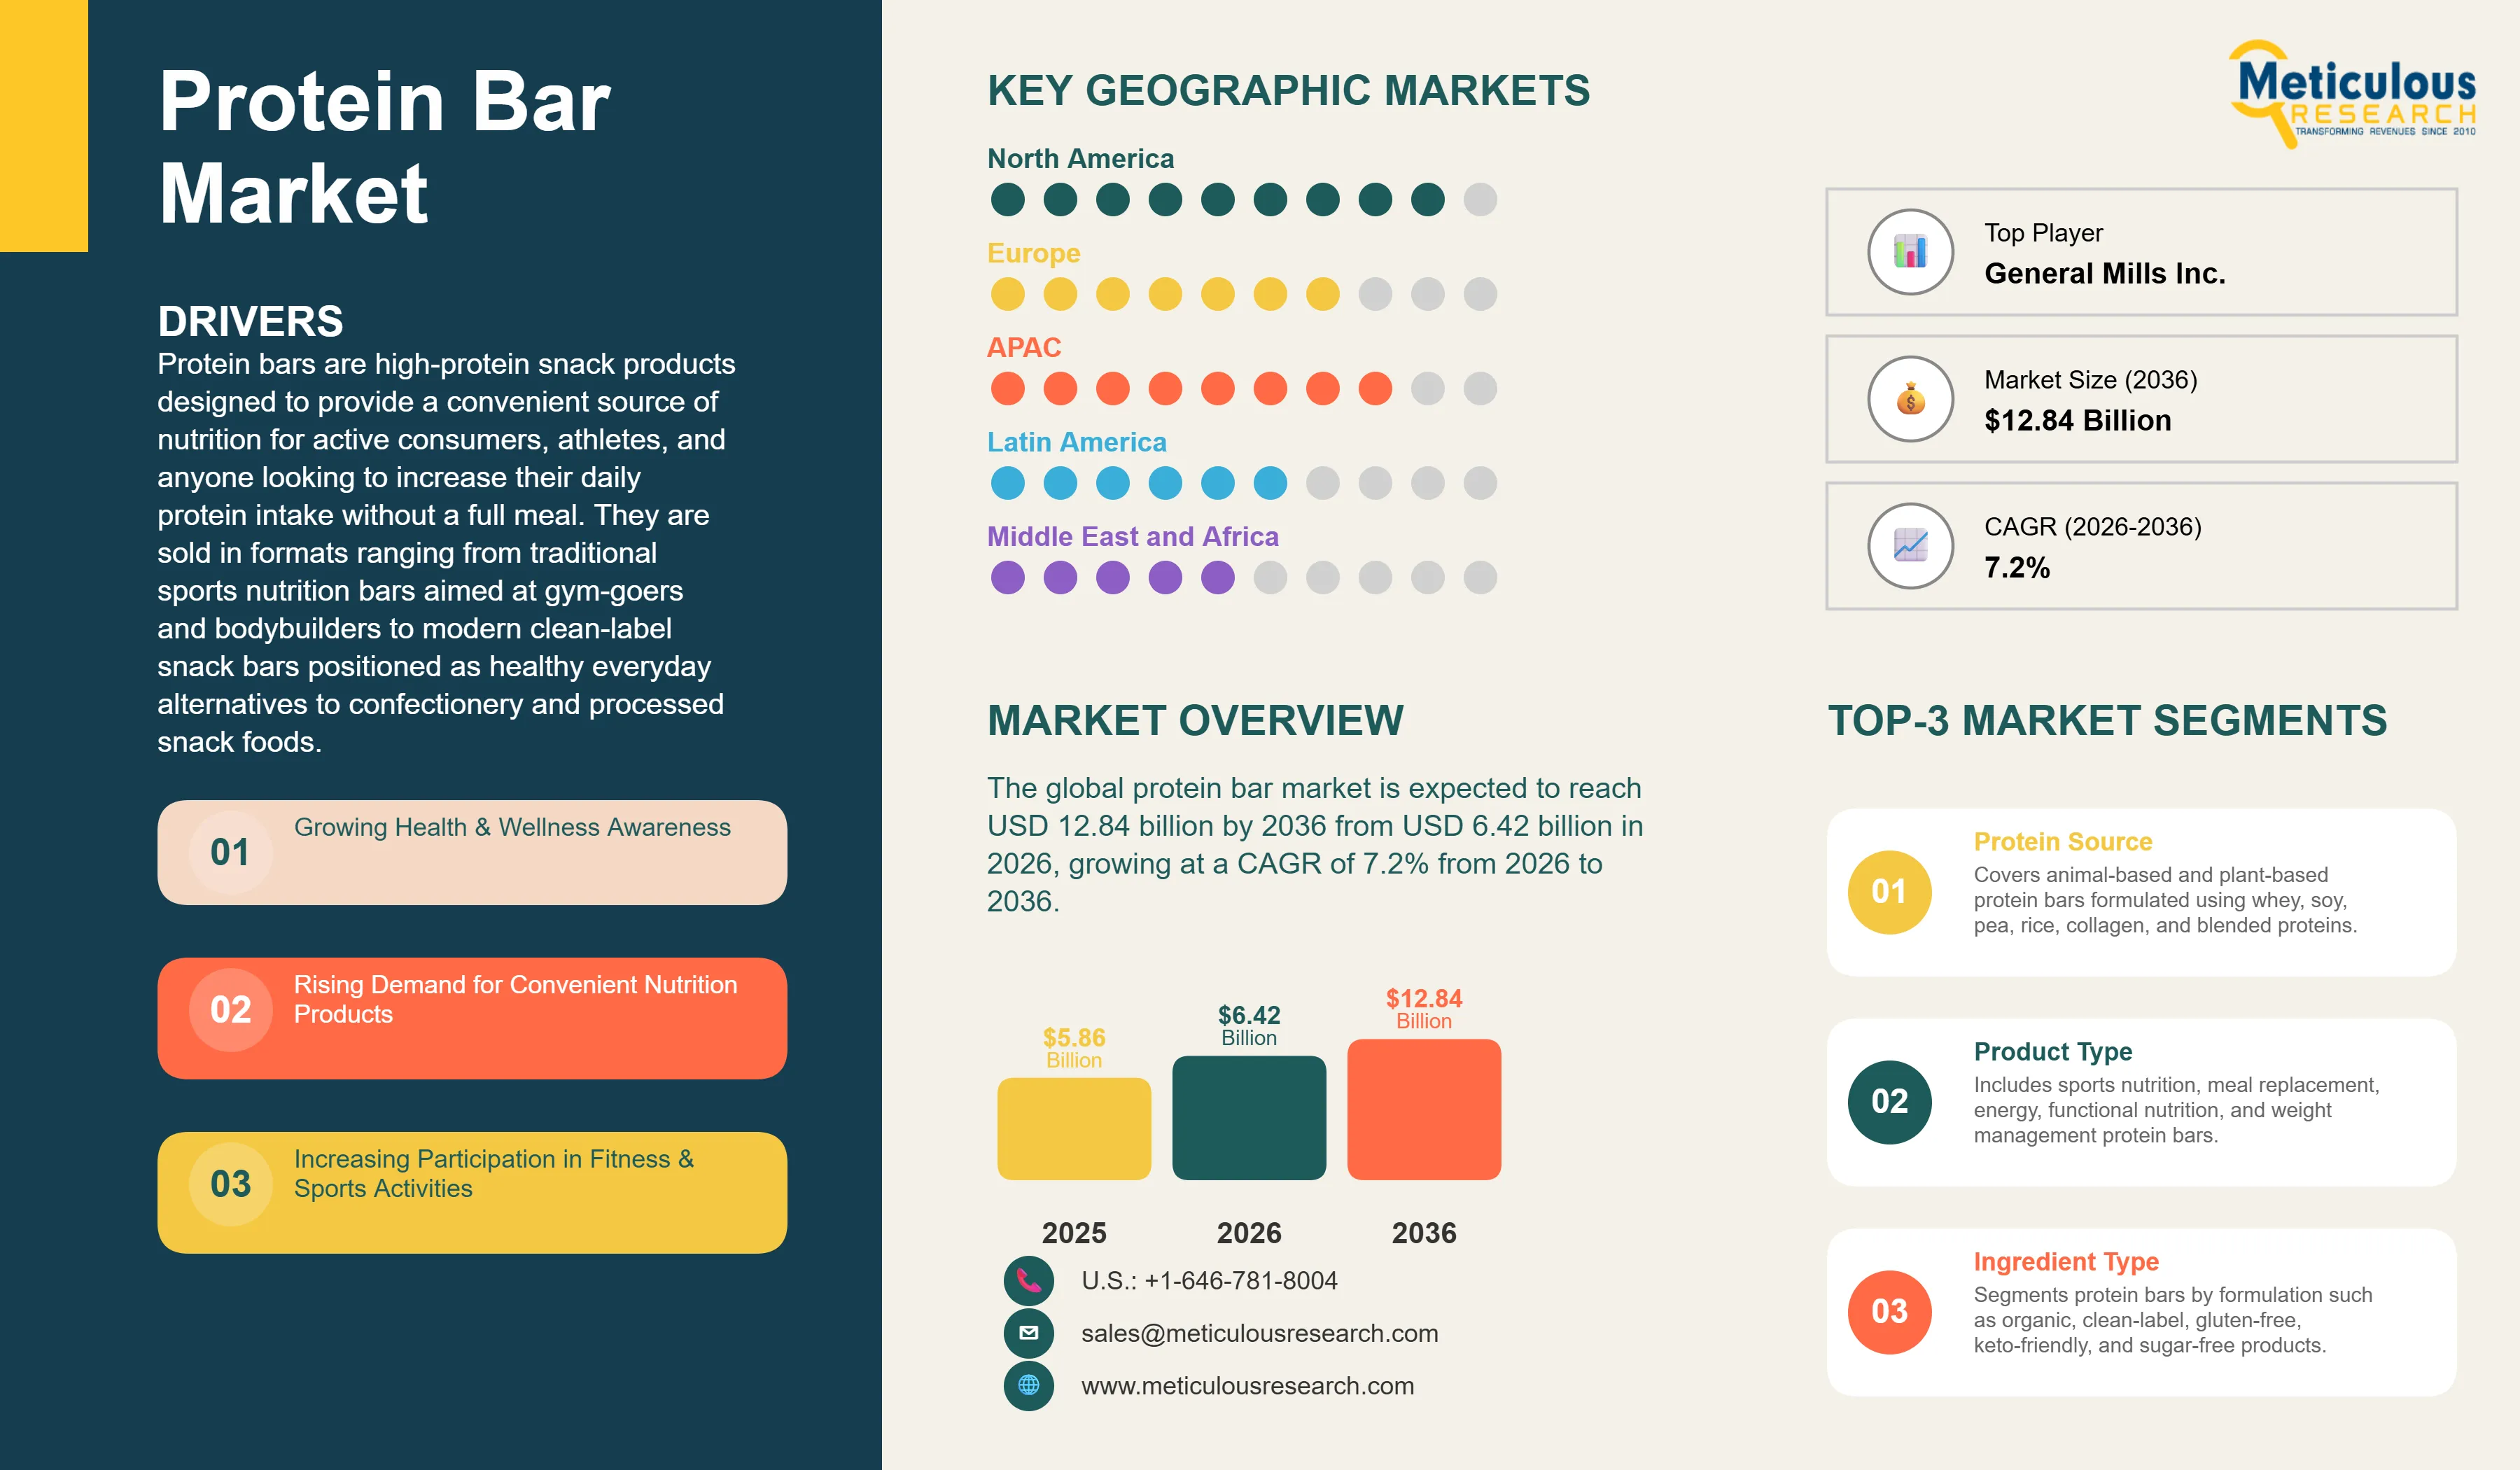
The global protein bar market was valued at USD 5.86 billion in 2025. This market is expected to reach USD 12.84 billion by 2036 from USD 6.42 billion in 2026, growing at a CAGR of 7.2% from 2026 to 2036.
- Published
- May 2026
- Pages
- 291
- Format
- PDF + Excel
- Report ID
- MR-2000
- Base year
- 2025
- 2025 · BASELINE
- $5.86B
- 2036
- $12.84B
- CAGR 2026–2036
- 7.2%
2025 baseline · 2026–2036 forecast at 7.2% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global protein bar market is projected to reach USD 12.84 billion by 2036.
The market is expected to grow at a CAGR of 7.2% from 2026 to 2036.
North America is expected to dominate the global protein bar market with the largest market share in 2026, driven by the high consumer awareness of protein nutrition, the mature sports supplement retail infrastructure, and the strong presence of leading brands including Quest Nutrition, RXBAR, Clif Bar, and ONE Bar across mass retail, specialty nutrition, and online channels.
Asia-Pacific is expected to witness the fastest growth during the forecast period, driven by the rapid expansion of gym and fitness culture in China, India, South Korea, and Australia, rising disposable incomes, growing awareness of protein nutrition among young urban consumers, and the expansion of international protein bar brands into the region through e-commerce.
By protein source, the animal-based protein bars segment is expected to hold the largest share of the overall protein bar market in 2026, as whey protein remains the preferred ingredient for sports nutrition bars due to its high bioavailability, complete amino acid profile, and established consumer trust among gym-goers and athletes.
By protein source, the plant-based protein bars segment is expected to witness the fastest growth during the forecast period, driven by growing consumer interest in vegan, flexitarian, and environmentally conscious diets that are shifting purchasing away from whey-based products toward bars made from pea, soy, rice, and blended plant protein sources.
By product type, the sports nutrition bars segment is expected to hold the largest share of the overall protein bar market in 2026, as this was the original product format that established the category and continues to generate the highest volume sales through specialty nutrition stores, gym retail, and online sports nutrition channels.
By ingredient type, the clean-label protein bars segment is expected to witness the fastest growth during the forecast period, as consumers increasingly seek products with short, recognizable ingredient lists and no artificial sweeteners, colors, or preservatives, a trend that brands including RXBAR, Larabar, and Aloha have commercialized successfully.
By distribution channel, the online retail and e-commerce segment is expected to witness the fastest growth during the forecast period, driven by the convenience of subscription-based purchasing, the ability to access a wider product range than physical retail offers, and the direct-to-consumer strategies of newer protein bar brands that bypass traditional retail entirely.
By application, the sports and fitness nutrition segment is expected to hold the largest share of the overall protein bar market in 2026, as protein bars were originally developed for this use case and still derive the largest share of their volume from gym-going and active consumers who use them as pre-workout, post-workout, or training day snacks.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 12.84 Billion |
| Market Size in 2026 | USD 6.42 Billion |
| Market Size in 2025 | USD 5.86 Billion |
| Market Growth Rate (2026-2036) | CAGR of 7.2% |
| Format | PDF, Excel & Cloud Portal · 291 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Protein Source, Product Type, Ingredient Type, Distribution Channel, Application, End User, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: protein source, ingredient type, distribution channel, application, end user.
Protein bars are high-protein snack products designed to provide a convenient source of nutrition for active consumers, athletes, and anyone looking to increase their daily protein intake without a full meal. They are sold in formats ranging from traditional sports nutrition bars aimed at gym-goers and bodybuilders to modern clean-label snack bars positioned as healthy everyday alternatives to confectionery and processed snack foods. The market has broadened significantly over the past decade as brands have moved beyond the niche sports nutrition channel into mass retail, convenience stores, and online subscription services, reaching a much wider consumer base.
The growth of this market is supported by clear and widely documented public health trends. According to the CDC, only one in four U.S. adults fully meets the physical activity guidelines for both aerobic and muscle-strengthening activity. The CDC notes that about one in two U.S. adults lives with a chronic disease and that getting enough physical activity could prevent many of these conditions. This large gap between recommended and actual physical activity levels creates a consumer base that is health-conscious but time-poor, making convenient, nutritious, on-the-go food products such as protein bars an appealing practical option. At the same time, CDC’s updated Adult Obesity Prevalence Maps (2024), every U.S. state and territory had an adult obesity prevalence of at least 25%, meaning at least one in four adults was living with obesity in each state. This drives growing consumer interest in high-protein snack products that support weight management and a higher-protein dietary approach.
Protein bars are manufactured food products containing elevated protein content, typically between 10 and 30 grams per bar, derived from one or more protein sources including whey, casein, soy, pea, rice, or collagen. They are sold in bar form as a portable, shelf-stable, and ready-to-eat alternative to other high-protein food sources such as chicken breast, eggs, or protein shakes. The product category spans a wide range of formulations and positioning, from high-protein, low-sugar sports performance bars aimed at competitive athletes through to more mainstream snack bars with 10 to 15 grams of protein that are positioned as a healthier alternative to candy bars and biscuits for everyday health-conscious consumers.
The category has gone through significant evolution over the past two decades. Early protein bars were heavily associated with bodybuilding and sports nutrition and were sold primarily through specialist supplement retailers. They were often criticized for poor taste, high sugar content, or the inclusion of artificial sweeteners and additives. The commercial breakthrough of brands including Quest Nutrition, which launched in 2010 with a formula based on high protein content, fiber, and minimal sugar using sugar alcohols as sweeteners, showed that consumers would prioritize nutritional profiles over traditional confectionery taste profiles. RXBAR's 2012 launch with a minimal ingredient list displayed prominently on the packaging established the clean-label format as a major commercial direction. These innovations shifted protein bars from a niche supplement product into a mainstream functional food category sold in supermarkets, convenience stores, and coffee chains alongside conventional snacks.
The competitive landscape of the protein bar market is a mix of large food companies that have entered through acquisition, specialist nutrition brands, and newer direct-to-consumer entrants. Mars Incorporated owns the ONE Bar and KIND Protein Bar brands. General Mills owns EPIC. Kellanova owns RXBAR. Nestle and Glanbia each have strong positions through their nutrition divisions. Quest Nutrition, the market leader by volume in the U.S. premium protein bar segment, is owned by The Simply Good Foods Company. Grenade from the UK and Barebells from Sweden have built strong brand followings in European markets and are expanding internationally. David Protein, founded in 2024 and positioning itself on an exceptionally high protein-to-calorie ratio, represents the newer generation of entrants competing aggressively on nutritional credentials rather than taste profile.
Market dynamics
4 factors across 3 forcesGrowing Consumer Focus on Health, Fitness, and High-protein Diets
The most important driver of the protein bar market is the growing number of consumers who are actively paying attention to their dietary protein intake and seeking convenient ways to meet their daily protein targets without cooking or meal preparation. According to the CDC's About Physical Activity page updated in August 2025, only one in four U.S. adults fully meets both the aerobic and muscle-strengthening components of the physical activity guidelines. The CDC's Active People, Healthy Nation initiative is working to help 27 million Americans become more physically active by 2027. As more people engage in strength training, running, cycling, and other fitness activities, awareness of protein's role in muscle repair, recovery, and maintenance increases, driving demand for convenient high-protein food products that can be consumed immediately after exercise or as part of a fitness-focused dietary routine.
The obesity data also supports this demand. According to the CDC's Adult Obesity Prevalence Maps updated in December 2025, in 2024 all U.S. states and territories had an adult obesity prevalence of 25% or higher, and at least one in five adults in every U.S. state is living with obesity. This large population of weight-management-focused consumers creates significant demand for protein-rich snack options that are more satiating than carbohydrate-heavy conventional snacks, support lean muscle mass during calorie-restricted diets, and fit into popular dietary frameworks including high-protein, low-carb, and ketogenic eating plans that have become mainstream consumer weight management approaches.
Table of contents
14 chapters · 163 sections · 291 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Protein Source | Animal-based Protein Bars | Plant-based protein bars |
| By Product Type | Sports Nutrition Bars | Functional nutrition bars |
| By Ingredient Type | Conventional Protein Bars | Clean-label protein bars |
| By Distribution Channel | Supermarkets and Hypermarkets | Online retail and e-commerce |
| By Application | Sports and Fitness Nutrition | General wellness and healthy snacking |
| By End User | Athletes and Bodybuilders | Lifestyle and wellness consumers |
By Protein Source
- The animal-based protein bars segment is expected to hold the largest share of the protein bar market.
- Whey protein, which is derived from milk as a byproduct of cheese production, is the most widely used ingredient in protein bars.
- It is valued by consumers and formulation scientists for its high protein concentration, complete amino acid profile including all nine essential amino acids, fast absorption rate that supports post-workout muscle recovery, and relatively neutral flavor that is easy to work with in bar formulations.
- Whey protein's decades of use in sports nutrition and the large body of research supporting its effectiveness for muscle protein synthesis have established it as the default protein source for sports nutrition bars.
- Major brands including Quest Nutrition, Grenade, and Barebells base their core products on whey protein or combinations of whey and casein.
- Casein protein, also derived from milk, is slower digesting than whey and is used in bars marketed for overnight muscle recovery or as a more sustained protein source between meals.
- Collagen protein, which has grown significantly in use as a functional protein ingredient in bars marketed for skin, hair, joint, and gut health, is another animal-based protein source gaining commercial traction outside traditional sports nutrition.
- However, the plant-based protein bars segment is expected to witness the fastest growth during the forecast period.
- Pea protein, soy protein, rice protein, and blended plant protein formulations are being adopted by a growing range of brands serving vegan, flexitarian, and allergy-conscious consumers.
- Pea protein has become the most popular plant-based protein in bars because it provides high protein content, neutral flavor, and good texture in finished bars, with fewer allergen concerns than soy.
- Aloha Foods, Garden of Life, and Orgain are among the leading brands competing in this segment.
By Product Type
- The sports nutrition bars segment is expected to hold the largest share of the protein bar market by product type.
- Sports nutrition bars were the original form of the protein bar category and continue to generate the largest revenue share through their strong presence in specialty nutrition retail, online sports nutrition channels, and gym retail.
- These products are typically formulated with 20 grams or more of protein, low sugar content, and specific macronutrient profiles designed to support athletic performance, muscle building, or post-exercise recovery.
- Quest Bar, the leading product in this segment in the U.S. market, built its reputation on a 20-gram protein, high-fiber, low-sugar formulation that appealed directly to gym-going consumers seeking a guilt-free high-protein snack.
- Grenade's Carb Killa bar has achieved a similar position in the UK and European markets.
- However, the functional nutrition bars segment is expected to witness the fastest growth during the forecast period.
- Functional bars go beyond protein content to include additional active ingredients such as probiotics, adaptogens, collagen, vitamins, or botanical extracts that address specific health goals beyond muscle building.
- This product format is appealing to a broader consumer base that includes wellness-focused buyers who are not primarily motivated by sports performance but want their snacks to contribute to digestive health, stress management, skin health, or immune function.
- The functional bar format commands higher retail prices than standard sports bars, supporting revenue growth even at moderate volume growth rates.
By Ingredient Type
- The conventional protein bars segment is expected to hold the largest share of the protein bar market by ingredient type.
- Conventional protein bars using standard food-grade ingredients including whey protein concentrate, sugar alcohols such as maltitol and erythritol, artificial sweeteners, and standard binding agents represent the broadest product base in the market and include the highest-volume selling products including Quest Bar, ONE Bar, and Grenade Carb Killa.
- These products are widely available across all distribution channels and have the lowest retail price points within the protein bar category, making them accessible to the largest number of buyers.
- However, the clean-label protein bars segment is expected to witness the fastest growth during the forecast period.
- Clean-label products that use short, transparent ingredient lists with recognizable whole food ingredients, and that avoid artificial sweeteners, synthetic preservatives, and modified food starches, are attracting the highest price premiums in the market and commanding premium shelf placement.
- The FDA's food labeling regulations require brands to list all ingredients in descending order of weight, enabling consumers to directly compare ingredient quality across products, which clean-label brands exploit commercially by making their short ingredient lists a front-of-pack marketing feature.
By Distribution Channel
- The supermarkets and hypermarkets segment is expected to hold the largest share of the protein bar market by distribution channel.
- The expansion of protein bars from specialist nutrition retailers into mainstream supermarket shelves is one of the defining commercial developments of the past decade, bringing the category to the much larger consumer population that shops for everyday groceries at Walmart, Kroger, Tesco, Carrefour, and similar mass retail chains.
- Brands that achieved supermarket distribution including Quest, RXBAR, Kind, and Clif Bar accessed significantly larger consumer volumes than were available through specialist channels alone.
- Supermarket shelf placement in the snack or health food aisle puts protein bars in front of millions of shoppers who were not actively looking for a protein supplement product but find it a convenient and appealing snack option when confronted with it alongside conventional bars and biscuits.
- However, the online retail and e-commerce segment is expected to witness the fastest growth during the forecast period.
- Online purchasing of protein bars is growing rapidly as consumers appreciate the price advantages of buying in bulk, the wider product variety available compared with physical retail, and the convenience of home delivery.
- Amazon is the largest single online retailer for protein bars in North America, and brand-owned DTC websites are growing in importance as brands invest in direct consumer relationships.
- Subscription box services for protein bars and nutrition products are also expanding.
- The FDA's food labeling requirements apply equally to online product listings, and brands selling through Amazon and other online platforms must ensure their product pages accurately reflect ingredients and nutritional content, maintaining the same transparency standards as physical retail.
By Application
- The sports and fitness nutrition segment is expected to hold the largest share of the protein bar market by application.
- Protein bars were created for athletes and fitness enthusiasts and this consumer base remains the core of the market.
- According to the CDC's Active People, Healthy Nation initiative, the CDC is working to help 27 million additional Americans become more physically active by 2027, with physical activity participation already substantial across the U.S. population.
- Every person who participates in regular gym, running, cycling, or team sport activity is a potential consumer of sports nutrition bars as a convenient way to meet elevated protein requirements without meal preparation.
- The sports fitness application benefits from clear, well-understood consumer motivation: protein supports muscle recovery and growth, and bars provide that protein in a format that can be eaten immediately after a workout without refrigeration or preparation.
- However, the general wellness and healthy snacking segment is expected to witness the fastest growth during the forecast period.
- The expansion of protein bars into mainstream snacking is converting a much larger population of non-athlete consumers who simply want a more nutritious, more satiating alternative to conventional biscuits, chocolate bars, and crisps.
- These consumers are not primarily motivated by sports performance but by general health consciousness, weight management interest, or a preference for snacks with a better nutritional profile.
- This broader wellness application represents a much larger potential consumer base than the sports nutrition segment alone, and brands that successfully position their products for everyday snacking rather than just post-workout use are accessing this larger opportunity.
By End User
- The athletes and bodybuilders segment is expected to hold the largest share of the protein bar market by end user.
- This group has the highest per-capita protein bar consumption, buys the most frequently, has the strongest brand loyalty to specialist sports nutrition brands, and is willing to pay the highest prices for products with strong nutritional credentials.
- Athletes and bodybuilders are also the most knowledgeable buyers, reading ingredient labels and nutritional panels carefully and making purchasing decisions based on protein content, amino acid profile, and macronutrient ratios.
- Their buying behavior is less sensitive to price per bar than other consumer segments, and they are more likely to purchase in bulk packs of 12, 24, or even larger box formats rather than single bars.
- However, the lifestyle and wellness consumers segment is expected to witness the fastest growth during the forecast period.
- This is the largest and fastest-growing end-user group by head count, encompassing the broad population of health-conscious consumers who have begun eating protein bars as part of a general effort to improve their diet, manage their weight, or simply make better snacking choices.
- According to the CDC's obesity data, at least one in five adults in every U.S. state is living with obesity, and broader weight management interest extends well beyond the clinically obese population to a large group of consumers who are actively managing their diet and snack choices.
- This lifestyle wellness consumer group is accessible through supermarkets, convenience stores, online channels, and increasingly coffee shops and petrol station forecourts, making it the most commercially broad and commercially important growth end-user segment for the protein bar market over the forecast period.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to hold the largest share of the global protein bar market. The United States is by far the largest individual market, with the highest per-capita consumption of protein bars globally, the most developed sports nutrition retail infrastructure, and the deepest brand portfolio in the category. The U.S. market benefits from a large, fitness-conscious consumer population and a well-established retail ecosystem that includes specialist sports nutrition chains such as GNC and Vitamin Shoppe alongside mainstream supermarkets and convenience stores that carry a wide range of protein bar brands. According to the CDC, the CDC is actively working to increase physical activity participation among Americans through its Active People, Healthy Nation initiative targeting 27 million additional active Americans by 2027, and one in four U.S. adults currently meets the full physical activity guidelines for both aerobic and muscle-strengthening activity. The large and growing number of Americans who are engaged in regular physical activity, combined with the equally large number who are health-conscious but not currently meeting activity guidelines, collectively represents the largest national consumer base for protein bars globally. Canada contributes to regional demand through a similar fitness and health culture, with major U.S. protein bar brands widely available through Canadian retail channels.
Asia-Pacific
Fastest growthAsia-Pacific is expected to witness the highest growth rate in the protein bar market during the forecast period. This growth is driven by rapidly expanding gym culture and fitness participation in China, India, South Korea, and Australia, rising disposable incomes among young urban consumers, and the growing availability of protein bar products through e-commerce platforms and modern retail formats. China is the largest individual market in Asia-Pacific for protein bars, with a rapidly growing fitness and bodybuilding culture in major cities, a large young working population interested in health and wellness products, and major domestic e-commerce platforms providing easy access to both international and domestic protein bar brands. India's growing urban middle class, rapidly expanding gym network, and rising protein awareness among young consumers are creating a fast-growing protein supplement and protein snack market that international brands are beginning to address seriously. South Korea's highly developed health and beauty consumer culture, strong gym participation rates, and sophisticated e-commerce infrastructure make it one of the most commercially attractive markets in Asia-Pacific for premium protein bar brands. Australia has a well-established sports nutrition market with high per-capita fitness participation, and is a key market for brands including Grenade, Barebells, and international whey protein products.
Competitive landscape
- Quest Nutrition
- Mars Incorporated (ONE Brands, KIND Protein Bars)
- General Mills Inc. (EPIC Protein Bars)
- Simply Good Foods Company (Quest and Atkins)
- Nestle S.A.
- Clif Bar and Company
- Grenade (UK) Ltd.
- Barebells Functional Foods
- BellRing Brands Inc.
- Glanbia plc
- Herbalife Ltd.
- Abbott Laboratories
- RXBAR · Kellanova
- David Protein
- Aloha Foods Co
Frequently asked questions
The global protein bar market is expected to grow from USD 6.42 billion in 2026 to USD 12.84 billion by 2036.
Cite this report
Meticulous Research. (2026). Protein Bar Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-2000). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/reports/protein-bar-market-6683