Precision Bearings Market (2026-2036)
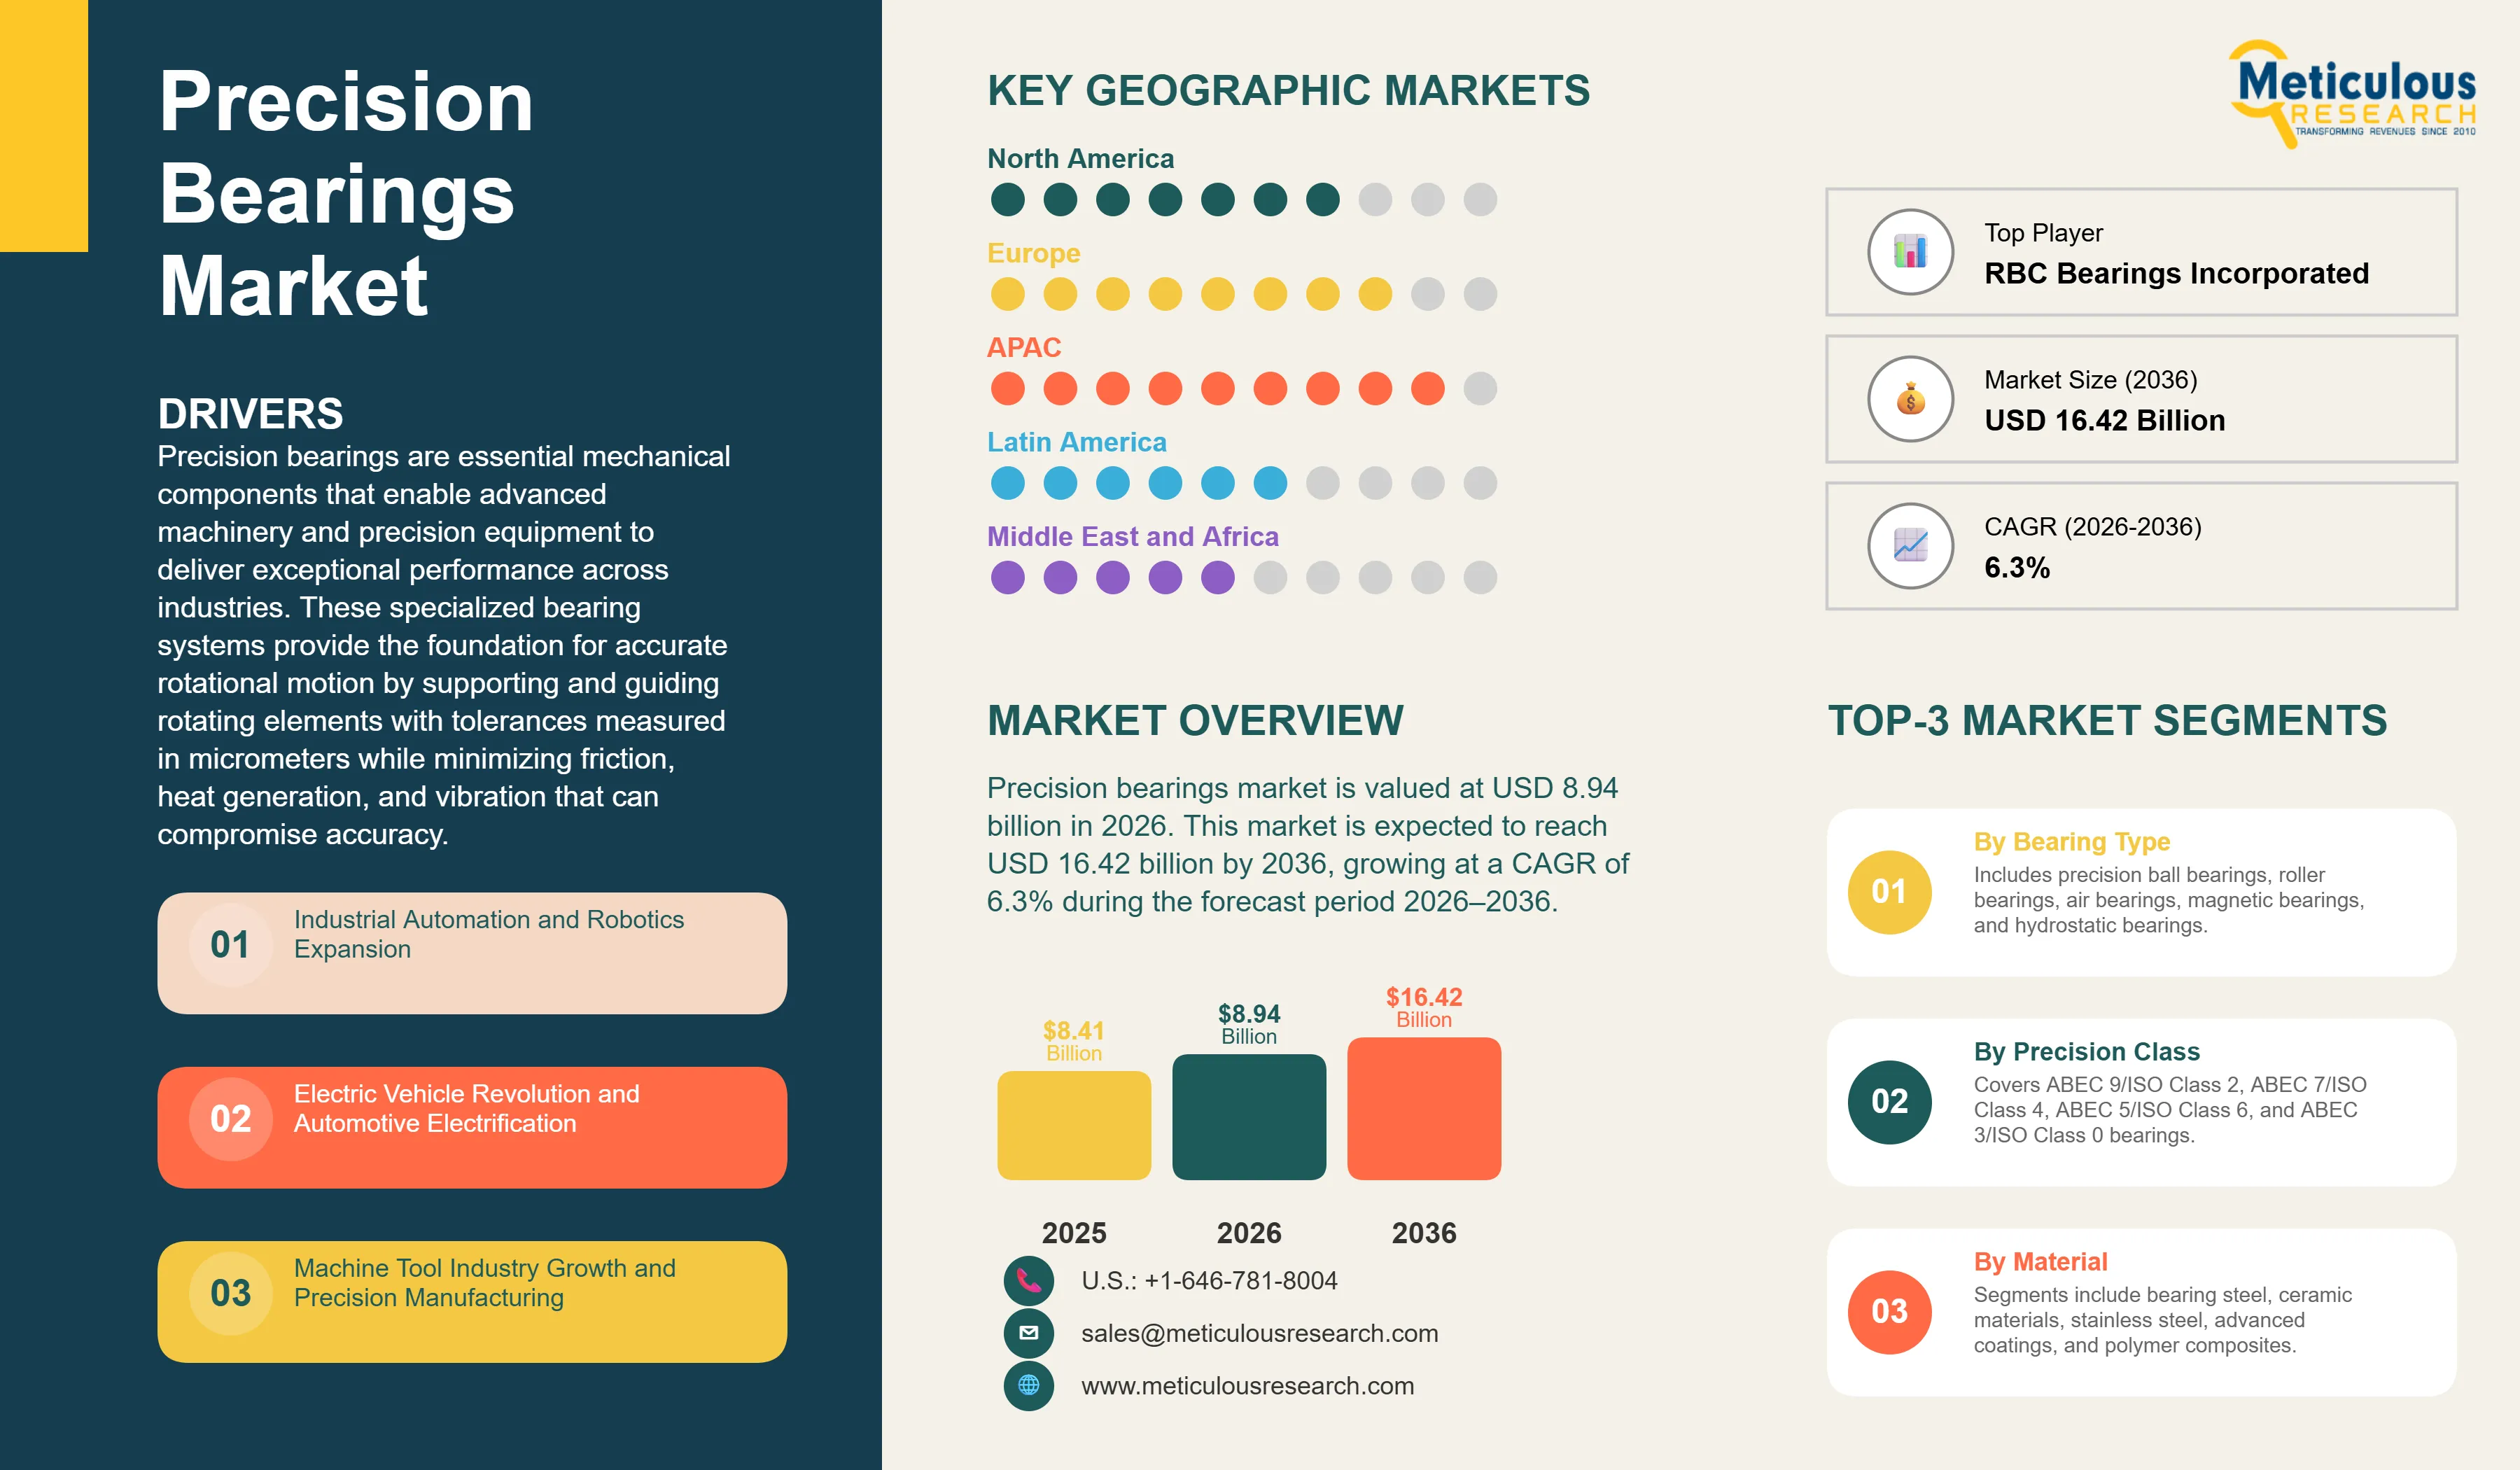
The global precision bearings market is valued at USD 8.94 billion in 2026. This market is expected to reach USD 16.42 billion by 2036, growing at a CAGR of 6.3% during the forecast period 2026–2036.
- Published
- Jan 2026
- Pages
- 273
- Format
- PDF + Excel
- Report ID
- MR-1679
- Base year
- 2025
- 2024 · HISTORICAL
- $627.6B
- 2036
- $16.42B
- CAGR 2026–2036
- 6.3%
2024–2025 baseline · 2026–2036 forecast at 6.3% CAGR · hover a bar for the value
Key highlights
In 2026, Asia-Pacific accounts for the largest share of the global precision bearings market, driven by massive machine tool production in China, Japan, and South Korea, strong industrial automation and robotics adoption, semiconductor manufacturing concentration, and presence of major bearing manufacturers including NSK, NTN, JTEKT, and Schaeffler.
Europe is projected to register a significant CAGR during the forecast period, fueled by advanced manufacturing sector requiring precision machinery, aerospace and automotive industries demanding high-performance bearings, Industry 4.0 initiatives, and strong presence of bearing technology leaders including SKF and Schaeffler.
Based on bearing type, the precision ball bearing segment holds the largest share of the market in 2026, driven by versatility across applications, superior high-speed capability, lower friction compared to roller bearings, and dominance in machine tool spindles, robotics, and aerospace applications.
Based on precision class, the ABEC 7 segment dominates the market in 2026, owing to optimal balance between precision performance and cost for majority of industrial applications including general machine tool spindles, industrial robots, and precision machinery.
Based on material, the bearing steel segment is expected to witness significant growth during the forecast period, driven by established performance characteristics, cost-effectiveness compared to ceramic alternatives, and continuous material improvements enhancing fatigue life and temperature resistance.
Based on application, the machine tool spindles segment accounts for the largest share of the market in 2026, fueled by precision machining requirements, growing CNC machine tool production, and demand for high-speed, high-precision metalworking capabilities.
The ceramic bearing segment is expected to grow at the highest CAGR during the forecast period, driven by superior performance in high-speed, high-temperature applications, electric vehicle motor requirements, and semiconductor manufacturing equipment demanding ultra-clean operation.
The U.S. precision bearings market is projected to grow at a CAGR of around 5% during the forecast period 2026 to 2036, driven by aerospace and defense applications, advanced manufacturing reshoring, medical device industry growth, and semiconductor fab expansion.
China is expected to lead the Asia-Pacific precision bearings market, driven by the world's largest machine tool production, massive industrial robot installations, semiconductor manufacturing expansion, and growing domestic bearing manufacturing capabilities.
In 2026, Germany is projected to account for the largest share of the European precision bearings market, driven by its advanced machine tool industry, strong automotive and aerospace sectors, precision engineering tradition, and headquarters of major bearing manufacturers including Schaeffler and SKF operations.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 8.94 Billion |
| Revenue Forecast in 2036 | USD 16.42 Billion |
| Growth Rate | CAGR of 6.3% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 273 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | Bearing Type, Precision Class, Material, Application, Industry Vertical, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Germany, U.K., France, Italy, Spain, Sweden, Japan, China, South Korea, Taiwan, India, Singapore, Brazil, Mexico, Saudi Arabia, UAE |
| Key Companies Profiled | NSK Ltd., SKF AB, Schaeffler Technologies AG & Co. KG, NTN Corporation, JTEKT Corporation, Timken Company, Minebea Mitsumi Inc., THK Co. Ltd., C&U Group, ZWZ Bearing Co. Ltd., LYC Bearing Corporation, GMN Paul Müller Industrie GmbH & Co. KG, Barden Precision Bearings (Schaeffler), RBC Bearings Incorporated, Kaydon Corporation (SKF), SNR Bearings (NTN), FAG (Schaeffler), IKO International Inc., Nachi-Fujikoshi Corp., Koyo Bearings (JTEKT) |
Report overview
Segments covered: bearing type, precision class, material, application.
Precision bearings are essential mechanical components that enable advanced machinery and precision equipment to deliver exceptional performance across industries. These specialized bearing systems provide the foundation for accurate rotational motion by supporting and guiding rotating elements with tolerances measured in micrometers while minimizing friction, heat generation, and vibration that can compromise accuracy. The challenge in precision machinery is maintaining highly accurate rotational performance under varying loads, speeds, and operating environments. Consequently, precision bearings are indispensable in applications ranging from submicron-accuracy machine tool spindles and nanometer-scale semiconductor manufacturing equipment to aerospace systems and industrial robots. According to the International Federation of Robotics (IFR), global industrial robot installations reached 553,000 units in 2022 and the active installed base exceeded 3.9 million units worldwide, creating substantial demand for high-precision bearings used in robotic joints, reducers, and motion-control systems. In addition, the Semiconductor Industry Association (SIA), citing World Semiconductor Trade Statistics (WSTS), reported that global semiconductor sales reached USD 627.6 billion in 2024, highlighting the expanding need for ultra-clean and vibration-free equipment used in wafer fabrication and inspection processes.
Several key trends are reshaping the precision bearings market. The industry is witnessing increasing adoption of hybrid and full ceramic bearing technologies, which provide superior speed capability, thermal stability, and corrosion resistance. Rising industrial automation and robotics are driving demand for smooth and highly precise motion-control systems, while expanding semiconductor manufacturing capacity is creating requirements for ultra-low vibration and contamination-free bearing solutions. The rapid electrification of the automotive sector is opening new opportunities for high-speed electric motors and transmission systems, and the emergence of smart bearings integrated with sensors is supporting condition monitoring and predictive maintenance. According to the International Federation of Robotics, annual robot installations are expected to exceed 700,000 units by 2027, reflecting accelerating automation across manufacturing industries. Meanwhile, smart bearing technologies are gaining momentum as manufacturers increasingly adopt Industry 4.0 practices to reduce downtime and improve operational efficiency. The convergence of stringent manufacturing requirements, rapid automation, advanced material technologies, and digitalization has transformed precision bearings from conventional mechanical components into strategic enablers of competitive advantage in precision manufacturing and high-technology applications.
Market dynamics
5 factors across 3 forcesIndustrial Automation and Robotics Expansion
The rapid growth of industrial automation and robotics is a key factor driving demand for precision bearings in manufacturing. According to the International Federation of Robotics (IFR), annual installations of industrial robots reached a record 553,000 units in 2022, and the global operational stock surpassed 4.2 million units in 2023. IFR forecasts suggest that yearly installations will keep increasing and could exceed 700,000 units by 2027. Industrial robots depend on precision bearings in joint mechanisms, speed reducers, wrists, linear axes, and end-effectors to provide accurate and repeatable motion. High-performance bearing types, like angular contact ball bearings and crossed roller bearings, are commonly used in harmonic drive and RV reducer systems to ensure stiffness, low friction, and minimal vibration. The large number of installed robots around the globe also creates ongoing demand for bearing replacement and maintenance throughout the equipment's lifecycle. The rising use of collaborative robots (cobots) is boosting demand for high-quality precision bearings. According to the International Federation of Robotics, cobots made up about 10.5% of all industrial robot installations in 2023, showing their increasing presence in electronics, automotive, logistics, and small-scale manufacturing. Because cobots are built to work safely alongside humans, they need smooth and highly precise motion, which places a greater focus on bearings that offer low friction, reduced vibration, and long-term reliability. Beyond robotics, the wider automation trend includes CNC machine tools, automated assembly systems, packaging machinery, semiconductor manufacturing equipment, and medical device production systems. All these rely on precision bearings for accurate motion control. The International Labour Organization (ILO) notes that many developed economies face aging workforces and labor shortages. This situation is accelerating investments in automation technologies. At the same time, manufacturers want greater productivity, improved quality, and safer operations in dangerous environments. These factors are driving ongoing investment in automation equipment, which is increasing the demand for precision bearing solutions.
Table of contents
15 chapters · 206 sections · 273 pages · click to expandGeographic analysis
Asia-Pacific
Largest shareAsia-Pacific is expected to hold the largest share of the global precision bearings market in 2026, supported by its strong presence in machine tools, industrial robotics, semiconductor manufacturing, and automotive production. China, Japan, and South Korea are major manufacturing hubs, while leading bearing producers such as NSK, NTN, JTEKT, Nachi-Fujikoshi, and MinebeaMitsui are headquartered in the region. According to the International Federation of Robotics (IFR), China possesses the world's largest installed base of industrial robots, while the region also accounts for a significant portion of global semiconductor fabrication capacity and EV production.
Europe
Europe is projected to grow at a healthy pace due to its advanced manufacturing base, strong automotive and aerospace industries, and emphasis on Industry 4.0 technologies. Germany remains the region's largest market, supported by its machine tool sector and the presence of major bearing manufacturers such as Schaeffler and SKF.
North America
North America represents an important market driven by aerospace and defense, medical devices, semiconductor manufacturing, and reshoring initiatives. Investments stimulated by the U.S. CHIPS and Science Act and expansion plans by Intel, TSMC, Samsung, and Micron are expected to strengthen demand for high-performance precision bearings in semiconductor equipment and advanced manufacturing applications.
Competitive landscape
- NSK Ltd. · Japan
- SKF AB · Sweden
- Schaeffler Technologies AG & Co. KG · Germany
- NTN Corporation · Japan
- JTEKT Corporation · Japan
- Timken Company (U.S.)
- Minebea Mitsumi Inc. · Japan
- THK Co. Ltd. · Japan
- C&U Group · China
- ZWZ Bearing Co. Ltd. · China
- LYC Bearing Corporation · China
- Barden Precision Bearings (Schaeffler) (U.S./Germany)
- RBC Bearings Incorporated (U.S.)
- Kaydon Corporation (SKF) (U.S.)
- SNR Bearings (NTN) · France
- FAG (Schaeffler) · Germany
- IKO International Inc. · Japan
- Nachi-Fujikoshi Corp. · Japan
- Koyo Bearings (JTEKT) · Japan
Frequently asked questions
The precision bearings market is expected to grow from USD 8.94 billion in 2026 to USD 16.42 billion by 2036.
Cite this report
Meticulous Research. (2026). Precision Bearings Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1679). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/reports/precision-bearings-market-6362