Wafer Processing Equipment Market (2026-2036)
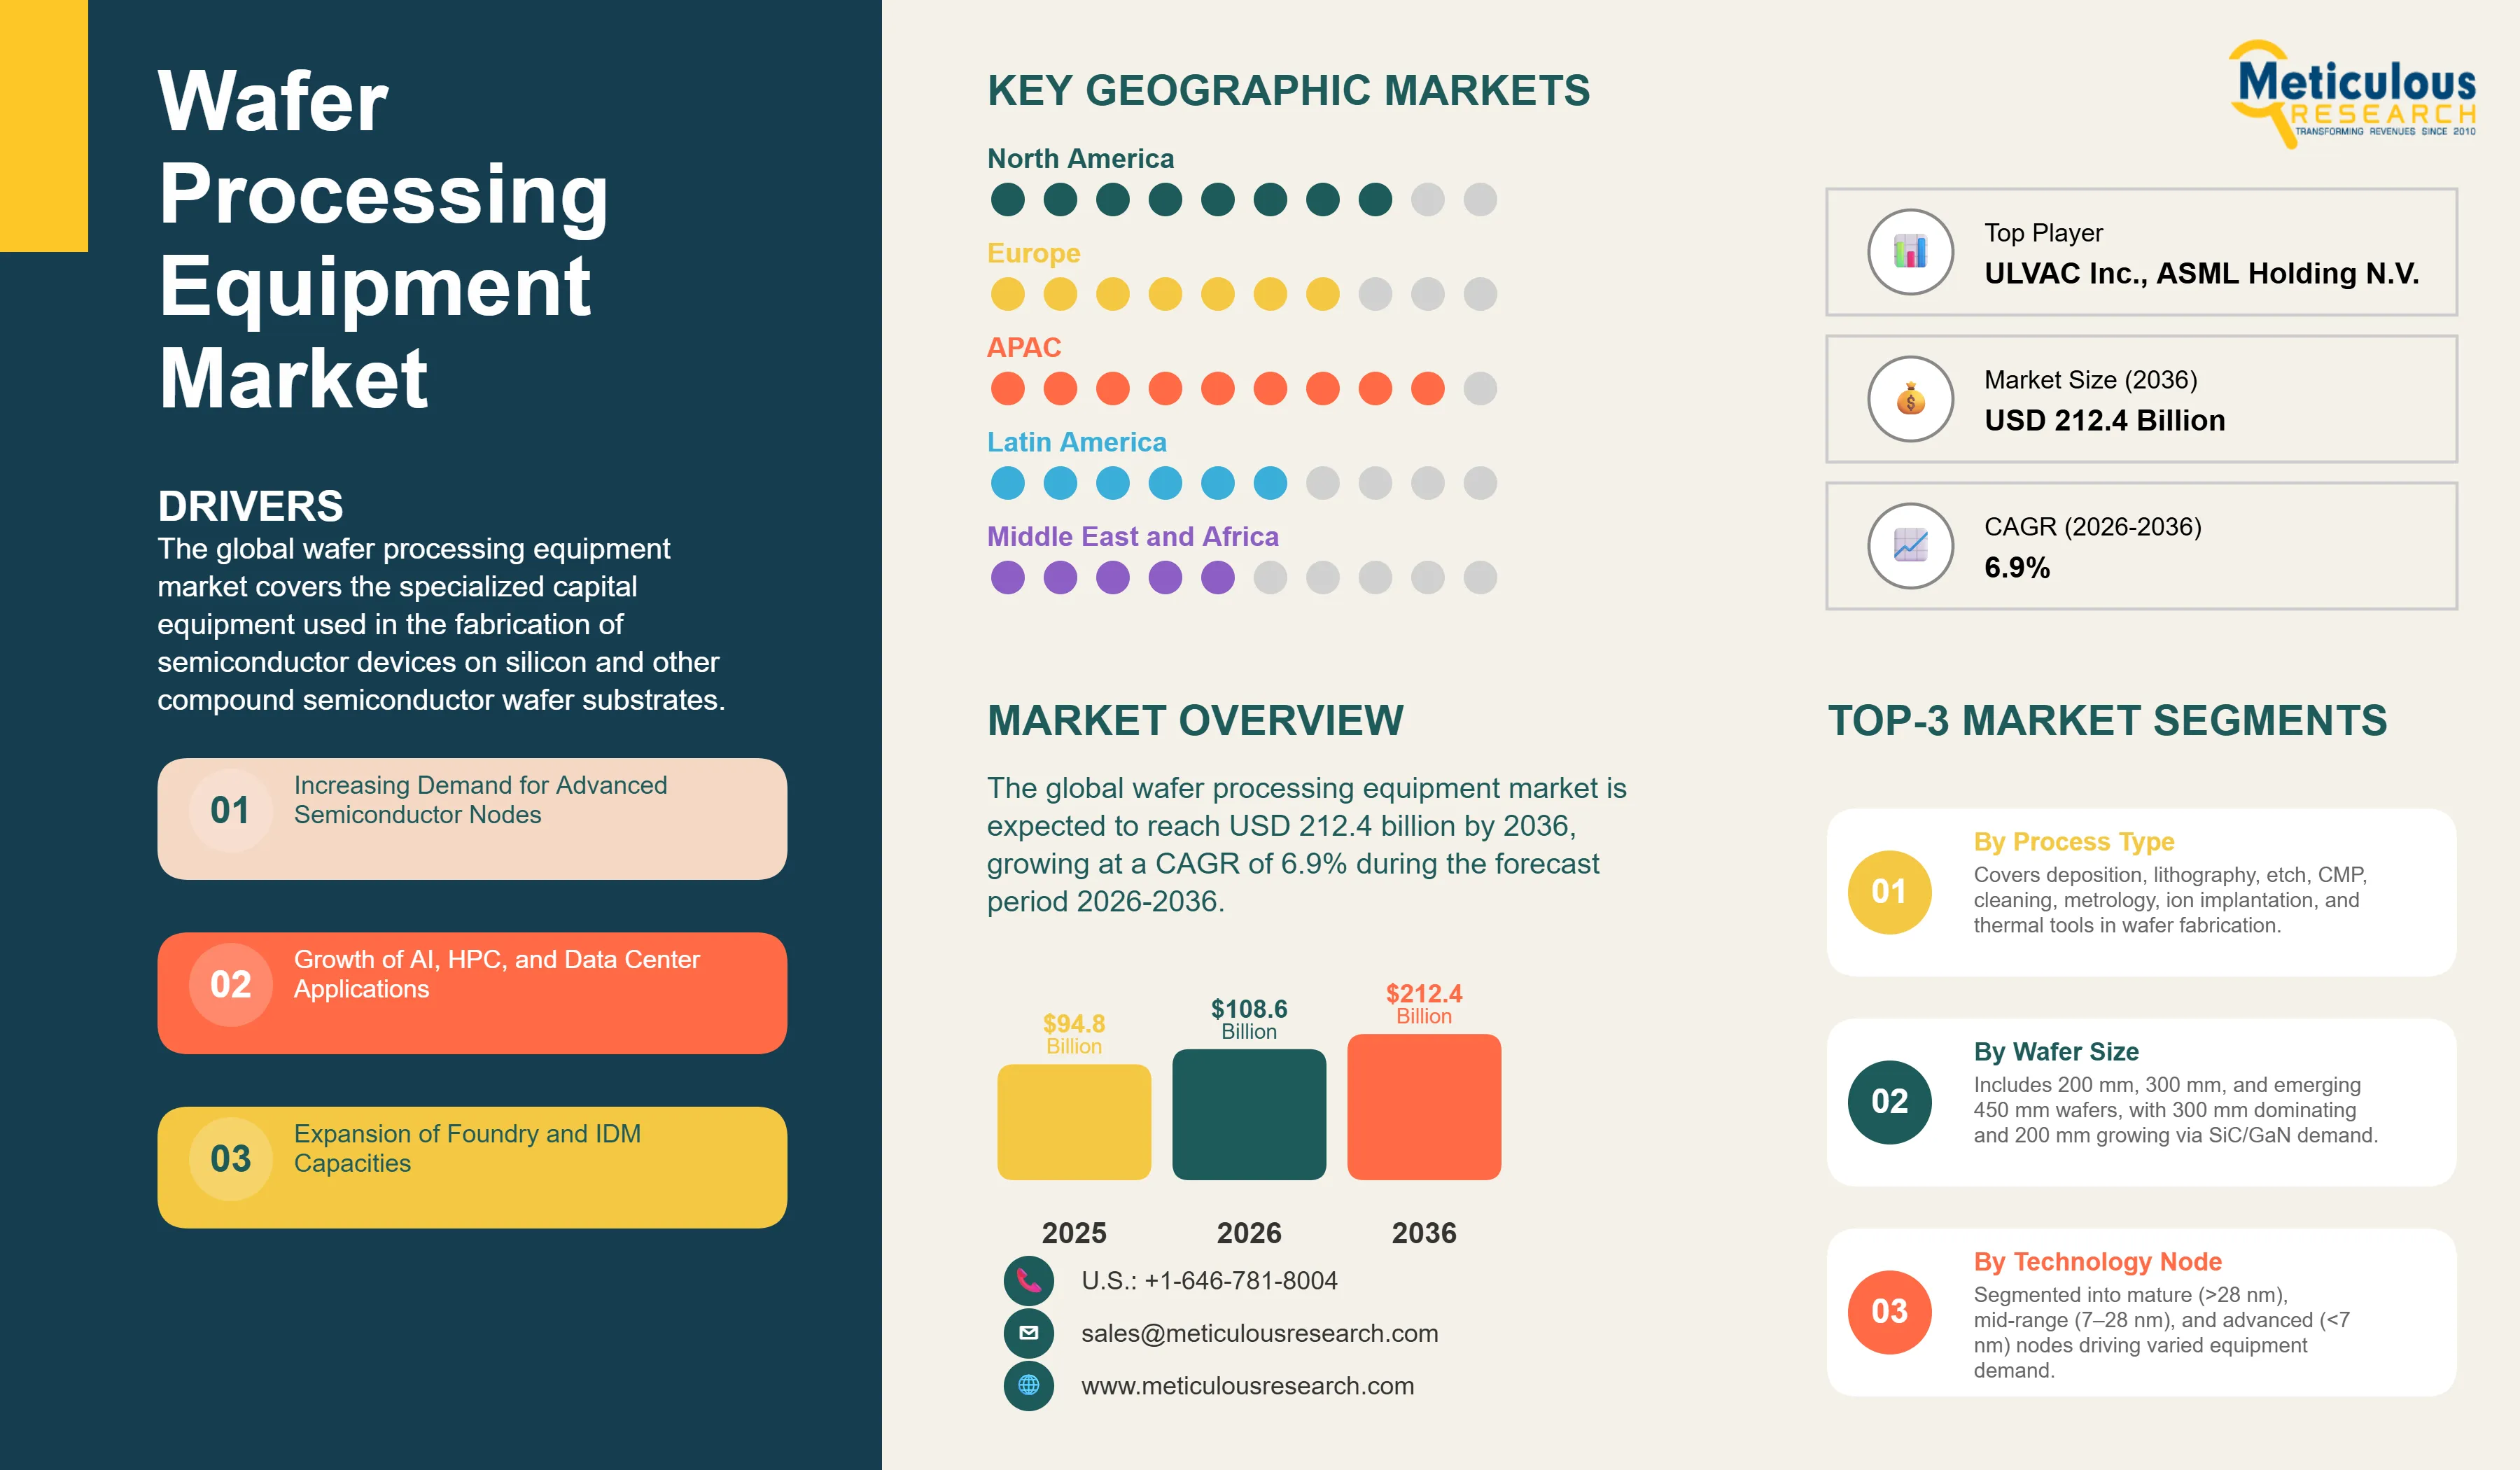
The global wafer processing equipment market was valued at USD 94.8 billion in 2025. This market is expected to reach USD 212.4 billion by 2036 from an estimated USD 108.6 billion in 2026, growing at a CAGR of 6.9% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 275
- Format
- PDF + Excel
- Report ID
- MR-1903
- Base year
- 2025
- 2025 · BASELINE
- $94.80B
- 2036
- $212.4B
- CAGR 2026–2036
- 6.9%
2025 baseline · 2026–2036 forecast at 6.9% CAGR · hover a bar for the value
Key highlights
The global wafer processing equipment market is projected to reach USD 212.4 billion by 2036.
The market is expected to grow at a CAGR of 6.9% during the forecast period 2026-2036.
The global wafer processing equipment market was valued at USD 94.8 billion in 2025 and is estimated to reach USD 108.6 billion in 2026.
Asia-Pacific is expected to dominate the global wafer processing equipment market with the largest market share in 2026, while North America is projected to register the highest CAGR during the forecast period.
By process type, the deposition equipment segment is expected to hold the largest share of the market in 2026, while the lithography equipment (EUV) segment is projected to register the highest CAGR during the forecast period.
By wafer size, the 300 mm segment is expected to hold the largest share in 2026, while the 200 mm segment is projected to register notable growth driven by SiC and GaN compound semiconductor applications during the forecast period.
By technology node, the mature nodes segment is expected to hold the largest share in 2026, while the advanced nodes segment is projected to register the highest CAGR during the forecast period.
By material type, the silicon segment is expected to hold the largest share in 2026, while the silicon carbide (SiC) segment is projected to register the highest CAGR during the forecast period.
By application, the logic devices segment is expected to hold the largest share in 2026, while the power devices segment is projected to register the highest CAGR during the forecast period.
By end user, the foundries segment is expected to hold the largest share in 2026, while the IDMs segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 212.4 Billion |
| Market Size in 2026 | USD 108.6 Billion |
| Market Size in 2025 | USD 94.8 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 6.9% |
| Format | PDF, Excel & Cloud Portal · 275 pages |
| Dominating Process Type | Deposition Equipment |
| Fastest Growing Process Type | Lithography Equipment (EUV) |
| Dominating Wafer Size | 300 mm |
| Fastest Growing Wafer Size | 200 mm (SiC/GaN applications) |
| Dominating Technology Node | Mature Nodes (>28 nm) |
| Fastest Growing Technology Node | Advanced Nodes (<7 nm) |
| Dominating Material Type | Silicon (Si) |
| Fastest Growing Material Type | Silicon Carbide (SiC) |
| Dominating Application | Logic Devices |
| Fastest Growing Application | Power Devices |
| Dominating End User | Foundries |
| Fastest Growing End User | IDMs |
| Dominating Geography | Asia-Pacific |
| Fastest Growing Geography | North America |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: process type, wafer size, end user, automation level.
The global wafer processing equipment market covers the specialized capital equipment used in the fabrication of semiconductor devices on silicon, silicon carbide, gallium nitride, and other compound semiconductor wafer substrates. This encompasses the full range of front-end-of-line process equipment including deposition systems for chemical vapor deposition, physical vapor deposition, and atomic layer deposition, photolithography systems spanning deep ultraviolet and extreme ultraviolet exposure platforms, dry and wet etching equipment, chemical mechanical planarization systems, wafer cleaning tools, inspection and metrology platforms, ion implantation systems, and thermal processing equipment that collectively perform the hundreds to thousands of process steps required to fabricate advanced logic, memory, power, and analog semiconductor devices.
The growth of the global wafer processing equipment market is primarily driven by the semiconductor industry's continued advancement along the technology node roadmap toward 3 nm, 2 nm, and sub-2 nm logic nodes that require progressively more sophisticated and higher-capital-intensity process equipment per wafer layer, and the unprecedented global wave of fab investment programs being funded through the U.S. CHIPS and Science Act, the EU Chips Act, and national semiconductor manufacturing investment initiatives in Japan, South Korea, India, and Taiwan that are creating the largest sustained increase in semiconductor manufacturing capacity investment in the industry's history. The AI-driven surge in advanced logic chip demand for training accelerators and inference processors at TSMC, Samsung Foundry, and Intel Foundry is generating the strongest advanced node capacity expansion cycle in recent memory, with each new leading-edge logic fab representing USD 15 to 25 billion of process equipment procurement.
Two significant opportunities are shaping the market's long-term trajectory. The rapid growth of compound semiconductor manufacturing, particularly silicon carbide for EV power electronics and gallium nitride for RF and power conversion applications, represents a fast-growing and high-value adjacent market for wafer processing equipment that is expanding the addressable market beyond traditional silicon device manufacturing and requiring specialized equipment adaptations for the different substrate properties, process temperatures, and chemistry requirements of SiC and GaN fabrication. The continuing advancement toward and beyond the 2 nm technology node, requiring the adoption of High-NA EUV lithography and increasingly complex multi-patterning and gate-all-around transistor process sequences, is driving equipment replacement cycles and new equipment procurement at leading-edge fabs at the highest per-wafer-layer equipment cost intensity in semiconductor manufacturing history.
Report infographic
Market dynamics
7 factors across 3 forcesIncreasing Demand for Advanced Semiconductor Nodes
The primary driver of the global wafer processing equipment market is the semiconductor industry's sustained advancement toward sub-3 nm and sub-2 nm logic technology nodes that require progressively more capable, more numerous, and higher-cost process equipment per manufactured chip. Each successive technology node generation increases the number of mask layers required per chip, adding multiple deposition, lithography, etch, and CMP process steps to the manufacturing sequence and expanding the equipment capital investment required per wafer fab proportionally. The transition to gate-all-around nanosheet transistor architectures at the 2 nm node and below involves entirely new epitaxial deposition, selective etch, and thermal processing sequences that require equipment configurations and capabilities not needed for FinFET devices, creating mandatory equipment upgrade and replacement cycles at leading-edge fabs that directly drive equipment procurement demand. The AI chip demand driven by foundation model training and inference infrastructure buildout at hyperscale data centers is generating unprecedented demand for advanced logic chips from TSMC, Samsung Foundry, and Intel Foundry that is sustaining leading-edge fab utilization and capital investment at historically high levels through the forecast period.
Expansion of Foundry and IDM Capacities
The global expansion of both pure-play foundry capacity and integrated device manufacturer production programs represents a sustained structural demand driver for wafer processing equipment that is operating independently of the cyclical demand fluctuations that have historically dominated semiconductor equipment market dynamics. TSMC's announced capital expenditure of approximately USD 32 to 38 billion annually through the mid-2020s, dedicated primarily to equipment procurement for advancing and expanding its leading-edge and mature node manufacturing capacity, represents the single largest annual equipment procurement program globally and sets a sustained demand floor for the equipment suppliers serving TSMC's technology transitions. Samsung Semiconductor's parallel capacity investment program, Intel's IDM 2.0 strategy investing heavily in its foundry capabilities across U.S. and European facilities, and the GlobalFoundries, UMC, and SMIC capacity expansion programs collectively create a multi-supplier equipment procurement market of extraordinary scale and geographic diversity that sustains the wafer processing equipment market at elevated investment levels throughout economic cycles.
Table of contents
15 chapters · 186 sections · 275 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Process Type | Deposition Equipment | Lithography equipment |
| By Wafer Size | 300 mm | — |
| By Technology Node | Mature Nodes | Advanced nodes |
| By Material Type | Silicon | Silicon carbide |
| By Application | Logic Devices | Power devices |
| By End User | Foundries | IDMs |
By Process Type
- Deposition Equipment to Dominate
- The deposition equipment segment is expected to account for the largest share of the global wafer processing equipment market.
- The large share of this segment is attributed to deposition processes encompassing CVD, PVD, and ALD collectively representing the most equipment-intensive and highest capital expenditure category within the wafer fabrication process flow, with multiple deposition steps required at each device layer for gate dielectric, metal contact, barrier, interconnect, and hardmask film deposition applications across hundreds of process layers in leading-edge logic chips.
- Applied Materials is the global leader in deposition equipment, with its Centura and Endura platforms dominating CVD, PVD, and ALD tool procurement across leading foundries and IDMs.
- However, the lithography equipment segment is poised to register the highest CAGR during the forecast period.
- The high growth of this segment is attributed to the accelerating EUV scanner installation rates at TSMC, Samsung Foundry, and Intel Foundry for advanced node capacity expansion, the introduction of High-NA EUV EXE:5000 systems at Intel's Intel 18A and future nodes at very high per-unit prices exceeding USD 350 million, and the continuous increase in EUV scanner count per wafer fab as EUV layer count per chip grows at each successive advanced technology node.
By Wafer Size
- 300 mm to Hold the Largest Share
- The 300 mm segment is expected to account for the largest share of the global wafer processing equipment market.
- The dominance of 300 mm reflects the industry-standard wafer size for all leading-edge and advanced logic and memory semiconductor manufacturing, with TSMC, Samsung, SK Hynix, Micron, Intel, and all major high-volume semiconductor manufacturers operating 300 mm fabs that consume the large majority of global semiconductor equipment procurement.
- The superior economics of 300 mm manufacturing relative to 200 mm for high-volume silicon device production, driven by the larger die count per wafer and the automation advantages of 300 mm AMHS-equipped facilities, ensure 300 mm's continued dominance as the production wafer size for the foreseeable forecast horizon.
- However, the 200 mm segment is projected to register significant growth during the forecast period.
- This growth is driven by the expansion of SiC and GaN compound semiconductor manufacturing, which is currently conducted primarily on 150 mm and 200 mm substrates due to the limited availability and high cost of larger-diameter SiC wafers, the sustained high demand for mature-node silicon devices fabricated at 200 mm fabs for automotive, industrial, and IoT applications, and the significant new 200 mm fab investment programs being driven by mature-node supply shortages experienced during the 2021 to 2023 semiconductor supply crisis.
By Technology Node
- Mature Nodes to Hold the Largest Share
- The mature nodes segment is expected to account for the largest share of the global wafer processing equipment market.
- The dominance of mature nodes reflects the very large global installed base of semiconductor manufacturing capacity at 28 nm and above serving the automotive, industrial, IoT, consumer electronics, and analog and mixed-signal device markets that represent the majority of global semiconductor unit production volume.
- The large number of mature-node fabs globally, including those operated by TSMC, GlobalFoundries, UMC, SMIC, and numerous IDMs and specialty manufacturers, collectively generates the highest aggregate equipment maintenance, upgrade, and replacement procurement volumes even though individual transaction values are lower than advanced node equipment.
- However, the advanced nodes segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the very high per-layer and per-wafer equipment capital intensity of sub-7 nm manufacturing, the progressive ramp of multiple new leading-edge logic fabs at TSMC, Samsung, and Intel across the forecast period, and the growing layer count per chip at each successive advanced node that expands equipment requirements per wafer fab even at constant wafer volume.
By Material Type
- Silicon to Hold the Largest Share
- The silicon segment is expected to account for the largest share of the global wafer processing equipment market.
- Silicon's overwhelming dominance reflects its position as the substrate material for the vast majority of global semiconductor production, encompassing all leading-edge logic and memory devices, the majority of analog and power semiconductor production, and nearly all foundry services.
- The decades-long optimization of silicon wafer processing equipment and process chemistry, the availability of 300 mm silicon substrates at low cost, and silicon's excellent thermal and electrical properties for most semiconductor device categories ensure its continued dominance through the forecast period.
- However, the silicon carbide segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the explosive commercial expansion of SiC power device manufacturing for EV inverters and chargers, the planned transition of major SiC manufacturers from 150 mm to 200 mm wafer processing at multiple gigafactory-scale capacity expansion programs, and the premium pricing of SiC-compatible equipment relative to silicon equipment that amplifies revenue growth relative to unit volume growth in this segment.
By Application
- Logic Devices to Hold the Largest Share
- The logic devices segment is expected to account for the largest share of the global wafer processing equipment market.
- Logic device manufacturing, encompassing advanced microprocessors, application processors, AI accelerators, FPGAs, and general-purpose computing chips, represents the highest equipment capital intensity per wafer of any semiconductor product category due to the largest layer counts, most complex transistor architectures, and most advanced lithography and patterning requirements.
- TSMC's N3 and N2 logic process nodes, Samsung Foundry's 3GAE and 2 nm SF2, and Intel Foundry's Intel 18A and 14A platforms collectively represent the highest per-fab equipment investment programs in the semiconductor industry.
- However, the power devices segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the explosive global demand for SiC and GaN power devices in EV applications, the large capacity expansion investments underway at SiC device manufacturers globally, and the increasing semiconductor content per electric vehicle as power electronics performance requirements intensify in higher-voltage 800-volt EV architectures.
By End User
- Foundries to Hold the Largest Share
- The foundries segment is expected to account for the largest share of the global wafer processing equipment market.
- Pure-play foundries represent the dominant wafer processing equipment procurement channel, with TSMC's annual capital expenditure program of USD 32 to 38 billion representing the single largest equipment procurement budget globally.
- The pure-play foundry model's specialization in wafer manufacturing at the most advanced process nodes, its continuous capital expenditure across technology transitions, and the concentration of the world's most technically demanding leading-edge chip manufacturing at a small number of leading foundries creates an equipment procurement market concentration at TSMC, Samsung Foundry, and GlobalFoundries that generates the majority of the wafer processing equipment market's highest-value equipment categories.
- However, the IDMs segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by Intel's IDM 2.0 strategy committing very large capital expenditure to rebuilding its manufacturing technology leadership through Intel Foundry, the SiC device manufacturers' large capacity expansion programs as they scale from pilot to high-volume production, and the compound semiconductor IDM programs of Wolfspeed, ON Semiconductor, and Infineon that are investing in proprietary SiC and GaN manufacturing capacity at scales requiring significant wafer processing equipment procurement.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global wafer processing equipment market. The largest share of this region is mainly due to the concentration of the world's leading semiconductor foundries and memory manufacturers in Taiwan, South Korea, Japan, and China, which collectively operate the majority of global semiconductor manufacturing capacity and generate the dominant share of annual wafer processing equipment procurement. TSMC's Taiwan-based fab complex, comprising over a dozen advanced and leading-edge manufacturing facilities in Hsinchu, Taichung, and Tainan science parks, represents the single largest concentration of wafer processing equipment procurement globally. Samsung Semiconductor's Hwaseong, Pyeongtaek, and Giheung complexes in South Korea and SK Hynix's Icheon and Cheongju facilities collectively represent the world's largest memory chip manufacturing base requiring sustained equipment investment for technology node transitions and capacity expansion. Japan's semiconductor equipment manufacturing leadership through Applied Materials Japan, Tokyo Electron, Screen Holdings, Hitachi High-Tech, and Canon represents both a manufacturing base for global equipment supply and a domestic customer base consuming equipment for Sony Semiconductor, Kioxia, Renesas, and other Japanese device manufacturers. China's equipment procurement from SMIC, CXMT, YMTC, and the expanding domestic semiconductor industry is growing rapidly despite export control restrictions on the most advanced equipment categories.
North America
Fastest growthHowever, the North American wafer processing equipment market is expected to grow at the fastest CAGR during the forecast period. North America's rapid growth is driven by the CHIPS Act-catalyzed wave of new fab construction representing the largest concentrated increase in U.S. semiconductor manufacturing capacity in decades, with TSMC's three-fab Arizona complex, Samsung's Taylor and expanded Austin facilities, Intel's Ohio and Arizona investments, Micron's U.S. memory expansion, and GlobalFoundries' facilities collectively requiring very large-scale equipment procurement programs that will substantially increase North American equipment consumption relative to its historically modest share of global equipment demand. The establishment of new fab operations in Arizona, Texas, Ohio, New York, Idaho, and Oregon by multiple manufacturers simultaneously is creating a geographic diversification of equipment procurement demand that benefits all major equipment suppliers and creates new opportunities for equipment companies to build North American service, support, and applications infrastructure generating sustained recurring revenue.
Europe
Europe's wafer processing equipment market is benefiting from the EU Chips Act and the major fab investments underway at Intel Magdeburg, TSMC Dresden, and expanding European IDM facilities that are progressively increasing the European region's share of global semiconductor manufacturing capacity. The Netherlands' unique position as the home of ASML represents the world's most commercially critical semiconductor equipment manufacturing concentration, with ASML's EUV scanners representing the highest-value single equipment category in the entire semiconductor supply chain and the Netherlands' export control framework for ASML's most advanced systems being one of the most commercially consequential trade policy issues in global semiconductor manufacturing.
Competitive landscape
- Applied Materials Inc. (U.S.)
- Lam Research Corporation (U.S.)
- Tokyo Electron Limited · Japan
- ASML Holding N.V. · Netherlands
- KLA Corporation (U.S.)
- Hitachi High-Tech Corporation · Japan
- SCREEN Holdings Co. Ltd. · Japan
- ASM International N.V. · Netherlands
- Canon Inc. · Japan
- Nikon Corporation · Japan
- Veeco Instruments Inc. (U.S.)
- Advantest Corporation · Japan
- Teradyne Inc. (U.S.)
- ULVAC Inc. · Japan
- Plasma-Therm LLC (U.S.)
Frequently asked questions
The global wafer processing equipment market is expected to reach USD 212.4 billion by 2036 from an estimated USD 108.6 billion in 2026, at a CAGR of 6.9% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Wafer Processing Equipment Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1903). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/wafer-processing-equipment-market-6586