Online Gaming Market (2023-2030)
is expected to reach $431.87 billion by 2030, at a CAGR of 19.6% during the forecast period of 2023–2030.
- Published
- Feb 2023
- Pages
- 253
- Format
- PDF + Excel
- Report ID
- MRICT - 104776
- Base year
- 2022
- 2030 · FORECAST
- $431.9B
- 2030
- $431.9B
- CAGR 2023–2030
- 19.6%
2022 baseline · 2023–2030 forecast at 19.6% CAGR · hover a bar for the value
Key highlights
is expected to reach $431.87 billion by 2030, at a CAGR of 19.6% during the forecast period of 2023–2030.
The free-to-play segment is expected to account for the larger share of the global online gaming market.
The action-adventure segment is expected to account for the largest share of the global online gaming market during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2022 |
| Estimated Year | 2023 |
| Forecast Period | 2023–2030 |
| Market Size (2030) | USD 431.87 billion |
| CAGR (2023–2030) | 19.6% |
| Format | PDF, Excel & Cloud Portal · 253 pages |
| Segments Covered | By Model: Free-to-play Games, Pay-to-Play Games · By Genre: Action/Adventure, Sandbox, Simulation and Sports, Role-playing, Player VS. Player, Multiplayer Online Battle Arena, Real-time Strategy, Shooters, Racing, Puzzlers and Party Games, Survival Horror, Other Genres · By Platform: Mobile Platforms Tablet Games, Smartphone Games, Browser PC Games, Boxed/Downloadable PC Games · By Streaming: Live Streaming, On-demand Streaming |
| Countries Covered | North America (Canada), Europe (U.K., Germany, France, Italy, Spain, Netherlands, Denmark, Rest of Europe), Asia-Pacific (China, Japan, India, Singapore) |
| Key Companies | Microsoft Corporation, Activision Blizzard, Inc., Apple Inc., Electronic Arts Inc., Nintendo Co., Ltd., Capcom Co., Ltd., Rovio Entertainment Corporation, Sony Interactive Entertainment Inc., Com, Inc., Tencent Holdings Ltd. |
Report overview
Segments covered: model, genre, platform, streaming. Regions: North America, Europe, Asia-Pacific.
The growth of this market is driven by the rise in the popularity of online gaming, a surge in the use of smartphones for online gaming, and the gradual establishment of internet infrastructure in developing countries. However, a lack of standards and regulations can restrain the market growth.
In addition, the creation of new monetization models and in-game advertisements and sponsorships are expected to offer significant opportunities for the growth of this market.
The COVID-19 pandemic impacted the worldwide economy. Governments worldwide imposed countrywide lockdowns to control the spread of the infection. The lockdown restrictions impacted manufacturing operations, with production facilities either completely shutting down or running at reduced capacities to ensure social distancing and employee safety. Most industries came to a standstill due to raw material & workforce shortages, supply chain disruptions, and restrictions on international trade. One area that has been relatively unaffected during the pandemic is the gaming industry, with user engagement growing considerably during this period
During the COVID-19 pandemic, the gaming industry witnessed an unprecedented surge in consumer demand and faced various challenges. For instance, the American telecommunications company Verizon reported a 75% increase in online gaming traffic during peak hours, compared to a 12% increase in digital video traffic and a 20% increase in web traffic. Similarly, WinZo Games (India) reported three times more user engagement and 30% higher traffic in online mobile gaming. Around 35% higher usage has been observed in multiplayer modes than in single-user modes. Similarly, Paytm First Games, an Indian mobile-based online gaming platform, reported an almost 200% increase in the user base during the pandemic, with 75,000 new users.
Apart from the COVID-19 lockdowns, people’s increased interest in online gaming was attributed to the anticipated launch of new titles and next-generation consoles. According to WeForum, Asian gaming giants Nintendo (Japan) and Tencent (China) saw increased sales during the COVID-19 pandemic, while Tencent witnessed a year-on-year increase of 31% in revenue from its online games. Gaming companies had to adjust rapidly to this unprecedented growth as further growth is expected in the coming years. Thus, the gaming industry proved resilient during the COVID-19 pandemic due to the significant increase in demand for online gaming.
The online gaming industry has grown rapidly during the last decade. The popularity of online gaming is largely attributed to its convenience and accessibility. Currently, the number of online gamers is increasing four times faster compared to the number of internet users. Globally, gamers spend more of their spare time online due to increased bandwidth and connectivity.
The accessibility of online games is increasing as people no longer must visit specific websites to play their favorite games online and can do so using gaming consoles or smartphones. Online game has become a great source of entertainment for people around the world. Online gaming also provides an excellent opportunity for players to interact with other players around the world.
The rapid growth and increasing popularity of online gaming have led to the advent of competitive gaming events. Social networks such as Facebook and Twitter have also started offering free-to-play online multiplayer games. Online video games offer users an immersive experience, particularly due to technological improvements in gaming hardware & software. Increasing smartphone penetration and the affordability of mobile data have driven an increase in mobile online gaming. Also, the increasing integration of cutting-edge technologies, such as AR/VR and cloud, has enhanced customers’ gaming experience, driving the growth of this market.
Report infographic
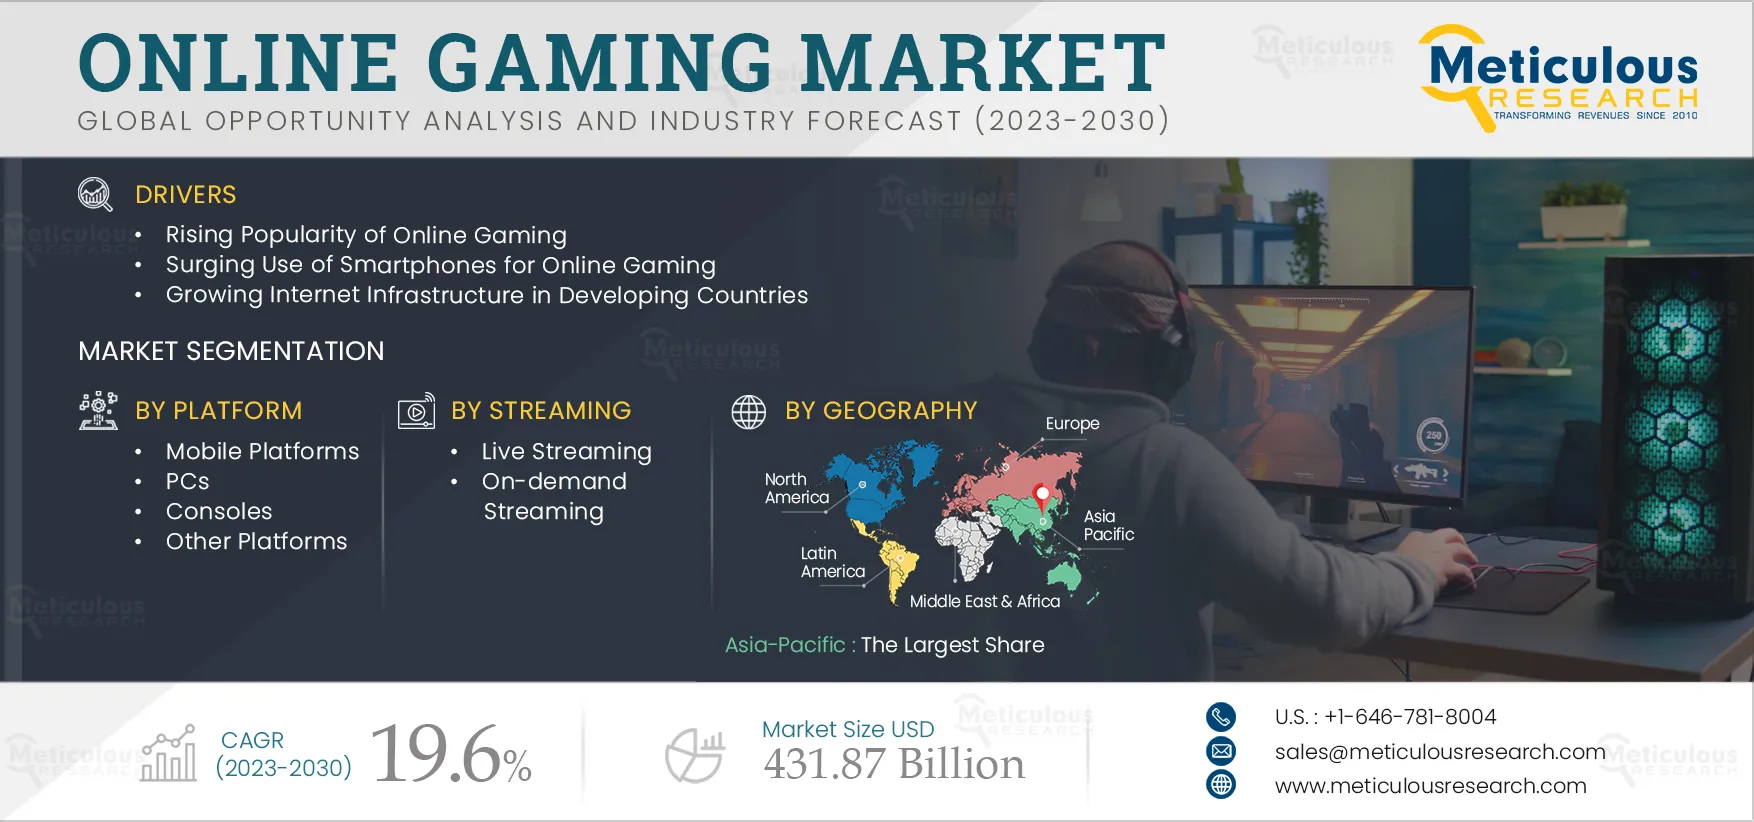
Table of contents
14 chapters · 193 sections · 253 pages · click to expandSegmental analysis
| Segment | Largest share (2023) | Fastest growth (2023–2030) |
|---|---|---|
| By Model | Free-to-Play | Pay-to-play |
| By Genre | Action-adventure | Shooters |
By Model
- The free-to-play segment is expected to account for the larger share of the global online gaming market.
- The growth of this segment is attributed to digital entertainment mediums, the rise in the number of smartphone users and the increasing usage of the internet across the globe.
- However, the pay-to-play segment is slated to register the highest CAGR during the forecast period.
By Genre
- The action-adventure segment is expected to account for the largest share of the global online gaming market during the forecast period.
- The large market share of this segment is attributed to technologies such as VR and AR to improve the gaming experience.
- However, the shooters segment is projected to register the highest CAGR during the forecast period.
- Asia-Pacific is expected to account for the largest share of the online gaming market.
- The large market share of Asia Pacific is mainly attributed to the high focus of gaming companies on game development in China, Japan, South Korea, and India and the deployment of multiple tactics and strategies by China’s game developers to attract users and integrate social media networks with games.
Competitive landscape
- Microsoft Corporation
- Activision Blizzard, Inc.
- Apple Inc.
- Electronic Arts Inc.
- Nintendo Co., Ltd.
- Capcom Co., Ltd.
- Rovio Entertainment Corporation
- Sony Interactive Entertainment Inc.
- Com, Inc.
- Tencent Holdings Ltd.
Frequently asked questions
The global online gaming market is projected to reach $431.87 billion by 2030 at a CAGR of 19.6% during the forecast period.
Cite this report
Meticulous Research. (2023). Online Gaming Market - Global Opportunity Analysis And Industry Forecast (2023-2030) (Report No. MRICT - 104776). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/online-gaming-market-5460