Industrial Wearable Devices Market (2026-2036)
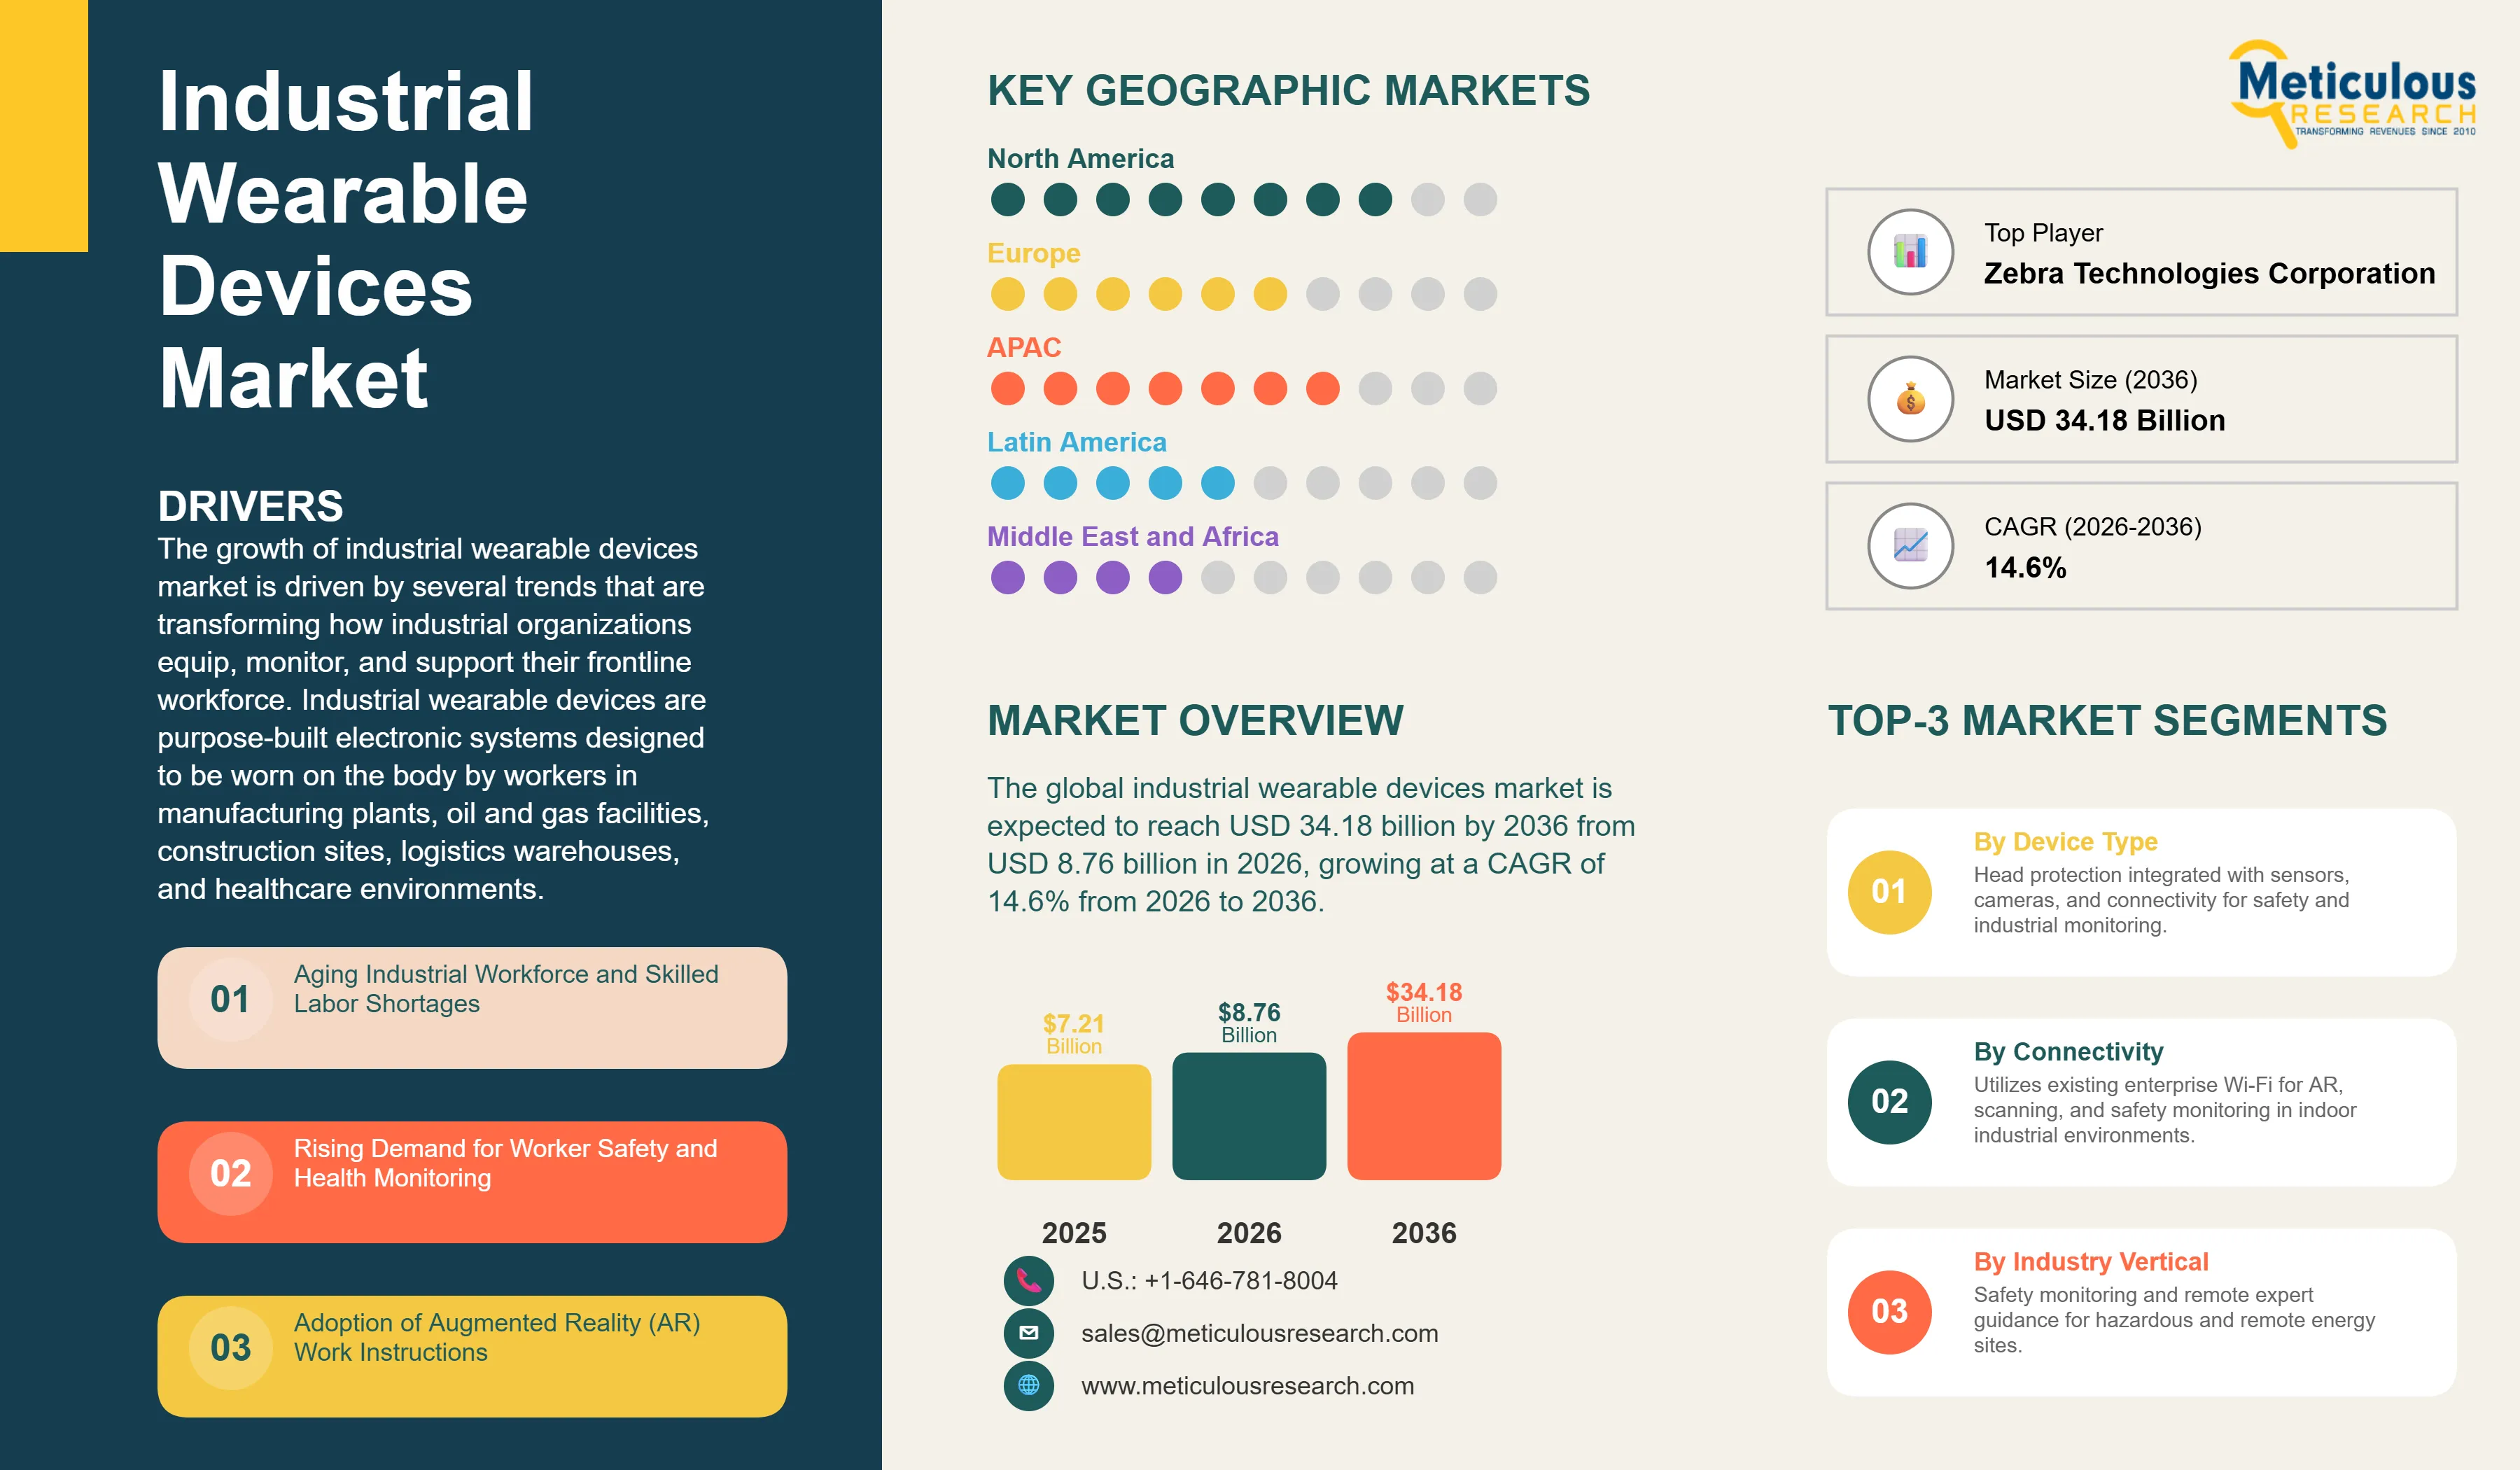
The global industrial wearable devices market was valued at USD 7.21 billion in 2025. This market is expected to reach USD 34.18 billion by 2036 from USD 8.76 billion in 2026, growing at a CAGR of 14.6% from 2026 to 2036.
- Published
- Mar 2026
- Pages
- 278
- Format
- PDF + Excel
- Report ID
- MR-1843
- Base year
- 2025
- 2025 · BASELINE
- $7.21B
- 2036
- $34.18B
- CAGR 2026–2036
- 14.6%
2025 baseline · 2026–2036 forecast at 14.6% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global industrial wearable devices market is projected to reach USD 34.18 billion by 2036.
The market is expected to grow at a CAGR of 14.6% from 2026 to 2036.
North America is expected to dominate the global industrial wearable devices market with the largest market share in 2026, driven by the region's large manufacturing and oil and gas industries deploying wearable safety and productivity solutions, early adoption of augmented reality work instruction platforms by major industrial companies including Boeing, Lockheed Martin, and Chevron, and the presence of leading industrial wearable technology developers including Honeywell, Zebra Technologies, and RealWear.
Asia-Pacific is expected to witness the fastest growth during the forecast period, supported by China's large-scale manufacturing sector adopting wearable productivity and quality control tools as part of its smart factory development programs, Japan's aging industrial workforce driving demand for exoskeleton and AR guidance solutions that extend productive working life, and South Korea's and Australia's resource extraction industries deploying wearable safety monitoring systems in mining and offshore energy operations.
By device type, the smart glasses and AR headsets segment is expected to hold the largest share of the overall industrial wearable devices market in 2026, as hands-free augmented reality platforms from RealWear, Google, and Honeywell have achieved the broadest enterprise deployment across manufacturing, field service, and logistics applications where hands-free access to work instructions and remote expert video is the primary productivity use case.
By connectivity, the Wi-Fi connected segment is expected to hold the largest share of the overall industrial wearable devices market in 2026, as enterprise Wi-Fi infrastructure is already deployed across most manufacturing plants and distribution centers where industrial wearables are being adopted, making Wi-Fi the default connectivity option for initial wearable deployments.
By industry vertical, the manufacturing segment is expected to hold the largest share of the overall industrial wearable devices market in 2026, as automotive, aerospace, electronics, and general industrial manufacturers have been the earliest and most active adopters of AR-guided assembly, quality inspection wearables, and worker safety monitoring platforms.
By sales channel, the system integrators and value-added resellers segment is expected to hold the largest share of the overall industrial wearable devices market in 2026, as industrial enterprises typically procure wearable solutions as part of broader digital transformation projects managed by industrial IT system integrators that handle device selection, software integration, deployment, and ongoing support.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 34.18 Billion |
| Market Size in 2026 | USD 8.76 Billion |
| Market Size in 2025 | USD 7.21 Billion |
| Market Growth Rate (2026-2036) | CAGR of 14.6% |
| Format | PDF, Excel & Cloud Portal · 278 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Device Type, Connectivity, Industry Vertical, Sales Channel, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: device type, connectivity, industry vertical, sales channel-.
The growth of this market is driven by several trends that are transforming how industrial organizations equip, monitor, and support their frontline workforce. Industrial wearable devices are purpose-built electronic systems designed to be worn on the body by workers in manufacturing plants, oil and gas facilities, construction sites, logistics warehouses, and healthcare environments. These devices differ fundamentally from consumer wearables in their design priorities: they are engineered for durability in harsh environments, compliance with occupational safety standards, all-day battery life under continuous use, compatibility with personal protective equipment, and integration with enterprise software platforms rather than consumer applications. Core product categories include smart glasses and augmented reality headsets that overlay digital information onto the worker's field of view, smart helmets that integrate sensors and communications into head protection, body-worn sensor systems that track physiological and environmental safety parameters, wrist-worn devices such as ruggedized smartwatches and wearable barcode scanners, and powered exoskeletons that reduce physical strain during manual handling tasks.
Several factors are driving the adoption of industrial wearables across key end markets. The aging of the skilled industrial workforce and the difficulty of retaining and training replacement workers is increasing the value of wearable-enabled remote expert guidance and step-by-step augmented reality work instructions that allow less experienced workers to perform complex tasks with fewer errors and less supervision. Industrial safety regulations in major markets are becoming increasingly data-driven, and wearable sensor platforms that continuously monitor worker vital signs, environmental gas concentrations, ergonomic risk, and proximity to hazardous equipment provide the real-time safety data that regulatory compliance programs and corporate safety management systems increasingly require. The rollout of private 5G networks in large industrial facilities is enabling a new generation of connected wearable applications that require low-latency, high-bandwidth wireless connectivity that previous Wi-Fi infrastructure could not reliably provide across large plant footprints.
Industrial wearable devices represent a distinct product category within the broader wearable technology market, defined by their design for use in physically demanding, safety-critical, and often hazardous industrial environments. The core technical requirements that differentiate industrial wearables from consumer wearables include ruggedization to IP65 or IP67 ingress protection ratings for dust and water resistance, compliance with relevant electrical safety standards for use in potentially explosive atmospheres, compatibility with hard hats, safety glasses, hearing protection, and gloves that workers in industrial settings are required to wear simultaneously, battery life sufficient for a full 8 to 12 hour work shift under continuous active use, and integration with enterprise resource planning, manufacturing execution, and industrial IoT platform software rather than consumer app ecosystems.
The industrial wearable device market encompasses five primary product categories that key players develop, brand, and sell as distinct product lines. Smart glasses and augmented reality headsets overlay digital information such as work instructions, equipment schematics, inventory data, and live video from remote experts onto the worker's field of view through a transparent display positioned in front of one or both eyes. Companies including RealWear with its HMT-1 and Navigator 500 head-mounted tablets, Google with Google Glass Enterprise Edition, and Honeywell with its Honeywell Intelligent Wearables platform lead this segment. Smart helmets integrate connectivity, cameras, sensors, and display capability into certified head protection, serving construction, mining, and energy sectors where head protection is mandatory and where the helmet provides a practical platform for sensor mounting. Body-worn sensors and safety wearables include clip-on gas detectors from Blackline Safety and MSA Safety, connected harness systems that detect falls, ergonomic monitoring bands from Kinetic and StrongArm Technologies that track unsafe movement patterns, and physiological monitoring devices that measure heart rate, core body temperature, and fatigue indicators. Wrist-worn devices encompass ruggedized smartwatches for worker communications and alert notification as well as wrist-mounted barcode and RFID scanners from Zebra Technologies and Honeywell that free warehouse workers' hands while maintaining scanning capability. Powered and passive exoskeletons from Ekso Bionics, SuitX, Ottobock, and Sarcos Technology support workers performing repetitive overhead assembly, heavy lifting, and prolonged standing by augmenting or offloading the physical effort required.
The competitive landscape of the industrial wearable devices market spans established industrial technology conglomerates, specialist wearable hardware developers, and enterprise software platform providers that increasingly bundle hardware and software into integrated solution offerings. Honeywell and Zebra Technologies represent the large industrial technology players that have built or acquired wearable product lines alongside their broader portfolio of industrial automation, safety, and data capture products. RealWear, Osterhout Design Group, and Vuzix are specialist AR headset developers focused exclusively on industrial head-worn computing. Blackline Safety, Guardhat, and Kenzen are specialist body-worn sensor and safety monitoring companies. Ekso Bionics and Sarcos compete in the emerging powered exoskeleton segment. Enterprise software companies including PTC with its Vuforia augmented reality platform and Scope AR provide the software layer that many hardware-agnostic industrial wearable deployments are built upon, creating a layered market structure where hardware and software are increasingly procured from different vendors and integrated by system integrators.
In 2026, the manufacturing segment is expected to hold the largest share of the industrial wearable devices market. Manufacturing has been the earliest and most active adopter of industrial wearable technology, particularly AR-guided assembly and quality inspection applications. The manufacturing environment provides favorable conditions for wearable adoption: facilities are typically indoors with established Wi-Fi infrastructure, workers perform repetitive complex tasks where AR guidance delivers measurable productivity gains, and the high cost of manufacturing defects provides a clear financial return on investment from error reduction. Automotive manufacturers including BMW, Ford, Volkswagen, and Toyota have been among the most public early adopters of AR wearables for assembly line worker guidance, quality inspection, and maintenance. Aerospace manufacturers including Boeing and Airbus have deployed AR wearables for complex wire harness assembly and aircraft maintenance procedures where paper documentation management is a significant challenge. Electronics manufacturers in Asia, particularly in China, South Korea, and Taiwan, are adopting wearable barcode scanners, AR inspection systems, and connected safety devices as part of smart factory initiatives supported by government-funded industrial upgrading programs.
However, the logistics and warehousing segment is expected to witness the fastest growth during the forecast period. The rapid growth of e-commerce has dramatically increased the volume and velocity of warehouse picking, packing, and sorting operations, creating strong demand for wearable devices that improve worker productivity and accuracy in these environments. Wrist-worn barcode scanners from Zebra Technologies and Honeywell allow warehouse workers to scan items and confirm picks hands-free, improving picking speed compared with handheld scanner workflows. AR-guided picking systems that display pick location and item information in the worker's field of view through smart glasses are being piloted by major logistics operators including DHL, UPS, and Amazon fulfillment network suppliers. The growth of same-day and next-day delivery commitments across e-commerce markets is increasing the productivity pressure on warehouse operations, making wearable tools that reduce pick time and error rates increasingly valuable. In addition, the logistics sector's high worker turnover rates make the training time reduction enabled by AR guidance systems particularly valuable for operators that must continuously onboard new workers.
Report infographic
Market dynamics
4 factors across 3 forcesAging Industrial Workforce and Skilled Labor Shortages
A key driver of the industrial wearable devices market is the accelerating retirement of experienced skilled workers from manufacturing, energy, and infrastructure industries and the difficulty of recruiting and training replacement workers to equivalent skill levels within acceptable timeframes. In the United States, the manufacturing sector is projected to have more than 2 million unfilled jobs by 2030, according to industry estimates, with the skills gap driven by the retirement of experienced baby boomer generation workers who carry decades of tacit process knowledge. Similar demographics are affecting manufacturing and industrial sectors in Germany, Japan, South Korea, and other major industrial economies. Industrial wearable platforms directly address this challenge in two ways. AR-guided work instruction systems allow less experienced workers to perform complex tasks correctly by following visual step-by-step guidance overlaid on their actual work environment, reducing dependence on memorized procedural knowledge. Remote expert assistance platforms, where an experienced specialist can see what a field technician is seeing through the wearable device's camera and provide live visual guidance, allow one expert to support multiple less-experienced workers simultaneously across different locations, extending the productivity of the most experienced remaining workforce.
Table of contents
11 chapters · 116 sections · 278 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Device Type | Smart glasses and AR headsets | — |
| Other segments | — | Exoskeletons |
| By Connectivity | Wi-Fi Connected | Cellular and 5G connected |
| By Sales Channel | System Integrators and VARs | Direct enterprise sales |
By Device Type
- The smart glasses and AR headsets segment is expected to hold the largest share of the industrial wearable devices market.
- This segment dominates because it addresses the most commercially validated and widely deployed industrial wearable use case: hands-free access to digital work instructions, equipment data, and remote expert video during physical work tasks.
- The hands-free capability is particularly important in industrial environments because workers are often wearing gloves and engaged in two-handed tasks where stopping to consult a phone, tablet, or printed document is time-consuming, disruptive, and sometimes unsafe.
- RealWear's HMT-1 and Navigator 500 head-mounted tablet devices, which use a display positioned below the eye rather than directly in the line of sight, have become the most widely deployed industrial AR headset platform globally, with more than 100,000 units deployed across customers including Shell, Merck, and Honeywell Process Solutions.
- Google Glass Enterprise Edition 2, distributed through Honeywell and other enterprise resellers, has achieved significant deployment in light manufacturing and logistics environments.
- The segment benefits from an established software ecosystem, with AR work instruction platforms from PTC Vuforia, Scope AR, and others providing proven enterprise deployments that reduce the technical risk of adoption for new customers.
Other segments
- However, the exoskeletons segment is expected to witness the fastest growth during the forecast period.
- This growth is driven by increasing recognition of musculoskeletal disorders as the leading category of occupational injury in manufacturing, logistics, and construction, combined with declining device costs as production volumes increase and design iterations reduce manufacturing complexity.
- Passive exoskeletons from companies including SuitX, Laevo, and Ottobock, which use springs and rigid frames to redistribute physical load without electronic components, have reached price points where large manufacturing and logistics operators are deploying them at scale.
- Powered exoskeletons from Ekso Bionics and Sarcos Technology, which use actuators and sensors to actively amplify worker strength, are being adopted for heavy-duty applications in automotive assembly and construction.
- Ford Motor Company and Boeing have publicly reported exoskeleton pilot programs in their assembly operations, and the involvement of major industrial employers in proving the business case for exoskeletons is accelerating broader adoption.
By Connectivity
- The Wi-Fi connected segment is expected to hold the largest share of the industrial wearable devices market.
- Wi-Fi connectivity dominates because enterprise Wi-Fi infrastructure is already deployed across the majority of manufacturing plants, distribution centers, and healthcare facilities where industrial wearables are being adopted.
- For most initial industrial wearable deployments, connecting devices to the existing enterprise Wi-Fi network is the path of least resistance and avoids the cost and complexity of deploying separate wireless infrastructure.
- The 802.11ac and 802.11ax Wi-Fi standards provide sufficient bandwidth for AR video streaming and data transfer in most indoor factory environments, and Wi-Fi security frameworks including WPA3 and enterprise authentication protocols satisfy corporate IT security requirements.
- RealWear, Google Glass Enterprise Edition, Zebra Technologies, and most other major industrial wearable platforms are designed with Wi-Fi as the primary connectivity option, reflecting the reality of the enterprise network environments where they are deployed.
- However, the cellular and 5G connected segment is expected to witness the fastest growth during the forecast period.
- As private 5G network deployment accelerates across large industrial facilities, oil and gas installations, mining sites, and port logistics terminals, cellular connectivity is becoming available in industrial environments that were previously served only by Wi-Fi or required standalone offline devices.
- The performance advantages of private 5G, including consistent low latency, outdoor coverage, and support for high device density, are unlocking wearable applications in field environments that Wi-Fi cannot reliably support.
- Major industrial operators including BP, Rio Tinto, and BMW have deployed or announced private 5G networks, and wearable device manufacturers are responding with 5G-capable product variants.
- In addition, the broader availability of LTE and 4G coverage in industrial areas means that cellular connectivity is increasingly practical for wearable deployments at smaller sites that cannot justify a private 5G investment.
By Sales Channel
- The system integrators and value-added resellers segment is expected to hold the largest share of the industrial wearable devices market.
- Industrial enterprises typically procure wearable solutions as part of broader digital transformation and Industry 4.0 projects rather than as standalone device purchases.
- These projects involve selection of hardware platforms, integration of wearable software with existing ERP, MES, and industrial IoT systems, change management programs for the workforce adopting new technology, and ongoing technical support.
- System integrators such as Accenture, Deloitte, Wipro, and specialized industrial IoT integrators manage these end-to-end deployments, selecting and procuring wearable hardware on behalf of their industrial clients and developing the custom software integrations that connect wearable platforms to enterprise systems.
- Value-added resellers that specialize in particular industries or technology platforms, such as RealWear's certified partner network or Zebra Technologies' PartnerConnect program, provide regional sales, implementation, and support services that hardware manufacturers rely upon to reach mid-market industrial customers that they cannot serve cost-effectively through direct sales teams alone.
- However, the direct enterprise sales segment is expected to witness the fastest growth during the forecast period.
- As industrial wearable technology matures and procurement processes become more standardized, large industrial corporations are increasingly purchasing wearable platforms directly from manufacturers through enterprise software agreements that combine hardware, software licenses, cloud platform access, and support services in a single commercial relationship.
- Tesla Energy's model of selling Solar Roof directly to homeowners through its own installation network provides an analogy: as vendors develop proven, standardized solution packages for defined use cases, the need for system integrator involvement in every deployment is reduced and direct sales become more efficient.
- Honeywell's Intelligent Wearables platform, RealWear's enterprise subscription model, and Blackline Safety's connected safety platform are examples of vendor-managed solutions that include hardware, software, analytics, and support in integrated commercial packages designed for direct enterprise procurement.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to hold the largest share of the global industrial wearable devices market. This leadership is primarily driven by the United States' position as the world's largest market for industrial AR and safety wearable deployments, supported by the presence of leading wearable technology developers, a large and technology-forward manufacturing and energy sector, and strong corporate investment in workforce productivity and safety technology. The U.S. oil and gas industry has been an early and significant adopter of connected safety wearables and AR remote assistance platforms. Companies including Shell, Chevron, ExxonMobil, and BP have deployed wearable safety monitoring systems from Blackline Safety and MSA Safety across upstream operations, and AR remote expert platforms from RealWear and Librestream for maintenance support at refineries and offshore facilities. The U.S. manufacturing sector, particularly aerospace and defense manufacturers including Boeing, Lockheed Martin, and Raytheon, has deployed AR-guided assembly and maintenance wearable systems at scale, with these programs receiving significant public documentation that has established proof of concept for the broader manufacturing market. Canada's mining and oil sands sectors also contribute to regional demand through deployments of connected safety monitoring wearables in remote extraction environments.
Asia-Pacific
Fastest growthAsia-Pacific is expected to witness the highest growth rate in the industrial wearable devices market during the forecast period. This growth is primarily driven by China's large-scale smart manufacturing initiatives, Japan's demographic-driven demand for workforce augmentation technology, and South Korea's and Australia's resource and advanced manufacturing sectors adopting wearable safety and productivity solutions. China is the largest and fastest-growing individual market in the Asia-Pacific region for industrial wearables. The Chinese government's Made in China 2025 and subsequent smart manufacturing policy initiatives are driving investment in factory digitization, including connected worker technology programs that encompass AR work instruction systems, wearable quality inspection devices, and connected safety monitoring. Chinese industrial equipment manufacturers are also developing domestic wearable products targeting the large domestic manufacturing base, creating a competitive domestic supply base alongside imported solutions from international vendors. Japan's industrial wearable market is driven by a particularly acute demographic challenge. Japan has the most rapidly aging industrial workforce globally, with the working-age population declining and the average age of skilled manufacturing and construction workers rising significantly. Exoskeletons that reduce physical strain and extend the working life of older workers are receiving significant government and corporate investment in Japan, with companies including Cyberdyne and Innophys developing domestically produced exoskeleton systems for manufacturing and nursing care applications. South Korea's semiconductor and electronics manufacturing sector is adopting AR inspection and quality monitoring wearables, and Australia's mining industry is deploying wearable safety systems for worker monitoring in remote surface and underground mining operations.
Competitive landscape
- Honeywell International Inc.
- Zebra Technologies Corporation
- RealWear Inc.
- Google LLC (Glass Enterprise Edition)
- Blackline Safety Corp.
- MSA Safety Incorporated
- Ekso Bionics Holdings Inc.
- Sarcos Technology and Robotics Corporation
- Kinetic Inc.
- StrongArm Technologies Inc.
- Guardhat Inc.
- Vuzix Corporation
- PTC Inc. · Vuforia
- Librestream Technologies Inc.
- Kenzen Inc
Frequently asked questions
The global industrial wearable devices market is expected to grow from USD 8.76 billion in 2026 to USD 34.18 billion by 2036.
Cite this report
Meticulous Research. (2026). Industrial Wearable Devices Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MR-1843). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/industrial-wearable-devices-market-6526