Induction Furnaces Market (2026-2036)
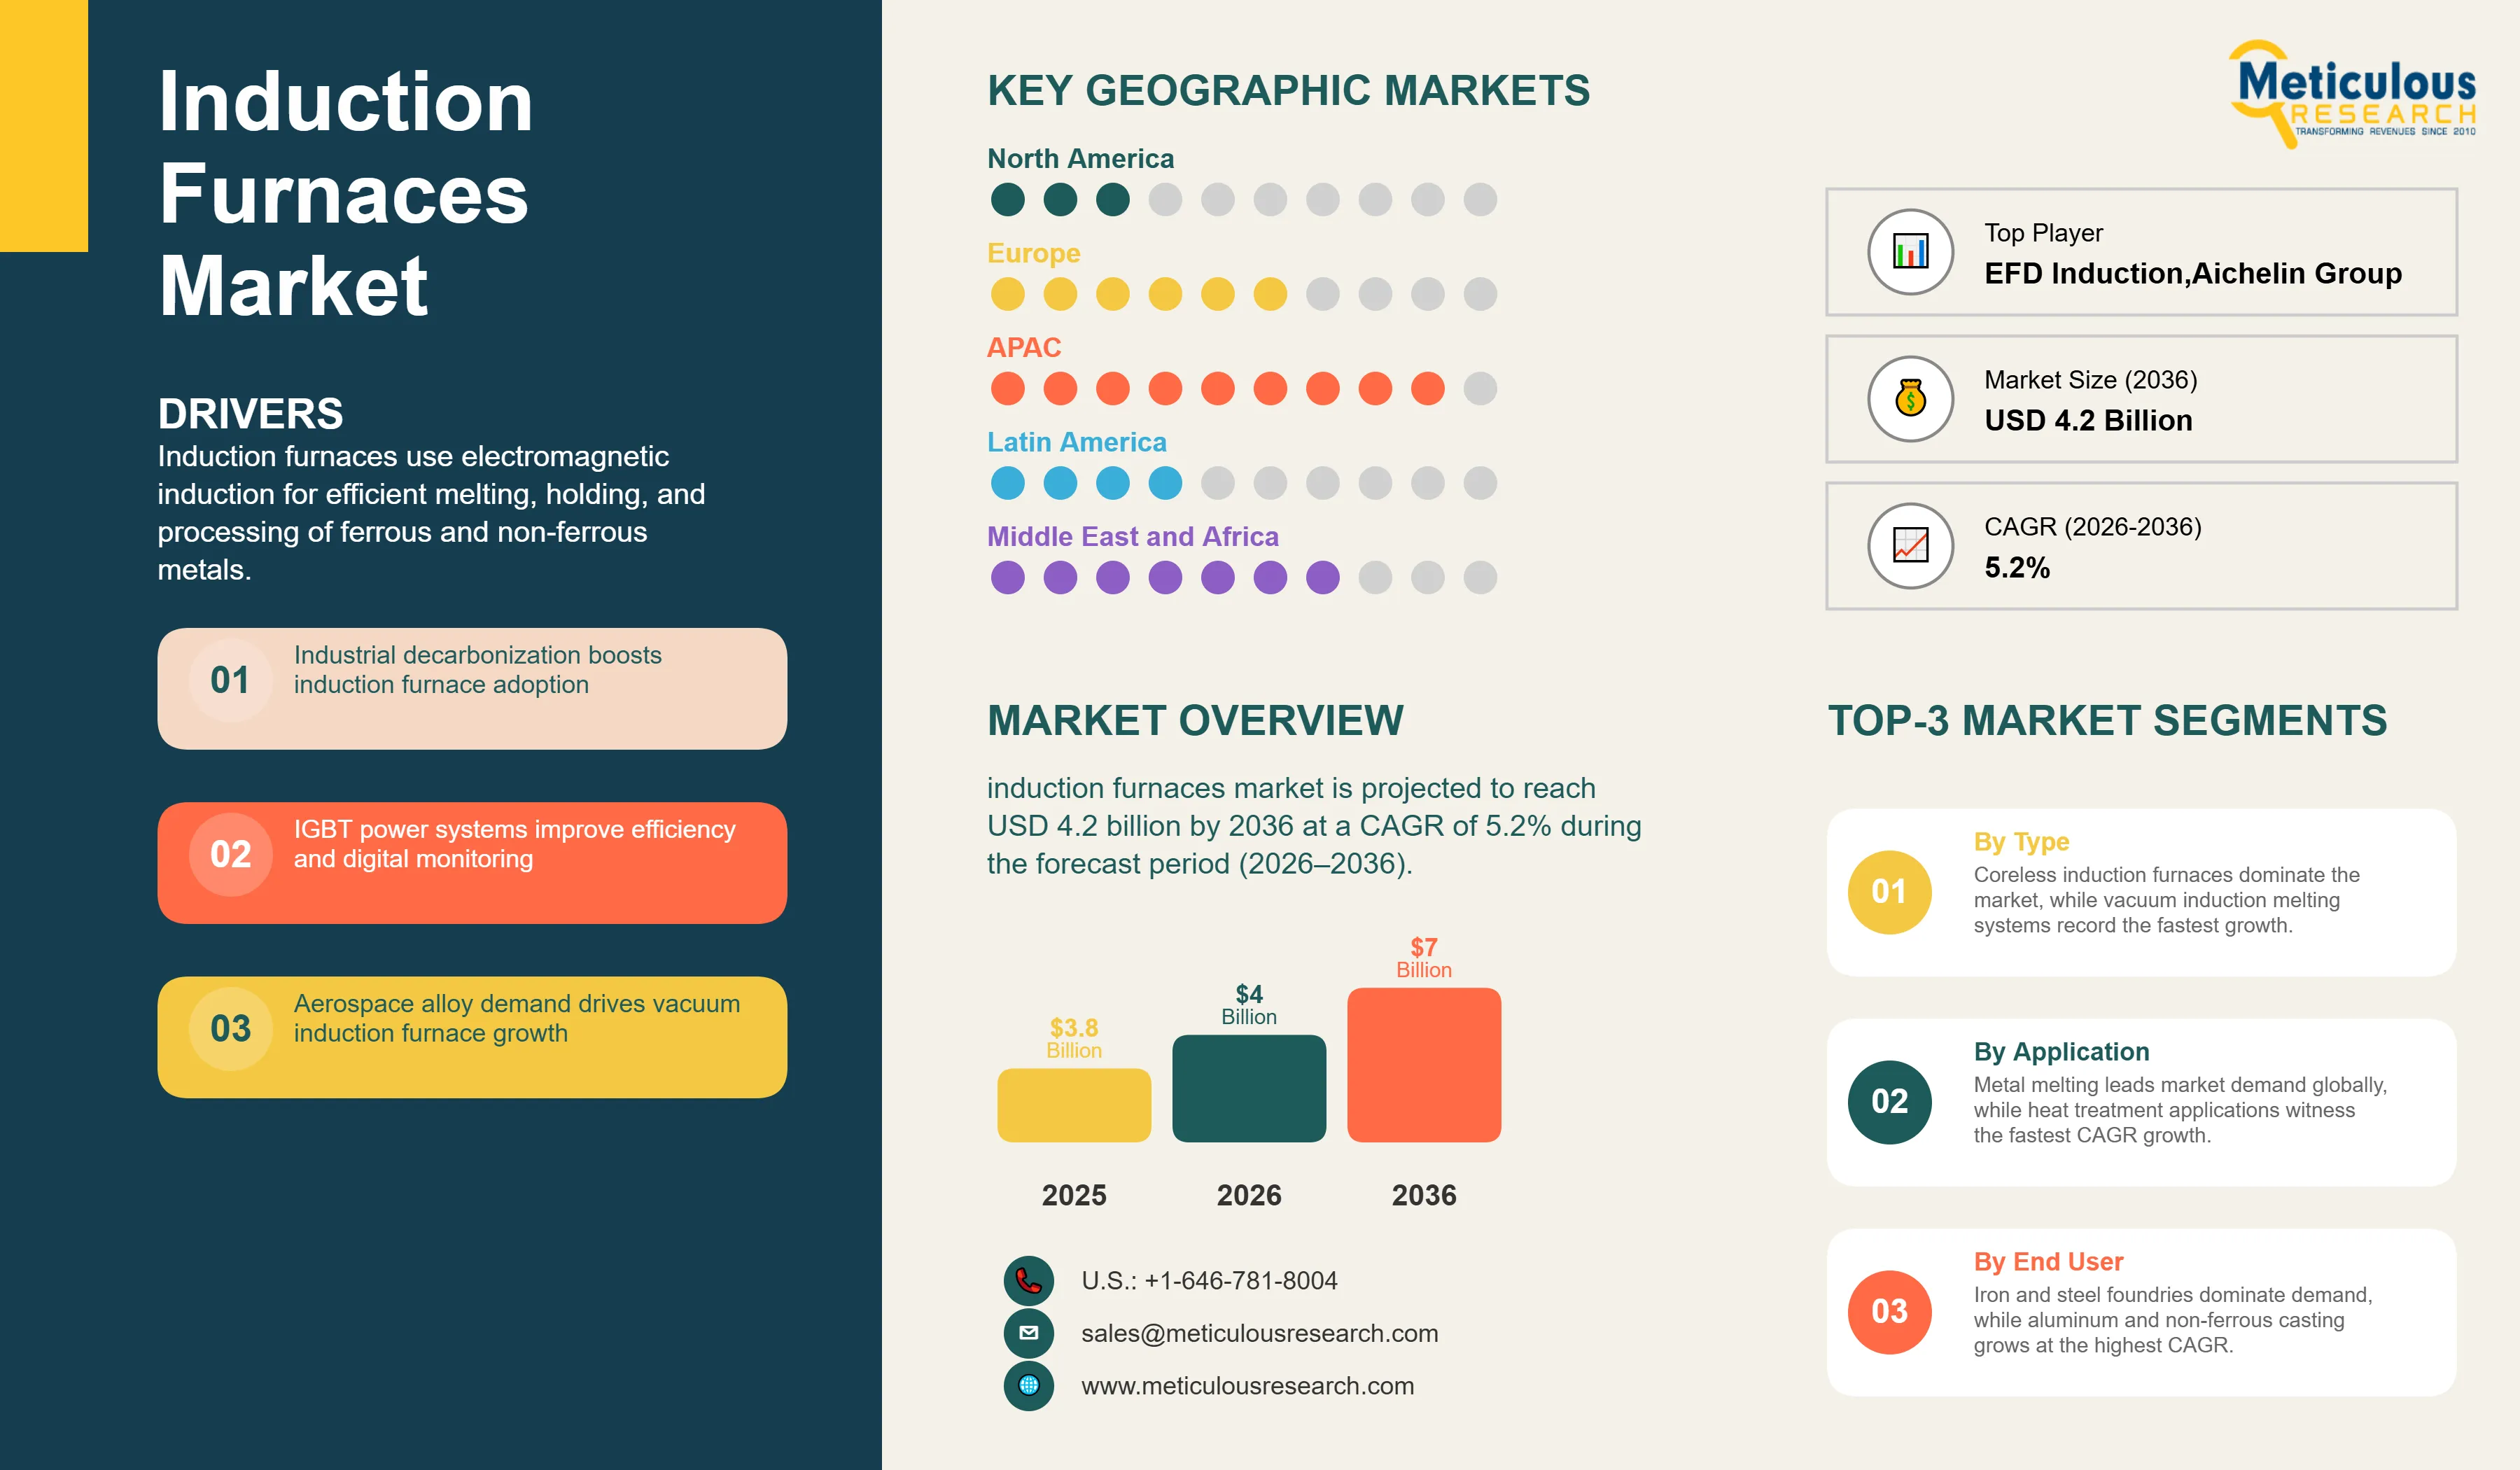
The global induction furnaces market was valued at USD 2.4 billion in 2025. The market is projected to reach USD 4.2 billion by 2036, growing from USD 2.5 billion in 2026 at a CAGR of 5.2% during the forecast period (2026–2036).
- Published
- May 2026
- Pages
- 287
- Format
- PDF + Excel
- Report ID
- MR-1990
- Base year
- 2025
- 2025 · BASELINE
- $2.40B
- 2036
- $4.20B
- CAGR 2026–2036
- 5.2%
2025 baseline · 2026–2036 forecast at 5.2% CAGR · hover a bar for the value
Key highlights
The global induction furnaces market is projected to reach USD 4.2 billion by 2036.
The market is expected to grow at a CAGR of 5.2% during the forecast period 2026–2036.
The total induction furnaces industry was valued at USD 2.4 billion in 2025 and is estimated to reach USD 2.5 billion in 2026.
Asia Pacific is expected to dominate this market with the largest revenue share in 2026, driven by the concentration of global steel and iron foundry production across China, India, Japan, and South Korea, the extensive installed base of induction melting systems in the Indian secondary steel sector, and sustained capital investment in foundry modernization and capacity expansion across the region's automotive and engineering goods supply chains.
Middle East & Africa is projected to witness the fastest revenue growth during the forecast period, driven by greenfield investments in steel manufacturing capacity aligned with economic diversification programs in Saudi Arabia and the UAE, the expanding mining and mineral processing sector across Sub-Saharan Africa, and increasing industrial electrification supported by government incentive programs for energy-efficient manufacturing infrastructure.
By furnace type, the coreless induction furnaces segment is expected to hold the largest share of the market in 2026, driven by its established position as the primary melting technology for iron, steel, and non-ferrous metals across foundry and secondary steelmaking operations globally.
By furnace type, the vacuum induction melting furnaces segment is projected to register the highest growth during the forecast period, driven by growing demand for high-purity nickel-based superalloys, titanium alloys, and specialty steels in aerospace, defense, and advanced energy applications.
By application, the metal melting segment is expected to account for the largest share of the market in 2026.
By application, the heat treatment segment is projected to register the highest growth during the forecast period, driven by the expanding use of induction hardening, tempering, and annealing systems in automotive drivetrain components and precision-engineered industrial parts manufacturing.
By capacity, the 1 to 10 tons segment is expected to account for the largest share in 2026, reflecting its prevalence across the global iron and steel foundry industry.
By capacity, the 10 to 50 tons segment is projected to register the highest CAGR during the forecast period, driven by large-scale foundry modernization and secondary steelmaking capacity expansion across India and Southeast Asia.
By end-use industry, the iron and steel foundry segment is expected to account for the largest share in 2026, while the aluminum and non-ferrous metal casting segment is projected to register the highest CAGR during the forecast period.
By geography, Asia Pacific is expected to dominate the market in 2026, while Middle East & Africa is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 7.0 Billion |
| Market Size in 2026 | USD 4.0 Billion |
| Market Size in 2025 | USD 3.8 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 5.8% |
| Format | PDF, Excel & Cloud Portal · 287 pages |
| Dominating Furnace Type | Coreless Induction Furnaces |
| Fastest Growing Furnace Type | Vacuum Induction Melting Furnaces |
| Dominating Application | Metal Melting |
| Fastest Growing Application | Heat Treatment |
| Dominating Capacity | 1 to 10 Tons |
| Fastest Growing Capacity | 10 to 50 Tons |
| Dominating End-use Industry | Iron and Steel Foundry |
| Fastest Growing End-use Industry | Aluminum and Non-ferrous Metal Casting |
| Dominating Geography | Asia Pacific |
| Fastest Growing Geography | Middle East & Africa |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report infographic
Market dynamics
1 factors across 1 forceIGBT Solid-State Power Supply Technology Displacing Thyristor-Based Systems and Enabling Connected Furnace Monitoring Platforms
The shift from conventional thyristor-based (SCR) power supplies to insulated gate bipolar transistor (IGBT) solid-state platforms represents one of the most significant product-level trends shaping the competitive landscape for induction furnace manufacturers in new installations. While thyristor-based medium-frequency systems have historically dominated induction melting applications, they typically provide less precise control, lower power factor, and higher harmonic distortion compared with modern IGBT-based technologies. In contrast, IGBT systems enable more accurate power modulation, reduced harmonic content, improved power factor, and, in many cases, substantial reductions in energy consumption and reactive power-related infrastructure costs. For foundry operators, where electricity frequently represents the largest share of operating expenses, these efficiency improvements can enhance operating economics and improve the return on investment for both retrofit and greenfield projects.
Inductotherm Group, the world's leading manufacturer of induction melting equipment, has integrated IGBT technology across its medium-frequency power supply product lines, enabling the company to offer solid-state systems that combine high energy efficiency with digital process control interfaces that record power consumption, heat cycle data, and operational parameters for reporting and process optimization. EFD Induction, the leading European and global supplier of induction heating systems, similarly deploys IGBT-based solid-state technology across its heating product range, enabling the integration of programmable process controllers and real-time monitoring capabilities that support lean manufacturing and traceability requirements in automotive and aerospace supply chains. Ajax Tocco Magnethermic, a major North American supplier of induction heating and melting systems, has similarly updated its power supply platform to IGBT-based architectures that support remote diagnostics and connectivity integration.
The commercial availability of connected induction furnace systems built on IGBT power supply platforms is enabling a transition toward service-based business models for equipment manufacturers, where aftermarket support, remote performance monitoring, process optimization consulting, and energy benchmarking services create recurring revenue streams alongside capital equipment sales. For large industrial operators managing multiple furnace installations across distributed facilities, the ability to monitor furnace performance remotely, track energy consumption per heat, and receive predictive maintenance alerts based on real-time operational data represents a meaningful operational advantage that is influencing procurement preferences toward manufacturers capable of delivering integrated digital platforms alongside furnace hardware.
Vacuum Induction Melting Furnace Demand Expanding from Aerospace Superalloy Manufacturing, Defense Production, and Advanced Energy Applications
The vacuum induction melting furnace segment is experiencing structural demand growth driven by the intersection of three reinforcing forces: the production ramp-up of commercial and military aircraft requiring nickel-based superalloy components, rising defense procurement budgets directing investment toward advanced materials supply chains, and the expanding use of specialty alloys in next-generation energy infrastructure including advanced nuclear reactors and large-scale industrial gas turbines. Vacuum induction melting is the foundational processing step for producing nickel-based superalloys such as Inconel, Waspaloy, and René alloy families, as well as for titanium and titanium aluminide alloys, cobalt-based alloys, and high-strength specialty steels that cannot be melted in open-air induction systems without unacceptable oxidation and contamination. The quality and compositional control achievable in VIM processing is a prerequisite for the mechanical and fatigue performance specifications demanded in rotating turbine components, airframe structural members, and propulsion system hardware across both commercial and defense aerospace applications.
Consarc Corporation, a subsidiary of Inductotherm Group, is a leading supplier of vacuum induction melting (VIM) systems, offering solutions that range from laboratory-scale equipment to large production furnaces designed for diverse alloy development and manufacturing applications. ALD Vacuum Technologies, a Germany-based specialist in vacuum and controlled-atmosphere metallurgical systems, also provides an extensive VIM portfolio widely used by superalloy manufacturers and aerospace suppliers for first-melt and specialty alloy production. Retech Systems similarly serves the specialty vacuum melting segment, including applications involving reactive and high-purity metals such as titanium and zirconium that may require skull melting or other contamination-controlled processes.
Demand for VIM furnaces is also being reinforced by the expanding use of high-performance alloys in advanced energy infrastructure. Nickel-based superalloys continue to play a critical role in industrial gas turbines for power generation, where ongoing efficiency improvements are driving higher temperature and performance requirements. In addition, emerging small modular reactor (SMR) programs across the United States, United Kingdom, Canada, and parts of Asia are expected to support long-term demand for corrosion-resistant nickel alloy components and related specialty materials, although the specific melting technologies used will vary depending on the component and supply chain requirements.
Table of contents
12 chapters · 134 sections · 287 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Furnace Type | Coreless Induction Furnaces | Vacuum induction melting furnaces |
| By Application | Metal Melting | Heat treatment |
| By Capacity | 1 to 10 Tons | — |
| By End-use Industry | Iron and Steel Foundry | Aluminum and non-ferrous metal casting |
By Furnace Type
- The Coreless Induction Furnaces Segment to Dominate the Global Induction Furnaces Market
- The induction furnaces industry is segmented into coreless induction furnaces, channel induction furnaces, vacuum induction melting furnaces, and induction skull melting furnaces.
- The coreless induction furnaces segment is expected to account for the largest share of this market.
- The leading position of this segment is attributed to its function as the foundational melting technology across the global iron and steel foundry industry, where coreless systems enable batch melting of scrap and pig iron charges to produce cast iron, ductile iron, and steel castings for automotive, infrastructure, and general engineering applications.
- Coreless induction furnaces operate using an alternating magnetic field generated by a water-cooled copper coil surrounding a refractory crucible, which induces eddy currents and resistive heating directly within the metal charge, delivering high melting rates, precise temperature control, and metallurgical flexibility that no alternative technology can match at comparable scale and cost for batch foundry operations.
- Inductotherm Group, the global market leader in induction melting systems, and OTTO JUNKER GmbH, a leading European manufacturer of both coreless and channel systems, exemplify the depth of product development investment that continues to sustain this segment's dominant commercial position.
- However, the vacuum induction melting furnaces segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by the accelerating demand for nickel-based superalloys and titanium alloys in commercial and military aerospace programs, the structural expansion of advanced manufacturing supply chains requiring VIM-processed specialty materials, and the growing use of high-performance alloys in industrial gas turbines and advanced energy infrastructure.
- The high per-unit value of vacuum induction melting systems and the premium placed on processing capability and metallurgical quality assurance features in aerospace and defense procurement are additionally supporting revenue growth rates in this segment that significantly outpace those of conventional melting equipment categories.
By Application
- The Metal Melting Segment to Hold the Largest Share
- The induction furnaces industry is segmented into metal melting, metal holding and pouring, heat treatment, and hot forming.
- The metal melting segment is expected to account for the largest share of this market.
- The dominant position of the metal melting application reflects the primary commercial purpose for which induction furnace technology was developed and continues to be most widely deployed, encompassing the melting of iron, steel, aluminum, copper, and specialty metal charges in foundry and steelmaking operations that collectively represent the broadest and highest-volume category of induction furnace use globally.
- The metal melting segment is characterized by large-scale capital investment cycles tied to foundry capacity expansion, facility modernization, and the replacement of aging fuel-fired melting equipment with energy-efficient induction alternatives, particularly across Asia Pacific where new foundry capacity additions are occurring at a pace that has no equivalent in mature market regions.
- However, the heat treatment segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by the expanding adoption of induction hardening, tempering, annealing, and normalizing systems in automotive drivetrain and chassis component manufacturing, where the precision and repeatability of induction heat treatment methods deliver superior dimensional control and metallurgical consistency compared with conventional batch furnace alternatives.
- The rapid growth of electric vehicle production globally is creating particularly strong demand for induction heat treatment systems capable of processing precision-hardened components including electric motor shafts, reduction gear assemblies, and bearing races to tight case depth and hardness specifications.
- EMAG eldec, EFD Induction, and Ajax Tocco Magnethermic are among the leading manufacturers investing in application-specific induction hardening and heat treatment system development for automotive and precision engineering customers, underscoring the strong commercial momentum in this application segment.
By Capacity
- The 1 to 10 Tons Segment to Account for the Largest Share
- The induction furnaces industry is segmented into below 1 ton, 1 to 10 tons, 10 to 50 tons, and above 50 tons.
- The 1 to 10 tons segment is expected to account for the largest share of this market.
- This growth is primarily driven by the widespread deployment of systems in this capacity range across the global iron and steel foundry industry, where the majority of independent foundries producing castings for automotive, agricultural equipment, and general engineering applications operate melting systems within this capacity band as the optimal balance between production flexibility, energy efficiency, and capital investment scale.
- The 1 to 10 ton capacity range also aligns closely with the standard charge weight requirements of the Indian induction furnace-based secondary steel sector, which represents one of the largest concentrations of induction melting equipment in the world and constitutes a structurally important demand base for manufacturers active in the Asia Pacific region.
- However, the 10 to 50 tons segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by the scaling of induction-based steelmaking capacity in India and Southeast Asia, where operators are investing in higher-capacity systems to improve throughput and reduce per-tonne energy consumption as they expand production to serve growing domestic demand for structural steel, reinforcing bar, and engineering steel products.
- The progressive shift of larger foundries and mini-mill operators from electric arc furnace technology to medium-frequency induction melting systems for specific product grades, driven by the superior metallurgical control and lower electrode consumption costs of induction technology in these applications, is additionally contributing to revenue growth in the higher capacity range over the forecast period.
By End-use Industry
- The Iron and Steel Foundry Segment to Hold the Largest Share
- The induction furnaces industry is segmented into iron and steel foundry, aluminum and non-ferrous metal casting, precious metals and specialty alloys, automotive components manufacturing, aerospace and defense, mining and mineral processing, and other end-use industries.
- The iron and steel foundry segment is expected to account for the largest share of this market, reflecting the status of induction melting as the foundational process technology for the production of cast iron and steel castings consumed in automotive, agricultural, construction, and industrial machinery applications globally.
- The iron and steel foundry sector represents the largest and most geographically distributed end-user base for induction melting equipment, with tens of thousands of independent and captive foundries operating globally across varying scales of production, the majority of which rely on coreless induction melting systems as their primary thermal processing infrastructure.
- In India, the Joint Plant Committee under the Ministry of Steel recognizes the induction furnace route as a critical component of the country's secondary steelmaking infrastructure, highlighting the unique significance of this technology to the Indian industry structure at a scale that has no parallel among other major steel-producing economies.
- However, the aluminum and non-ferrous metal casting segment is projected to register the highest CAGR during the forecast period.
- The high growth of this segment is driven by the structural transformation of the global automotive industry toward battery electric vehicle platforms, where aluminum and aluminum alloy castings for battery enclosures, electric motor housings, structural frames, and thermal management components are consuming induction melting capacity at a rate that significantly exceeds historical growth patterns for non-ferrous foundry operations.
- The lightweighting imperative embedded in both regulatory fuel economy standards and competitive vehicle range targets is compelling automotive manufacturers and their Tier 1 casting suppliers to invest in expanded aluminum melting and holding capacity, creating sustained demand for coreless induction melting systems, channel holding furnaces, and associated ladle and degassing equipment optimized for high-purity aluminum alloy processing.
- In parallel, expanding copper and copper alloy casting operations in electrical infrastructure manufacturing, driven by grid modernization investments and growing demand for EV charging infrastructure components, are adding a secondary growth driver within this segment.
Geographic analysis
Asia-Pacific
Largest shareAsia Pacific is expected to hold the largest market share in 2026, supported by the region’s concentration of steelmaking and foundry activity, especially in China and India. China remains the world’s largest steel producer, while India is a major and fast-growing market for induction furnaces, particularly in the secondary steel and foundry segments. Japan and South Korea also contribute meaningful demand through advanced manufacturing, automotive casting, and precision metal processing applications.
Middle East & Africa
However, the Middle East and Africa market is expected to be among the faster-growing regional markets for induction furnaces over 2026 to 2036, supported by greenfield and brownfield steel investments in the Gulf Cooperation Council countries. Economic diversification programs such as Saudi Vision 2030 and the UAE’s industrial strategy are encouraging investment in domestic metals and steel processing capacity, while Saudi Arabia’s expanding steel sector is likely to support additional demand for electric melting equipment. In Sub-Saharan Africa, growth in mining and mineral processing for copper, cobalt, gold, and other metals is creating demand for induction-based smelting and refining equipment, and the gradual expansion of foundry and engineering goods manufacturing in countries such as South Africa, Kenya, and Nigeria is adding early-stage demand for small and medium-capacity induction systems. Together, these trends suggest a positive long-term growth outlook for the region.
Competitive landscape
- Inductotherm Group (U.S.)
- EFD Induction · Norway
- OTTO JUNKER GmbH · Germany
- Ajax Tocco Magnethermic Corporation (U.S.)
- Electrotherm (India) Limited · India
- Consarc Corporation (U.S.)
- Pillar Induction (U.S.)
- ALD Vacuum Technologies GmbH · Germany
- GH Electrotermia, S.A. · Spain
- Aichelin Group · Austria
- EMAG eldec GmbH · Germany
- Retech Systems LLC (U.S.)
- Fuji Electric Co., Ltd. · Japan
- SMS Group GmbH · Germany
- Tenova S.p.A · Italy
Frequently asked questions
The global induction furnaces market is expected to reach USD 4.2 billion by 2036 from an estimated USD 2.5 billion in 2026, at a CAGR of 5.2% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Induction Furnaces Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1990). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/induction-furnaces-market-6673