Electrical Control Panels Market (2026-2036)
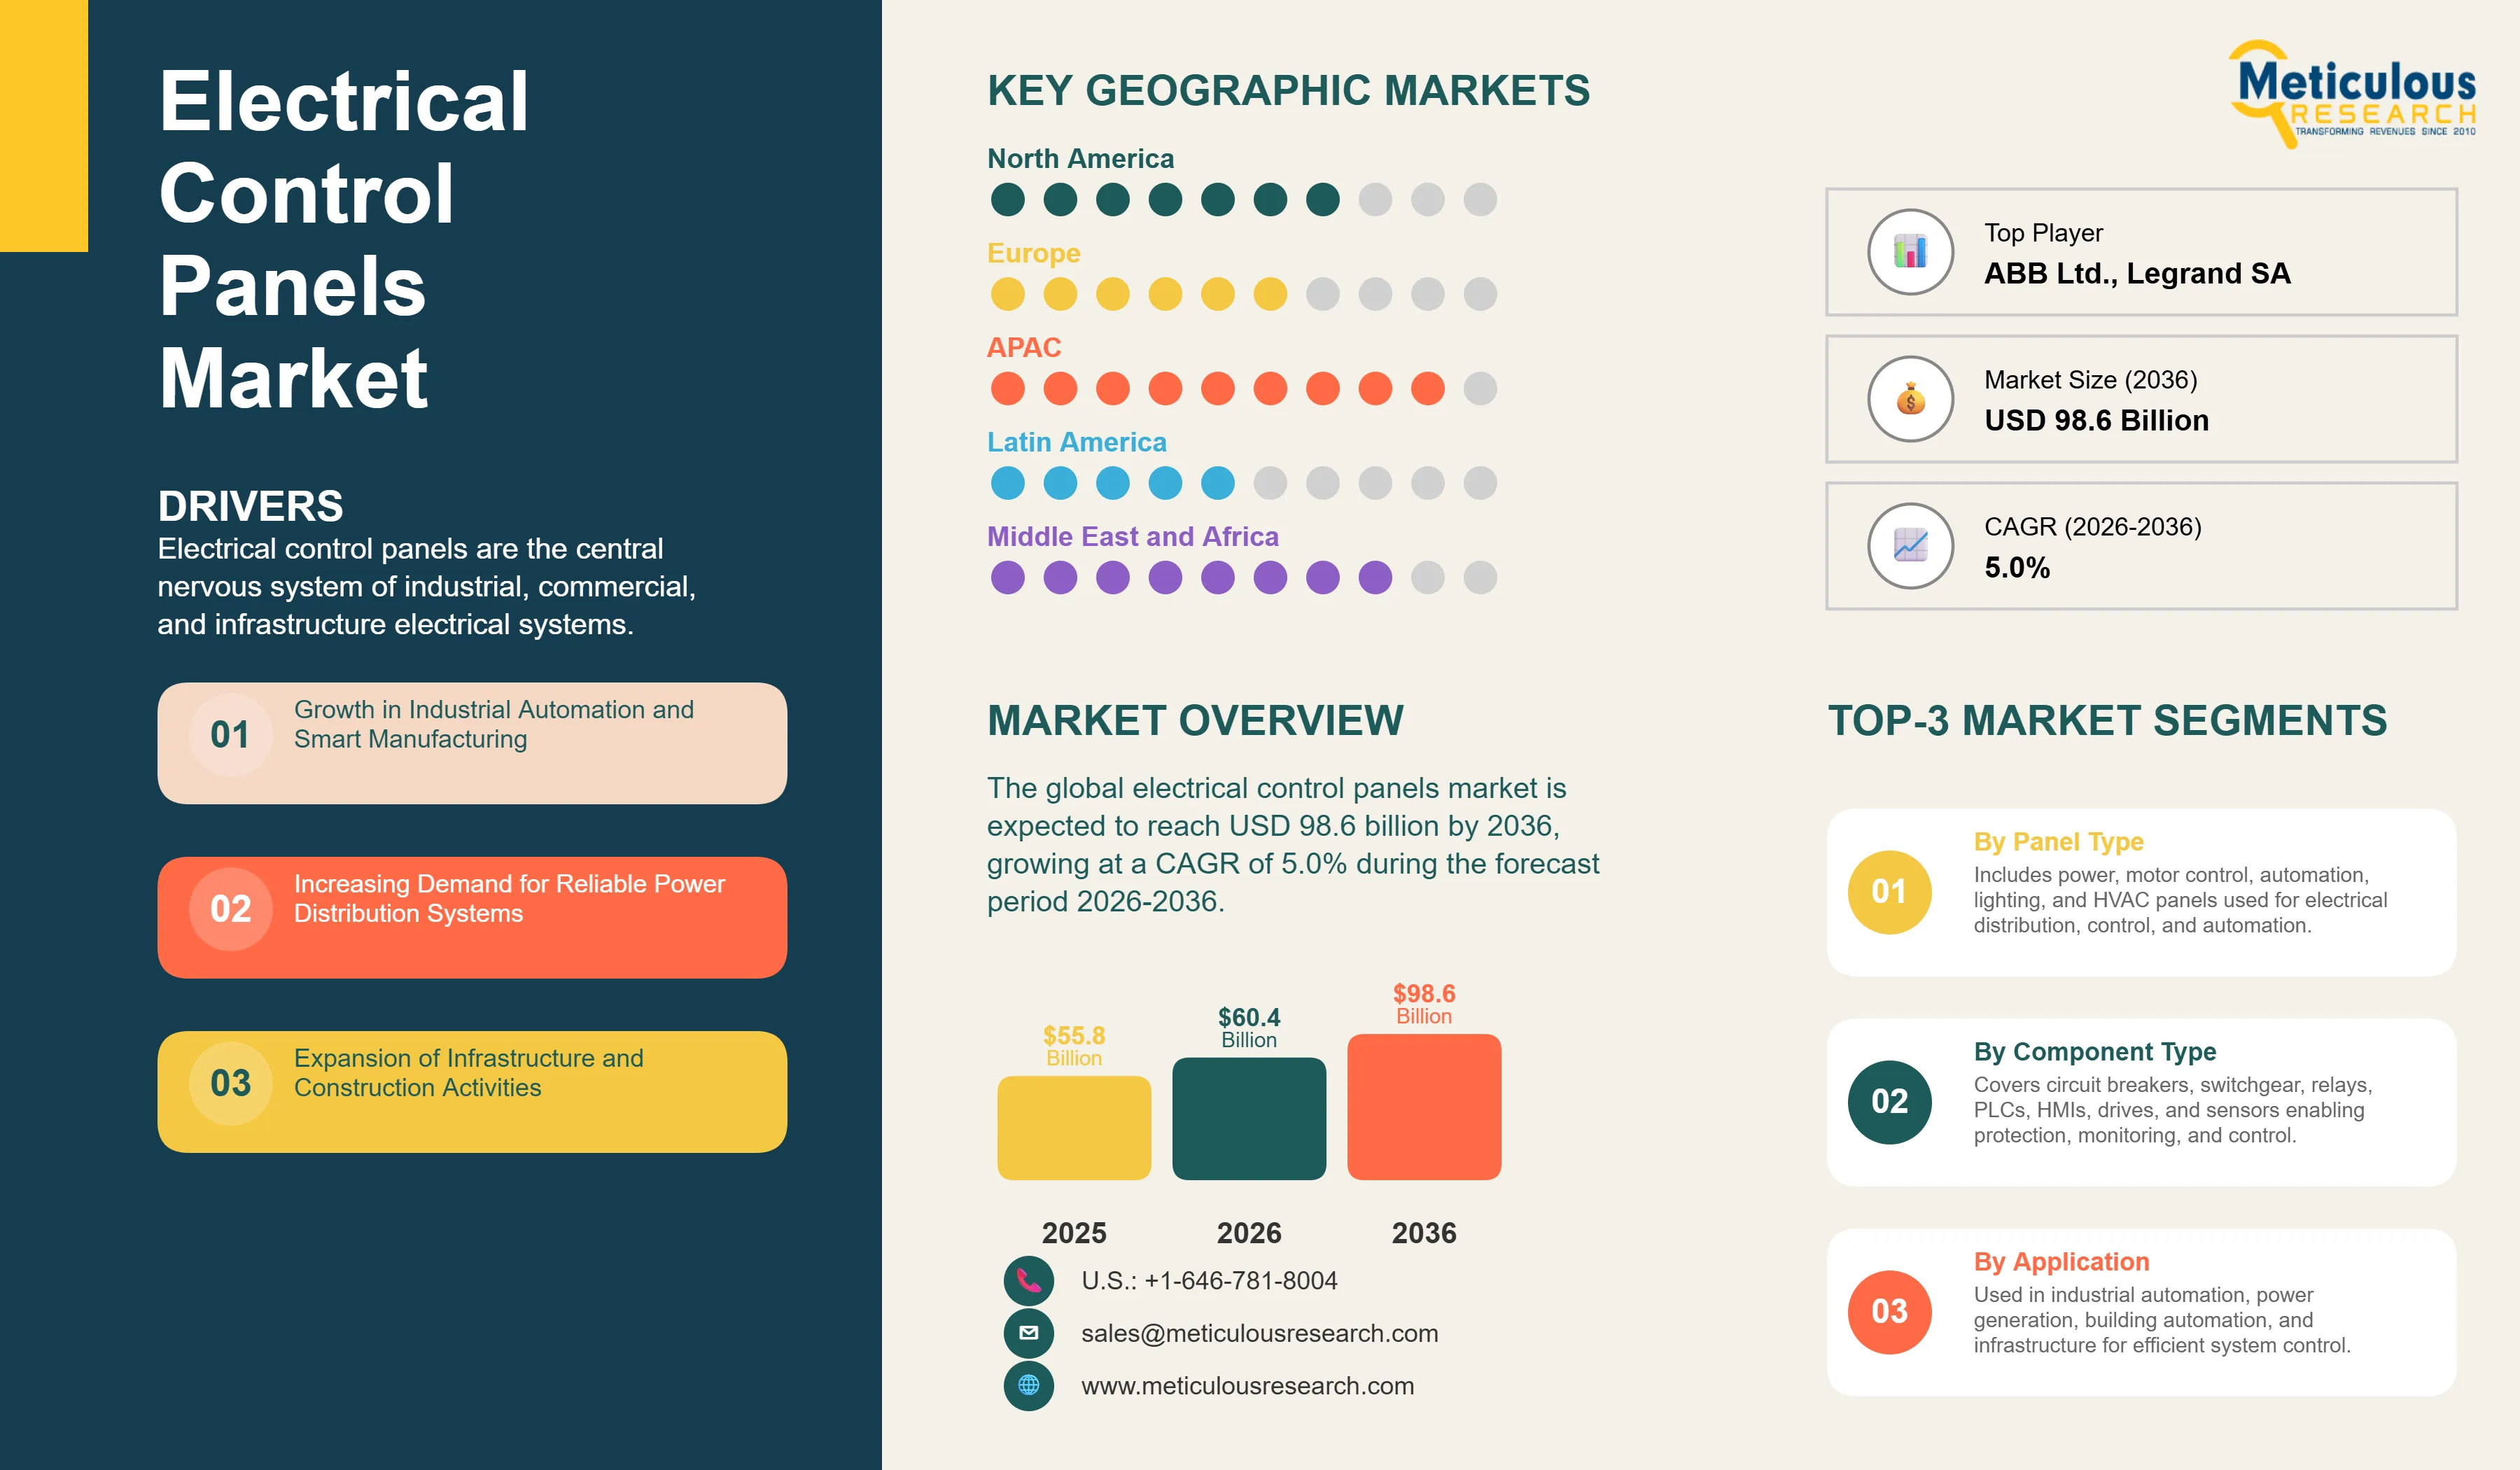
The global electrical control panels market was valued at USD 55.8 billion in 2025. This market is expected to reach USD 98.6 billion by 2036 from an estimated USD 60.4 billion in 2026, growing at a CAGR of 5.0% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 285
- Format
- PDF + Excel
- Report ID
- MREP - 1041941
- Base year
- 2025
- 2025 · BASELINE
- $55.80B
- 2036
- $98.60B
- CAGR 2026–2036
- 5.0%
2025 baseline · 2026–2036 forecast at 5.0% CAGR · hover a bar for the value
Key highlights
The global electrical control panels market is projected to reach USD 98.6 billion by 2036.
The market is expected to grow at a CAGR of 5.0% during the forecast period 2026-2036.
The global market for electrical control panels was valued at USD 55.8 billion in 2025 and is estimated to reach USD 60.4 billion in 2026.
Asia-Pacific is expected to dominate the global market with the largest market share in 2026, while the Middle East and Africa is projected to register the highest CAGR during the forecast period.
By panel type, the power control panels segment is expected to hold the largest share of the market in 2026, while the automation control panels segment is projected to register the highest CAGR during the forecast period.
By component type, the circuit breakers and switchgear segment is expected to hold the largest share in 2026, while the PLCs segment is projected to register the highest CAGR during the forecast period.
By application, the industrial automation segment is expected to hold the largest share in 2026, while the power generation and distribution segment is projected to register the highest CAGR during the forecast period.
By end-use industry, the manufacturing segment is expected to hold the largest share in 2026, while the energy and utilities segment is projected to register the highest CAGR during the forecast period.
By voltage level, the low voltage segment is expected to hold the largest share in 2026, while the medium voltage segment is projected to register the highest CAGR during the forecast period.
By mounting type, the floor-mounted panels segment is expected to hold the largest share in 2026, while the wall-mounted panels segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 98.6 Billion |
| Market Size in 2026 | USD 60.4 Billion |
| Market Size in 2025 | USD 55.8 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 5.0% |
| Format | PDF, Excel & Cloud Portal · 285 pages |
| Dominating Panel Type | Power Control Panels |
| Fastest Growing Panel Type | Automation Control Panels |
| Dominating Component Type | Circuit Breakers and Switchgear |
| Fastest Growing Component Type | Programmable Logic Controllers (PLC) |
| Dominating Application | Industrial Automation |
| Fastest Growing Application | Power Generation and Distribution |
| Dominating End-Use Industry | Manufacturing |
| Fastest Growing End-Use Industry | Energy & Utilities |
| Dominating Voltage Level | Low Voltage |
| Fastest Growing Voltage Level | Medium Voltage |
| Dominating Mounting Type | Floor-Mounted Panels |
| Fastest Growing Mounting Type | Wall-Mounted Panels |
| Dominating Geography | Asia-Pacific |
| Fastest Growing Geography | Middle East & Africa |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: panel type, component type, application, end-use industry-.
Electrical control panels are the central nervous system of industrial, commercial, and infrastructure electrical systems. They house the circuit breakers, contactors, PLCs, drives, and monitoring devices that control and protect electrical equipment ranging from simple lighting circuits to complex automated production lines. Every modern factory, commercial building, power plant, water treatment facility, and data center relies on electrical control panels to manage the flow of electricity to its equipment safely and efficiently.
The market is growing because industrial automation is expanding rapidly across manufacturing sectors globally, and every new automated production line or robotic cell requires dedicated motor control and automation control panels. The global construction boom in infrastructure, commercial real estate, and data centers is generating very large quantities of power distribution and building automation panel demand. The accelerating deployment of solar and wind energy requires specialized control panels for inverter management, grid connection, and protection, adding a significant new demand segment that barely existed a decade ago.
Two key opportunities stand out. The integration of IoT connectivity and smart monitoring into control panels, allowing remote access, real-time diagnostics, and predictive maintenance through cloud platforms, is transforming panels from passive enclosures into intelligent nodes in the industrial internet of things. Simultaneously, the very large installed base of aging control panels in factories and utilities globally that need upgrading to comply with updated safety standards and to interface with new digital control systems is creating a substantial and growing retrofitting market alongside new installation demand.
Report infographic
Market dynamics
7 factors across 3 forcesGrowth in Industrial Automation and Smart Manufacturing
The global expansion of factory automation is the most consistent and reliable demand driver for electrical control panels. Every automated production line, robotic cell, conveyor system, and packaging machine requires motor control panels and automation panels to manage its electrical power and control logic. Global manufacturing investment is growing across automotive, electronics, food processing, pharmaceuticals, and consumer goods industries as companies build new capacity and upgrade existing plants with more automated equipment. The shift from labor-intensive to capital-intensive production models in Asia, combined with reshoring and nearshoring of manufacturing in North America and Europe, is generating sustained investment in new automated facilities that each require significant control panel procurement. Industrial automation investment is not cyclical in the way that some construction markets are: even in slower economic periods, manufacturers continue upgrading to automation to reduce costs and improve quality, providing a stable and growing baseline demand for control panels.
Rising Adoption of Renewable Energy Systems
The global deployment of solar, wind, and battery storage systems is creating structural new demand for specialized electrical control panels that did not exist at significant scale before 2010. A utility-scale solar farm requires dozens of string combiner boxes, inverter control panels, and MV switchboards. A wind farm requires nacelle control panels, HV transformer protection panels, and grid connection switchgear. A grid-scale battery storage system requires battery management system panels, power conversion system controls, and protection switchboards. As global renewable energy capacity continues growing rapidly, driven by falling technology costs and government decarbonization commitments, the demand for renewable energy-specific control panels is growing proportionally, adding a significant new and fast-growing demand category to the electrical control panels market.
Table of contents
14 chapters · 184 sections · 285 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Panel Type | Power Control Panels | Automation control panels |
| By Component Type | Circuit Breakers and Switchgear | PLCs |
| By Application | Industrial Automation | Power generation and distribution |
| By End-Use Industry | Manufacturing | Energy and utilities |
By Panel Type
- Power Control Panels to Dominate
- The global market for electrical control panels is segmented into power control panels, motor control panels, automation control panels, lighting control panels, HVAC control panels, and other control panels.
- The power control panels segment is expected to account for the largest share of the global electrical control panels market.
- Main and sub-distribution boards are required in every commercial, industrial, and infrastructure electrical installation to distribute power from the incoming supply to individual circuits and equipment.
- The universal requirement for power distribution panels across every building and facility type makes this the highest-volume panel category by a significant margin, with every new construction project requiring multiple distribution boards at various levels of the electrical distribution hierarchy.
- However, the automation control panels segment is projected to register the highest CAGR during the forecast period.
- PLC and SCADA panels are growing faster than the overall market as industrial automation investment accelerates and as more previously manual or semi-automated processes are upgraded to fully automated control.
- The ongoing global expansion of manufacturing automation, combined with the growing demand for digital connectivity and remote monitoring in all types of industrial facilities, is driving strong growth in automation panel procurement across most industry sectors.
By Component Type
- Circuit Breakers and Switchgear to Hold the Largest Share
- The circuit breakers and switchgear segment is expected to account for the largest share of the global electrical control panels market.
- Circuit breakers and switchgear are the foundational protection and switching components in every type of electrical control panel and represent the highest total procurement value across the broadest range of panel types from simple distribution boards to complex industrial switchboards.
- Every panel contains circuit breakers at minimum, and many contain multiple layers of switchgear for different protection functions.
- However, the PLCs segment is projected to register the highest CAGR during the forecast period.
- Programmable logic controllers are the intelligence at the heart of automation, motor control, and process control panels, and their adoption is growing rapidly as more industrial and infrastructure systems shift from relay-based to programmable control architectures.
- The expansion of industrial automation and the growing demand for smart, connected panels that can communicate with supervisory systems are both driving strong growth in PLC procurement for new and retrofit panel applications.
By Application
- Industrial Automation to Hold the Largest Share
- The industrial automation segment is expected to account for the largest share of the global electrical control panels market.
- Manufacturing plants, process industries, and automated production facilities represent the largest and most technically demanding application for electrical control panels, requiring motor control centers, PLC automation panels, and sophisticated protection schemes for complex multi-motor drive systems.
- The global scale of manufacturing investment makes industrial automation the dominant application by revenue.
- However, the power generation and distribution segment is projected to register the highest CAGR during the forecast period.
- The renewable energy deployment boom is generating very large and fast-growing procurement of specialized control panels for solar, wind, and battery storage systems.
- Simultaneously, grid modernization programs in both developed and emerging markets are investing in upgraded substation and distribution switchgear that requires new control panel installations.
- The combination of these two demand sources is making power generation and distribution the fastest-growing application segment.
By End-Use Industry
- Manufacturing to Hold the Largest Share
- The manufacturing segment is expected to account for the largest share of the global electrical control panels market.
- Manufacturing encompasses the broadest and most diverse range of electrical control panel applications, from simple motor control for conveyor systems to complex multi-axis robot controllers for automotive production.
- The very large global investment in manufacturing capacity, particularly in Asia, combined with ongoing automation upgrades in developed market factories, generates the highest total panel procurement of any end-use category.
- However, the energy and utilities segment is projected to register the highest CAGR during the forecast period.
- The combination of renewable energy system deployment, grid modernization investment, and new power generation and transmission infrastructure is creating rapidly growing demand for control panels across the energy and utility sector.
- As energy transition investment accelerates globally, this segment is expected to grow significantly faster than manufacturing and other established end-use categories.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global market. The region's dominance reflects the extraordinary scale of its manufacturing and infrastructure sectors. China is by far the world's largest manufacturing economy and also the largest investor in renewable energy, data center infrastructure, and grid modernization, making it the single largest national market for electrical control panels globally. India's rapid industrial expansion, supported by the government's Production Linked Incentive schemes and manufacturing zone development, is generating large control panel demand across automotive, electronics, pharmaceuticals, and food processing sectors. Japan, South Korea, and Taiwan all have very large and sophisticated electronics and semiconductor manufacturing industries that require the highest-specification automation and process control panels. Southeast Asian industrial economies including Vietnam, Thailand, and Indonesia are growing rapidly as manufacturing investment flows into the region from China and from developed market manufacturers seeking to diversify their supply chains. The combination of the world's largest manufacturing investment volumes, very rapid renewable energy deployment, and extensive ongoing infrastructure construction makes Asia-Pacific the dominant region by a large margin.
Middle East & Africa
Fastest growthHowever, the Middle East and Africa region is expected to grow at the fastest CAGR during the forecast period. Saudi Arabia's Vision 2030 transformation program is investing at unprecedented scale in new industrial cities, manufacturing zones, petrochemical complexes, tourism infrastructure, and utility-scale renewable energy, all of which generate large electrical control panel procurement. The UAE's continued expansion as a commercial, logistics, and data center hub is driving commercial building and data center panel demand. Egypt's industrial development programs, Turkey's large manufacturing sector expansion, and the growing economic development investment across Sub-Saharan Africa collectively contribute to the region's above-average growth trajectory. The combination of large new construction programs starting from a lower installed base than mature markets generates the highest percentage growth rate of any region through the forecast period.
North America
North America is a large and technologically sophisticated electrical control panels market, driven by continued manufacturing investment including reshoring programs, major data center construction, infrastructure modernization spending under the U.S. Infrastructure Investment and Jobs Act, and the rapid expansion of renewable energy across solar and wind installations. Rockwell Automation's strong position in the U.S. industrial automation panel market, combined with the broad presence of Schneider Electric, Eaton, and Siemens, gives the market a competitive and innovative supplier ecosystem.
Europe
Europe is characterized by high technical standards, strong demand for energy-efficient and smart panel solutions, and significant industrial automation investment particularly in Germany, which has Europe's most active manufacturing automation market. European renewable energy deployment, particularly in Germany, Spain, and the UK, is also driving growing demand for specialized energy control panels.
Competitive landscape
- Schneider Electric SE · France
- Siemens AG · Germany
- ABB Ltd. · Switzerland
- Eaton Corporation plc · Ireland
- Rockwell Automation Inc. (U.S.)
- Mitsubishi Electric Corporation · Japan
- General Electric Company (U.S.)
- Larsen & Toubro Limited · India
- Fuji Electric Co. Ltd. · Japan
- Delta Electronics Inc. · Taiwan
- Legrand SA · France
- Rittal GmbH & Co. KG · Germany
- Emerson Electric Co. (U.S.)
- Hitachi Ltd. · Japan
- Honeywell International Inc. (U.S.)
Frequently asked questions
The global electrical control panels market is expected to reach USD 98.6 billion by 2036 from an estimated USD 60.4 billion in 2026, at a CAGR of 5.0% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Electrical Control Panels Market - Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MREP - 1041941). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/electrical-control-panels-market-6624