Edge Data Center Market (2024-2031)
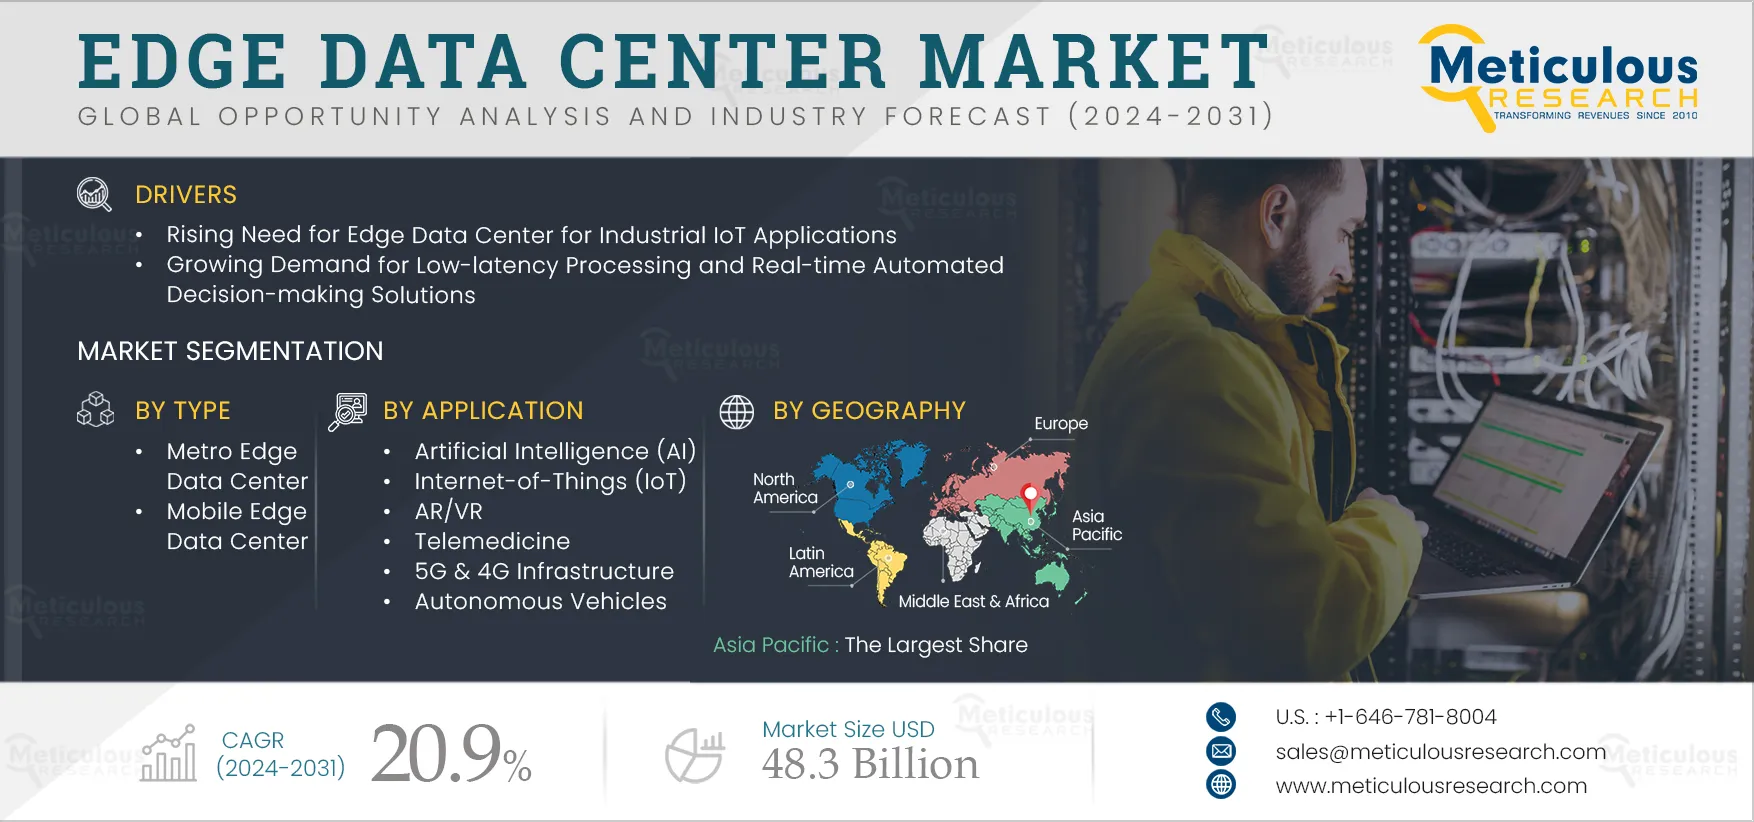
The Edge Data Center market is expected to reach $48.3 billion by 2031, at a CAGR of 20.9% from 2024 to 2031.
- Published
- Jul 2024
- Pages
- 223
- Format
- PDF + Excel
- Report ID
- MR-727
- Base year
- 2023
- 2031 · FORECAST
- $48.30B
- 2031
- $48.30B
- CAGR 2024–2031
- 20.9%
2023 baseline · 2024–2031 forecast at 20.9% CAGR · hover a bar for the value
Key highlights
By Type: The Metro Edge Data Center Segment to Dominate the Edge Data Center Market in 2024
By Component: The Software Segment to Dominate the Edge Data Center Market in 2024
By Deployment Mode: The Cloud-based Deployments Segment to Dominate the Edge Data Center Market in 2024
By Organization Size: The Small & Medium-sized Enterprise Segment to Dominate the Edge Data Center Market in 2024
By Application: The 5G and 4G Infrastructure Segment to Dominate the Edge Data Center Market in 2024
By End-use Sector: The IT & Telecommunications Enterprise Segment to Dominate the Edge Data Center Market in 2024
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 223 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR | 20.9% |
| Market Size | $48.3 Billion by 2031 |
| Segments Covered | By Type · Metro Edge Data Center · Mobile Edge Data Center · By Component · Hardware · Software · Services · Training & Support · Consulting Services · By Deployment Mode · On-premise Deployments · Cloud-based Deployments · By Organization Size · Large Enterprises · Small & Medium-sized Enterprise · By Application · Artificial Intelligence (AI) · Internet-of-Things (IoT) · AR/VR · Telemedicine · 5G & 4G Infrastructure · Autonomous Vehicles · Video/live Streaming · Network Functions Virtualization (NFV) · Other Applications · By End-use Sector · IT & Telecommunications · Automotive · Transportation & Logistics · Healthcare · Energy & Utilities · Manufacturing · Government & Defense · Retail · Other End-use Sectors |
| Countries Covered | Europe (Germany, U.K., France, Italy, Spain, and Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, and Rest of Asia- Pacific), North America (U.S. and Canada), Latin America, and the Middle East & Africa |
| Key Companies Profiles | Dell Technologies Inc. (U.S.), Cisco Systems, Inc. (U.S.), Eaton Corporation plc (Ireland), Fujitsu Limited (Japan), Schneider Electric SE (France), Hewlett-Packard Enterprise Company (U.S.), Huawei Technologies Co., Ltd. (China), IBM Corporation (U.S.), NVIDIA Corporation (U.S.), Mitsubishi Electric Corporation (Japan), Equinix, Inc (U.S.), American Tower Corporation (U.S.), Cyxtera Technologies, Inc. (U.S.), ABB (Switzerland), Nxtra Data Limited (India) (a subsidiary of Bharti Airtel Limited), Zenlayer Inc. (U.S.), Switch, Inc. (U.S.), Vertiv Holdings Co. (U.S.), Nokia Corporation (Finland), EdgeConneX, Inc. (U.S.), Reichle & De-Massari AG (Switzerland), Ubiquity Management, LLC (U.S.), and Vapor IO, Inc. (U.S.) |
Report overview
Segments covered: type, component, deployment, organization, application, end-use sector. Regions: Europe, Asia-Pacific, North America.
The growth of this market is attributed to the rising need for Edge Data Center for industrial IoT applications, the growing demand for low-latency processing and real-time automated decision-making solutions, and the increasing utilization of Edge Data Center in online video streaming. The emergence of autonomous vehicles and the commercialization of 4G technology are expected to generate growth opportunities for the players in the Edge Data Center market.
Market dynamics
4 factors across 3 forcesRising Need for Edge Data Center for Industrial IoT Applications
In recent years, Industrial Internet of Things (IIoT) technologies have evolved rapidly, however, users of IIoT technology are increasingly encountering challenges such as the security of connected infrastructures, data-related issues, scalability difficulties, IoT security, efficient data analysis, and resource shortages. These challenges are impacting productivity and efficiency across various industries. To overcome these issues, industries such as automotive, telemedicine, and telecommunications are adopting Edge Data Center. These centers enable more efficient data collection and management, increase process efficiency, improve network security, and allow for greater network scalability and faster response times.
Edge Data Center offer numerous benefits such as improving security by limiting the quantity of data stored, reducing broader network vulnerabilities, decreasing the amount of sensitive data transmitted, and enabling lower latency. They also enable significantly faster response times and lower the cost of routing and data transmission by placing computation and storage close to the end users. Edge data center solutions are designed to provide low-latency, high-performance connectivity to the cloud, making it easier for Industrial IoT users to adopt low-latency analytics technologies. Thus, the growing adoption of IIoT technology is driving the need for Edge Data Center.
Growing Demand for Low-latency Processing and Real-time Automated Decision-making Solutions
With increasing internet penetration and the increasing usage of smartphones and IoT devices, data traffic is growing exponentially, driving the demand for Edge Data Center. The surge in big data traffic is generating large volumes of data, leading to latency issues and slower network speeds. Hence, there is a growing demand for Edge Data Center to handle massive data volumes and facilitate low-latency processing for real-time automated decision-making is driving the growth of this market.
In traditional big data processing methods, data is stored and processed in batches, which time-consuming. Delays can lead to missed opportunities or inaccurate insights, especially in industries such as finance, healthcare, and telecommunications, where real-time data processing is particularly important.
Ensuring low latency can help businesses increase profits and provide a competitive advantage by enabling them to respond to market changes and customer needs quickly. With data being generated at unprecedented rates, industries must process and analyze that data quickly to gain a competitive edge. Low latency enables the processing and analysis of big data in real time. Additionally, low latency can reduce the load on traditional big data systems by processing only the necessary data in real time, saving costs.
Many ultra-low-latency solutions providers, such as Celoxica Limited (U.K.), Crown Castle Inc. (U.S.), and IPC Systems, Inc. (U.S.), are focused on helping industries manage risks by providing low-latency price discovery and proximity to key financial markets. For instance, in April 2023, IPC Systems, Inc. (U.S.) partnered with Celoxica Limited (U.K.) to deliver FPGA-powered low latency normalized market data feeds across all asset classes. These factors contribute to driving market growth.
Table of contents
14 chapters · 134 sections · 223 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | Metro Edge Data Center | Mobile Edge Data Center |
| By Component | Software | Software |
| By Deployment Mode | Cloud-based Deployments | Cloud-based deployments |
| By Organization Size | Small & Medium-sized Enterprise | Small & medium-sized enterprise |
| By Application | 5G and 4G Infrastructure | Artificial intelligence (AI) |
| By End-use Sector | End-use Sector: The IT & Telecommunications Enterprise | — |
By Type
- The metro Edge Data Center segment accounted for the larger share of over 60.8% of the Edge Data Center market.
- The large market share of this segment is mainly attributed to the growing deployment of 5G networks, increasing data traffic, and the need to provide localized cloud computing resources for businesses and organizations, supporting the segment's growth.
- Metro Edge Data Center are an essential part of the distributed computing infrastructure, as they bring computing resources closer to the source of data generation, consumption, and processing.
- These centers are designed to provide low-latency, high-bandwidth connectivity, and computing resources to support local applications and services.
- However, the mobile Edge Data Center segment is projected to record the highest CAGR during the forecast period.
- The growth of this segment is attributed to factors such as the increasing demand to reduce latency in mobile applications, enhance user experience, enable real-time functionalities, optimize network bandwidth, and alleviate congestion by processing data locally.
- Mobile Edge Data Center (MEC) are an important component of the evolving edge computing ecosystem, catering to the growing demands of emerging technologies.
By Component
- The Software Segment to Dominate the Edge Data Center Market in 2024
- The software accounted for the largest share of over 46.4% of the Edge Data Center market.
- The large share of this segment is mainly attributed to the increasing demand for workload orchestration, resource allocation, real-time data analysis, and insight extraction drive the growth of the software segment.
- Edge data center software plays a critical role in enabling efficient data processing, resource allocation, security, and connectivity within edge computing environments.
- This software encompasses applications, platforms, and tools utilized to manage, orchestrate, and optimize the operations of Edge Data Center.
- Additionally, the software segment is also projected to record the highest CAGR during the forecast period.
By Deployment Mode
- The cloud-based deployments segment accounted for the larger share of over 54.7% of the Edge Data Center market.
- This segment is projected to record the highest CAGR during the forecast period.
- The large share of this segment is mainly attributed to the increasing need to efficiently allocate resources, rapidly deploy applications & services closer to end users and reduce latency while improving performance.
- Cloud computing technology has transformed businesses, enabling scalable and cost-effective data storage, processing, and delivery.
- Additionally, the cloud-based deployments segment is projected to record the highest CAGR during the forecast period.
By Organization Size
- The small & medium-sized enterprise segment accounted for the larger share of over 55.6% of the Edge Data Center market.
- The large share of this segment is mainly attributed to the increasing demand for real-time processing and localized data management, enabling a competitive edge, optimizing operations, and accelerating the digital transformation journey.
- Edge Data Center have emerged as a transformative solution for small and medium-sized enterprises, effectively tackling specific challenges and providing substantial benefits.
- Additionally, the small & medium-sized enterprise segment is projected to record the highest CAGR during the forecast period.
By Application
- The 5G and 4G Infrastructure Segment to Dominate the Edge Data Center Market in 2024
- The 5G & 4G infrastructure segments accounted for the largest share of over 26.2% of the Edge Data Center market.
- The large market share of this segment is mainly attributed to the rising demand for ultra-low latency applications, growing adoption of 5G networks, and growing adoption of Edge Data Center for high bandwidth in 5G infrastructure.
- Edge Data Center play a crucial role in enhancing performance, hosting critical functions, and enhancing the efficiency of both 5G & 4G infrastructures.
- However, the artificial intelligence (AI) segment is projected to record the highest CAGR during the forecast period.
- The growth of this segment can be attributed to factors such as the increasing need for real-time analytics, enhanced data privacy, and reduced network costs.
- Edge artificial intelligence, or AI at the edge, is the implementation of artificial intelligence in an edge computing environment that allows computations where data is collected rather than at a centralized cloud computing facility or an offsite data center.
By End-use Sector
- The IT & Telecommunications Enterprise Segment to Dominate the Edge Data Center Market in 2024
- The IT & telecommunications segment is expected to account for the largest share of over 41.1% of the Edge Data Center market.
- The large share of this segment is mainly attributed to the increasing demand for low-latency and high-bandwidth communication, real-time data processing, and the need to reduce the risk of data breaches during transmission while also ensuring compliance with data protection regulations in the IT & telecommunications sector.
- Additionally, the IT & telecommunications segment is projected to record the highest CAGR during the forecast period.
Geographic analysis
Asia-Pacific
Largest shareIn 2024, Asia-Pacific is expected to account for the largest share of over 36.2% of the Edge Data Center market, followed by North America, Europe, Latin America, and the Middle East & Africa. The Asia-Pacific region is projected to register the highest CAGR during the forecast period. The large share of the Asia-Pacific market is attributed to the growing demand and adoption of advanced technologies, such as IoT and cloud computing, increasing adoption of internet-of-things (IoT) devices, and rising mobile data traffic & over-the-top (OTT) traffic across the region. IoT adoption has accelerated in Asia-Pacific countries. IoT and Edge Data Center are integral components of the modern digital ecosystem. They work together to address the challenges posed by the massive influx of data from IoT devices and enable real-time, low-latency applications across various industries. High investments in smart factories, AR/VR, satellite IoT devices, and 5G IoT are expected to drive the demand for Edge Data Center. Moreover, Asia-Pacific is also projected to register the highest CAGR of 22.5% during the forecast period. Asia-Pacific to Dominate the Edge Data Center Market in 2024
Competitive landscape
- June 2023
IBM (U.S.) announced plans to open its first Europe-based quantum data center to facilitate access to innovative quantum computing for companies, research institutions, and government agencies. The data center is expected to be operational in 2024, with multiple IBM quantum computing systems, each with utility-scale quantum processors, i.e., those of more than 100 qubits.
- May 2023
Megatelecom (Brazil), a telecom operator based in Brazil, announced plans to deploy numerous Edge Data Center across the country and expand its fiber optic network backbone. The company intends to first expand its fiber infrastructure and subsequently establish data centers at these locations.
- April 2023
Nokia (Finland) introduced four third-party applications for MX Industrial Edge (MXIE), a robust on-premises operational technology (OT) edge solution. This solution enables enterprises to securely connect, collect, and analyze data from OT assets at the edge.
- April 2023
NTT Corporation (Japan) collaborated with SES S.A. (Luxembourg) to enable enterprises to build existing network infrastructure and deliver dependable, high-bandwidth, and low-latency connections for multiple use cases operating on a single private 5G network and drive revenue growth across the energy, mining, maritime, manufacturing, and industrial sectors.
- February 2023
NLighten (Germany) launched an edge data center platform in Germany. This advanced edge data center platform offers a step forward for companies wanting to place computing, content, or applications closer to their users.
- Dell Technologies Inc. (U.S.)
- Cisco Systems, Inc. (U.S.)
- Eaton Corporation plc · Ireland
- Fujitsu Limited · Japan
- Schneider Electric SE · France
- Hewlett-Packard Enterprise Company (U.S.)
- Huawei Technologies Co., Ltd. · China
- IBM Corporation (U.S.)
- NVIDIA Corporation (U.S.)
- Mitsubishi Electric Corporation · Japan
- Equinix, Inc. (U.S.)
- American Tower Corporation (U.S.)
- Cyxtera Technologies, Inc. (U.S.)
- ABB · Switzerland
- Nxtra Data Limited · India
- Zenlayer Inc. (U.S.)
- Switch, Inc. (U.S.)
- Vertiv Holdings Co. (U.S.)
- Nokia Corporation · Finland
- EdgeConneX, Inc. (U.S.)
- Reichle & De-Massari AG · Switzerland
- Ubiquity Management, LLC (U.S.)
- Vapor IO, Inc. (U.S.)
Frequently asked questions
The Edge Data Center market is expected to reach $48.3 billion by 2031, at a CAGR of 20.9% from 2024 to 2031.
Cite this report
Meticulous Research. (2024). Edge Data Center Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MR-727). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/edge-data-center-market-5411