Data Center Networking Market (2026-2036)
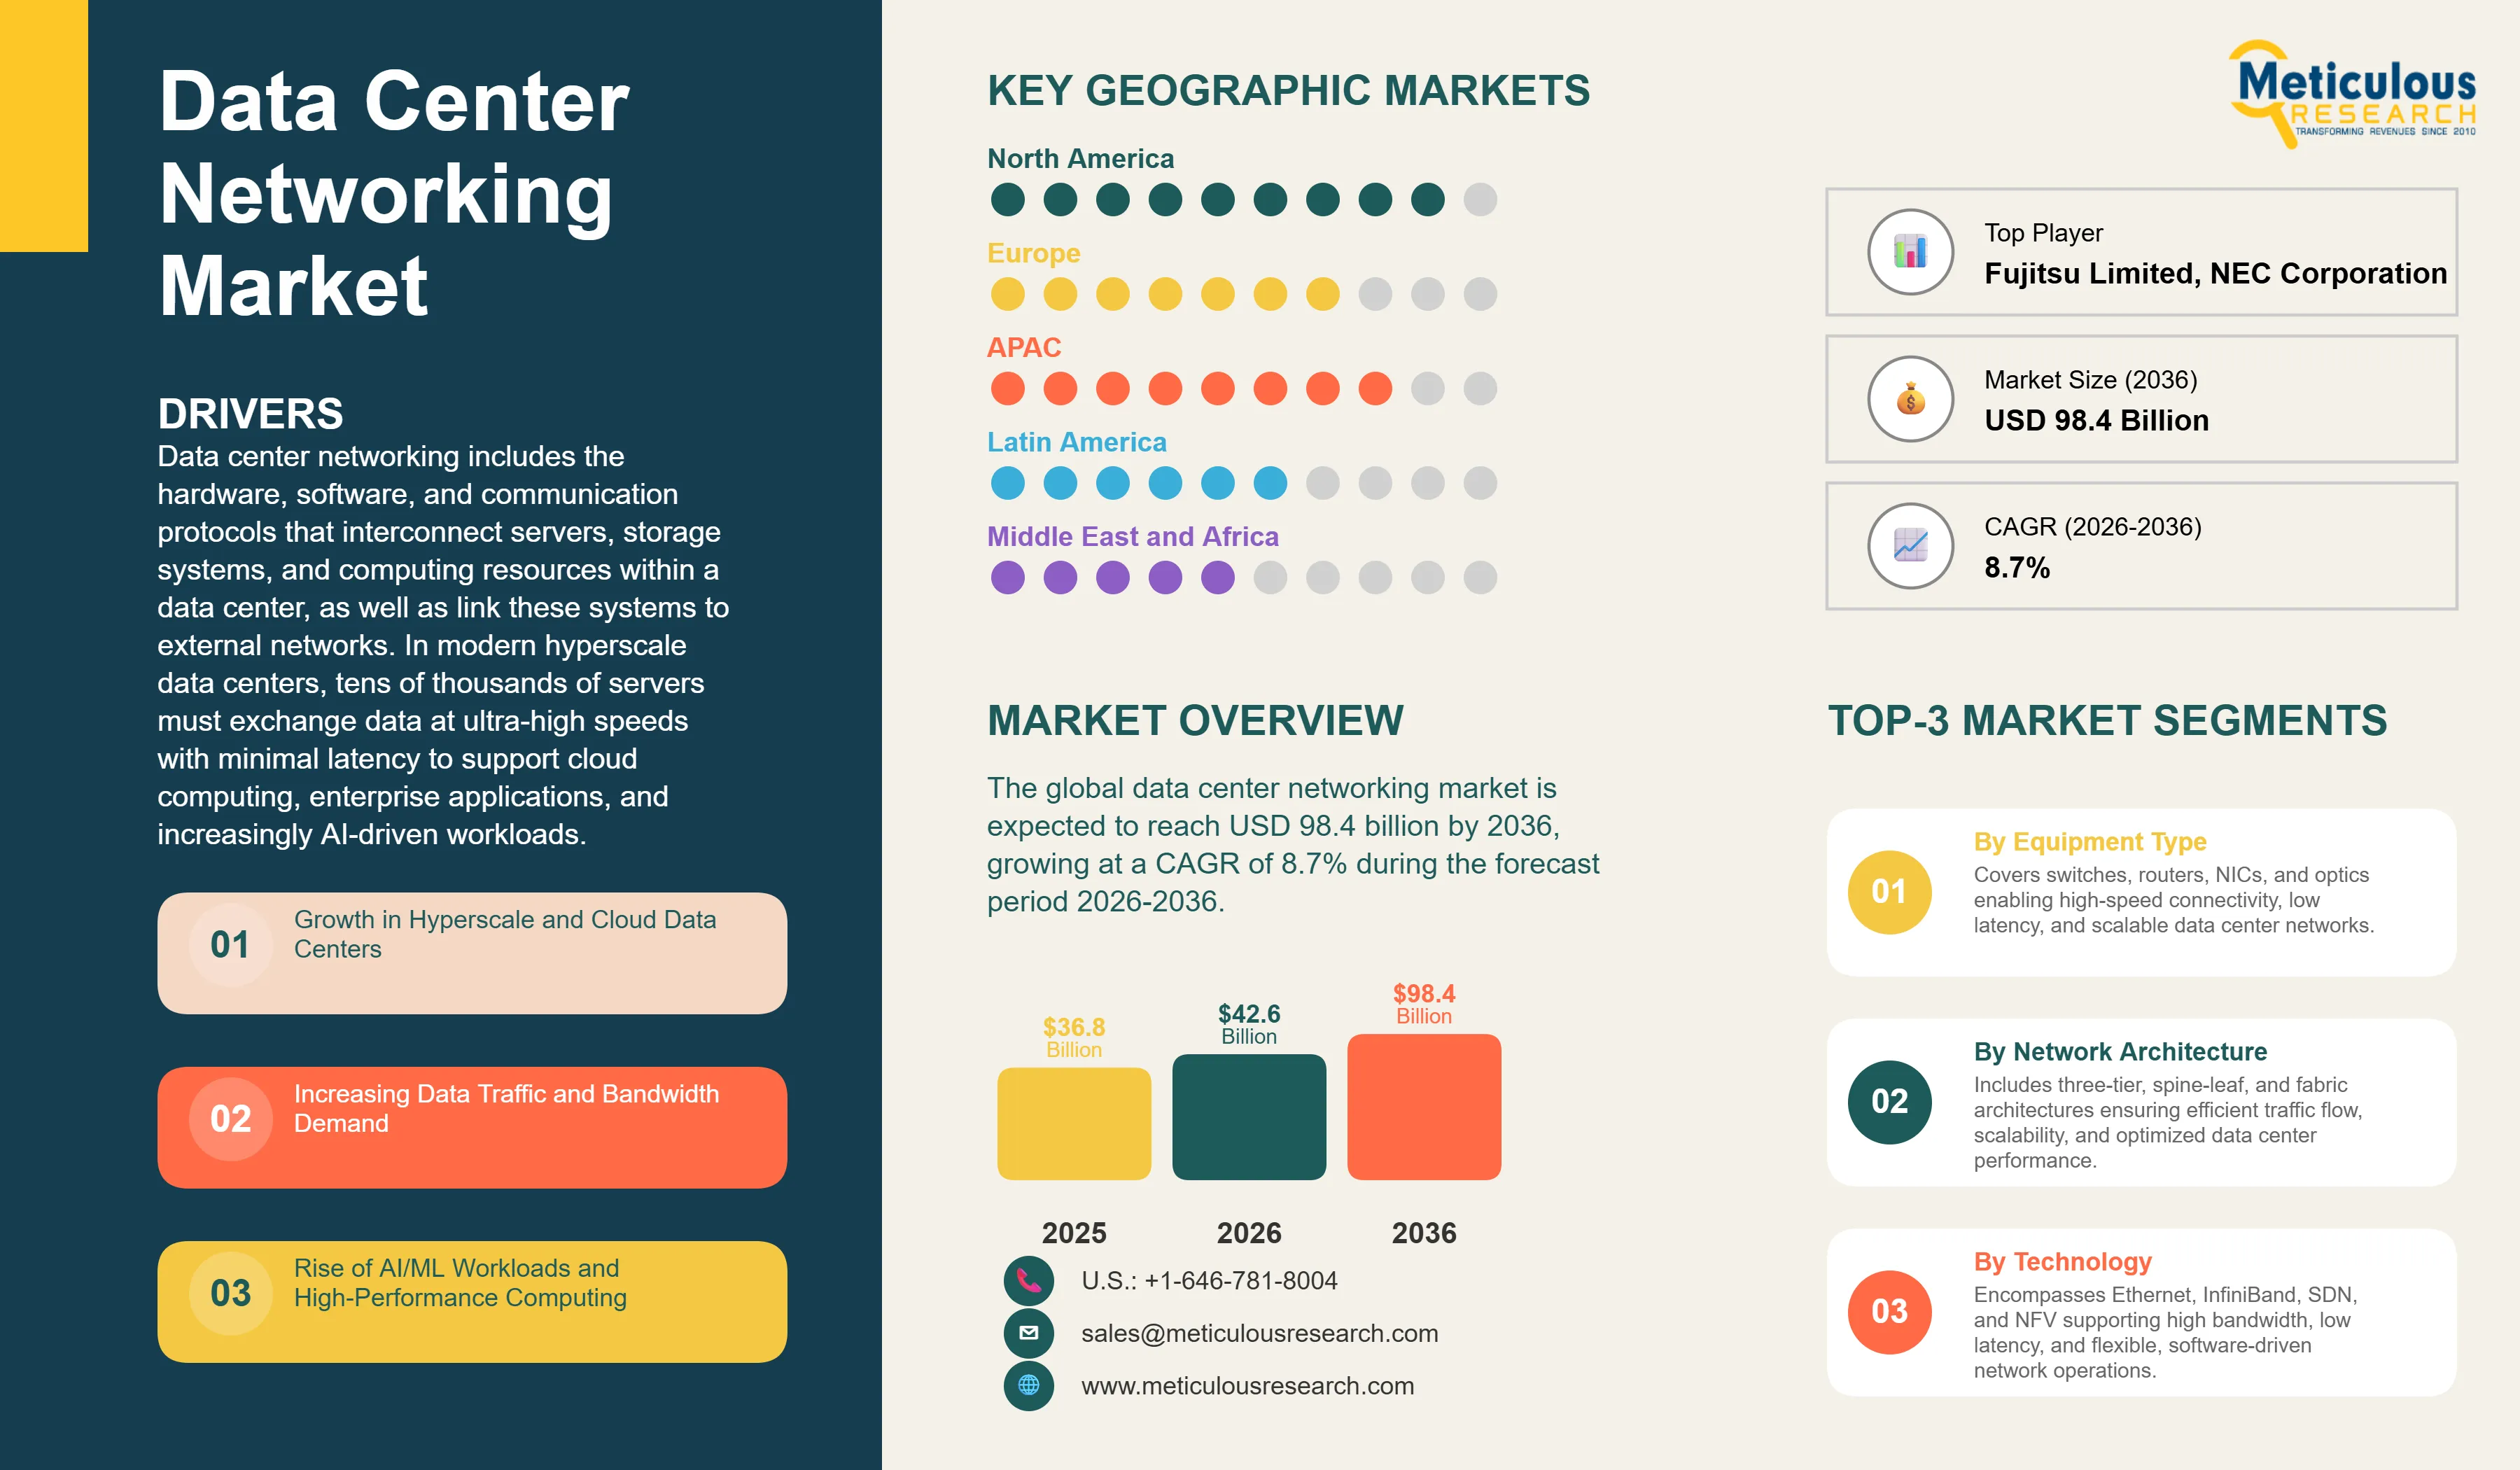
The global data center networking market was valued at USD 36.8 billion in 2025. This market is expected to reach USD 98.4 billion by 2036 from an estimated USD 42.6 billion in 2026, growing at a CAGR of 8.7% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 315
- Format
- PDF + Excel
- Report ID
- MRICT - 1041947
- Base year
- 2025
- 2025 · BASELINE
- $36.80B
- 2036
- $98.40B
- CAGR 2026–2036
- 8.7%
2025 baseline · 2026–2036 forecast at 8.7% CAGR · hover a bar for the value
Key highlights
The global data center networking market is projected to reach USD 98.4 billion by 2036.
The market is expected to grow at a CAGR of 8.7% during the forecast period 2026-2036.
The global market for data center networking was valued at USD 36.8 billion in 2025 and is estimated to reach USD 42.6 billion in 2026.
North America is expected to dominate the global market for data center networking with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By equipment type, the switches segment is expected to hold the largest share of the market in 2026, while the optical transceivers and cables segment is projected to register the highest CAGR during the forecast period.
By network architecture, the spine-leaf architecture segment is expected to hold the largest share in 2026, while the fabric-based architecture segment is projected to register the highest CAGR during the forecast period.
By technology, the 100G Ethernet segment is expected to hold the largest share in 2026, while the 400G/800G Ethernet segment is projected to register the highest CAGR during the forecast period.
By application, the cloud computing segment is expected to hold the largest share in 2026, while the AI and machine learning workloads segment is projected to register the highest CAGR during the forecast period.
By end user, the cloud service providers segment is expected to hold the largest share in 2026, while the enterprises segment is projected to register the highest CAGR during the forecast period.
By data center type, the hyperscale data centers segment is expected to hold the largest share in 2026, while the edge data centers segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 98.4 Billion |
| Market Size in 2026 | USD 42.6 Billion |
| Market Size in 2025 | USD 36.8 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 8.7% |
| Format | PDF, Excel & Cloud Portal · 315 pages |
| Dominating Equipment Type | Switches |
| Fastest Growing Equipment Type | Optical Transceivers and Cables |
| Dominating Network Architecture | Spine-Leaf Architecture |
| Fastest Growing Network Architecture | Fabric-Based Architecture |
| Dominating Technology | Ethernet-Based Networking (100G) |
| Fastest Growing Technology | 400G/800G Ethernet |
| Dominating Application | Cloud Computing |
| Fastest Growing Application | AI and Machine Learning Workloads |
| Dominating End User | Cloud Service Providers |
| Fastest Growing End User | Enterprises |
| Dominating Data Center Type | Hyperscale Data Centers |
| Fastest Growing Data Center Type | Edge Data Centers |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: equipment type, technology, application, end user, data center type.
According to Synergy Research Group, the number of hyperscale data centers operated by major cloud providers reached 1,136 globally at the end of 2024, reflecting record-scale expansion over the past several years. The sector added 137 new hyperscale facilities in 2024, and the global hyperscale footprint continues to grow rapidly as AI-driven demand pushes networking and IT infrastructure requirements higher.
Data center networking includes the hardware, software, and communication protocols that interconnect servers, storage systems, and computing resources within a data center, as well as link these systems to external networks. In modern hyperscale data centers, tens of thousands of servers must exchange data at ultra-high speeds with minimal latency to support cloud computing, enterprise applications, and increasingly AI-driven workloads. The network fabric, comprising switches, routers, security systems, and high-speed optical interconnects, forms a performance-critical backbone, directly influencing application speed, scalability, and reliability. As a result, data center networking remains one of the most frequently upgraded layers of IT infrastructure.
The market is experiencing strong and sustained growth, driven by the convergence of cloud expansion and AI workload proliferation. Global data center traffic continues to rise rapidly, fueled by video streaming, cloud services, and data-intensive enterprise applications. More importantly, the surge in artificial intelligence (AI) training and inference workloads since 2023 has introduced a new class of networking demand. AI clusters require thousands of GPUs to operate in parallel, necessitating ultra-high bandwidth, low-latency interconnects. This has significantly accelerated the adoption of advanced networking technologies such as 400G Ethernet and InfiniBand, particularly in AI-optimized data centers.
A major technology transition is currently underway, with hyperscale operators shifting from 100G to 400G Ethernet as the standard interconnect, while early deployments of 800G infrastructure are gaining momentum. Industry analyses (e.g., Dell'Oro Group) indicate that 400G switch deployments have now overtaken 100G in hyperscale environments, marking a key inflection point in the market. This upgrade cycle is expected to continue through the forecast period, as cloud providers and AI infrastructure builders invest in next-generation networking to support increasingly complex, data-intensive workloads.
Overall, the data center networking market is entering a high-growth phase characterized by rapid bandwidth scaling, shorter technology refresh cycles, and increasing architectural complexity driven by AI and distributed computing demands.
Report infographic
Market dynamics
7 factors across 3 forcesRise of AI/ML Workloads and High-Performance Computing
The commercial deployment of generative AI applications at scale has created a step-change in data center networking requirements that is driving an investment cycle unlike any the industry has seen before. According to Goldman Sachs Research, hyperscale (AI-driven) data center capital expenditure has been rising sharply, with total investments reaching over USD 300 billion annually by 2024, and projected to exceed USD 500 billion by 2026 as AI infrastructure build-out accelerates. NVIDIA's data center revenue, which is the primary proxy for AI compute infrastructure investment, reached USD 60.9 billion in fiscal year 2024, growing over 126% year-on-year, and each NVIDIA GPU cluster requires high-performance networking that is a multiplier of the compute spend. According to NVIDIA's own guidance, networking and interconnect infrastructure typically represents 20 to 30% of total AI cluster cost, meaning NVIDIA's data center revenue implies very large networking infrastructure procurement.
Growth in Hyperscale and Cloud Data Centers
According to Synergy Research Group's 2024 tracking data, global hyperscale data center capacity expanded substantially in 2023 and 2024, with Amazon, Microsoft, Google, and Meta collectively accounting for the majority of new hyperscale deployments. The global cloud computing market, which drives hyperscale data center investment, reached approximately USD 680 billion in revenue in 2024 according to Gartner's forecast, and is projected to continue growing at above-average rates through the forecast period. Each new hyperscale data center facility of 50 to 100 megawatts of IT load capacity requires hundreds of millions of dollars of networking equipment including spine and leaf switches, optical interconnects, and security appliances, making hyperscale expansion the primary near-term demand driver for data center networking hardware.
Table of contents
14 chapters · 172 sections · 315 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Equipment Type | Switches | Optical transceivers and cables |
| By Technology | 100G Ethernet | 400G/800G Ethernet |
| By Application | Cloud Computing | AI and machine learning workloads |
| By Data Center Type | Hyperscale Data Centers | Edge data centers |
By Equipment Type
- Switches to Dominate
- The global market for data center networking is segmented into switches (core, spine, and leaf), routers, network security equipment, load balancers, network interface cards, and optical transceivers and cables.
- The switches segment is expected to account for the largest share of the global data center networking market.
- Data center switches are the fundamental building blocks of every data center network, required at the leaf layer to connect servers, at the spine layer to interconnect leaf switches, and at the core layer to connect to external networks.
- The very large volume of switches required to connect the hundreds of thousands of servers in a hyperscale data center, combined with the ongoing transition from 100G to 400G switches that is driving a multi-year replacement cycle, makes switches the dominant equipment category by revenue.
- However, the optical transceivers and cables segment is projected to register the highest CAGR during the forecast period.
- Every 400G or 800G switch port requires a corresponding optical transceiver, and the transition to higher-speed networking is driving very rapid growth in high-speed transceiver demand.
- Optical transceivers are a consumable infrastructure component that must match every networking speed upgrade, making the transceiver market a leading indicator and proportional beneficiary of each networking technology transition.
By Technology
- 100G Ethernet to Hold the Largest Share
- The 100G Ethernet segment is expected to account for the largest share of the global data center networking market. 100G Ethernet is the current predominant interconnect speed across the large installed base of data center switches globally, having been the standard for hyperscale and enterprise data centers for the past five to six years.
- The large number of data center facilities still operating on 100G infrastructure and the gradual pace at which capacity is upgraded rather than replaced overnight means 100G remains the largest installed base by port count through 2026.
- However, the 400G/800G Ethernet segment is projected to register the highest CAGR during the forecast period, driven by rapidly increasing bandwidth requirements in AI and hyperscale cloud environments.
- The pace of 400G deployment continues to accelerate across hyperscale data centers, particularly to support AI training clusters, east-west traffic growth, and distributed workloads.
- At the same time, the transition toward 800G Ethernet is gaining momentum, with leading cloud providers and AI infrastructure operators beginning to deploy next-generation switches and optical modules to overcome the bandwidth limitations of 400G architectures.
By Application
- Cloud Computing to Hold the Largest Share
- The global market for data center networking is segmented into cloud computing (public, private, and hybrid), AI and machine learning workloads, big data and analytics, content delivery and streaming, enterprise IT applications, and other applications.
- The cloud computing segment is expected to account for the largest share of the global data center networking market.
- Cloud computing is the largest and most dominant application driving data center investment globally.
- According to Gartner's 2024 forecast, worldwide public cloud services revenue reached approximately USD 680 billion in 2024, and the hyperscale cloud operators who run this infrastructure are the world's largest single purchasers of data center networking equipment.
- Amazon Web Services, Microsoft Azure, and Google Cloud collectively spend tens of billions of dollars on networking infrastructure annually.
- However, the AI and machine learning workloads segment is projected to register the highest CAGR during the forecast period.
- The AI infrastructure buildout of 2023 to 2025 has created a new and very fast-growing demand segment for networking equipment specifically optimized for AI cluster interconnects, characterized by very high bandwidth, very low latency, and the use of both Ethernet and InfiniBand fabrics.
- According to IDC's 2024 AI infrastructure spending forecast, global spending on AI infrastructure including servers, storage, and networking is expected to grow at approximately 30% annually through 2028, with networking representing a substantial and growing share of total AI cluster cost.
By Data Center Type
- Hyperscale Data Centers to Hold the Largest Share
- The hyperscale data centers segment is expected to account for the largest share of the global data center networking market.
- Hyperscale data centers operated by Amazon, Microsoft, Google, Meta, and a small number of other large cloud and internet companies are the world's largest individual purchasers of networking equipment, with a single facility of 100 megawatts or more potentially consuming hundreds of millions of dollars of switches, transceivers, and security equipment.
- According to Synergy Research Group, hyperscale operators are responsible for a rapidly growing share of global data center capacity expansion, with 1,136 hyperscale sites worldwide at the end of 2024 and a continuing four-year doubling trend in total hyperscale capacity
- However, the edge data centers segment is projected to register the highest CAGR during the forecast period.
- Edge data centers, which are smaller facilities located close to end users to enable low-latency processing of data from IoT devices, mobile users, and streaming applications, are growing rapidly as 5G deployment creates new latency-sensitive application requirements and as content delivery networks expand their point-of-presence footprints.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global data center networking market. The United States is home to the global headquarters and primary data center operations of Amazon Web Services, Microsoft Azure, Google Cloud, and Meta, which are collectively the world's largest purchasers of data center networking equipment. According to industry reporting, the U.S. is the world’s largest data center market by capacity, and Northern Virginia remains the largest data center cluster globally, with commissioned inventory well above 2.6 GW in 2024 and nearly 5 GW by 2025. The AI infrastructure buildout of 2024 and 2025 has been heavily concentrated in U.S. data center markets, including Northern Virginia, Phoenix, Chicago, and Dallas, driving very large networking equipment procurement. Cisco and Arista are two of the most important North American suppliers in data center networking, reflecting the region’s leadership in high-performance switching and AI-driven infrastructure demand.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific data center networking market is projected to register the fastest CAGR during the forecast period. The region has emerged as the most dynamic global hub for new data center capacity, supported by strong digital demand, expanding cloud adoption, and supportive regulatory environments. According to insights from JLL, Asia-Pacific recorded the highest year-on-year growth in data center construction activity globally across 2023 and 2025, with major investments concentrated in key hubs such as Singapore, Tokyo, and Sydney, alongside rapidly growing secondary markets including Jakarta, Kuala Lumpur, and Mumbai. China continues to be a major driver of regional demand, supported by its large domestic internet ecosystem and hyperscale cloud providers such as Alibaba Cloud, Tencent Cloud, ByteDance, and Huawei Cloud. These companies are investing heavily in high-performance data center infrastructure, including advanced networking, largely independent of Western hyperscale ecosystems. India is emerging as one of the fastest-growing data center markets globally. The country’s capacity is expected to expand significantly in the near term, driven by rapid digitalization, increasing enterprise cloud adoption, and evolving data localization requirements that are encouraging both domestic and global cloud providers to scale local infrastructure. Meanwhile, Singapore continues to serve as a strategic ASEAN data center hub despite land and power constraints, while Australia remains a highly active market with sustained investments in hyperscale and colocation facilities.
Competitive landscape
- Cisco Systems Inc. (U.S.)
- Arista Networks Inc. (U.S.)
- Juniper Networks Inc./HPE (U.S.)
- NVIDIA Corporation (U.S.)
- Hewlett Packard Enterprise (U.S.)
- Huawei Technologies Co. Ltd. · China
- Dell Technologies Inc. (U.S.)
- Extreme Networks Inc. (U.S.)
- Broadcom Inc. (U.S.)
- Lenovo Group Limited · Hong Kong
- Fujitsu Limited · Japan
- NEC Corporation · Japan
- IBM Corporation (U.S.)
- Nokia Corporation · Finland
- ZTE Corporation · China
Frequently asked questions
The global market for data center networking is expected to reach USD 98.4 billion by 2036 from an estimated USD 42.6 billion in 2026, at a CAGR of 8.7% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Data Center Networking Market - Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRICT - 1041947). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/data-center-networking-market-6630