Industrial Cybersecurity Market (2025-2032)
The Industrial Cybersecurity Market was valued at $21.33 billion in 2024. This market is expected to reach $57.6 million by 2032 from an estimated $23.8 billion in 2025, at a CAGR of 13.5% during the forecast period 2025-2032. Industrial Cybersecurity Market Size & Forecast Key factors driving the
- Published
- Feb 2025
- Pages
- 300
- Format
- PDF + Excel
- Report ID
- MRICT - 104630
- Base year
- 2024
- 2024 · BASELINE
- $21.33B
- 2032
- $57.6M
- CAGR 2025–2032
- 13.5%
2024 baseline · 2025–2032 forecast at 13.5% CAGR · hover a bar for the value
Key highlights
By Component: In 2025, the Solutions Segment to Dominate the Industrial Cybersecurity Market
By Security Type: In 2025, the Endpoint Security Segment to Dominate the Industrial Cybersecurity Market
By Deployment Mode: In 2025, the Cloud-Based Deployment Segment to Dominate the Industrial Cybersecurity Market
By End-User: In 2025, the Industrial Manufacturing Segment to Dominate the Industrial Cybersecurity Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | ~300 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR | 13.5% |
| Market Size (2025) | $23.8 billion |
| Market Size (2032) | $57.6 billion |
| Segments Covered | By Component · Solutions · Intrusion Detection/Prevention Systems · Identity & Access Management · Security & Vulnerability Management · Antivirus/Antimalware · Disaster Recovery · Firewalls · Unified Threat Management · Encryption · Risk & Compliance Management · Web Filtering · Data Loss Prevention · Dds Management · Services · Professional Services · Managed Services · By Security Type · Endpoint Security · Network Security · Application Security · Cloud Security · Other Security Types · By Deployment Mode · Cloud-based Deployment · On-premise Deployment · By End-User · Industrial Manufacturing · Automotive · Heavy Metals & Machinery · Aerospace & Defense · Electronics & Electrical · FMCG · Chemicals · Other Manufacturing Industries · Transportation & Logistics · Energy & Utilities · Other End Users |
| Countries/Regions Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Italy, Spain, and Rest of Europe), Asia-Pacific (China, Japan, India, Australia, South Korea, Taiwan, Singapore and Rest of Asia-Pacific), Latin America (Brazil, Mexico, Rest of Latin America), and the Middle East & Africa |
| Key Companies | Fortinet, Inc. (U.S.), Cisco Systems, Inc. (U.S.), Juniper Networks, Inc. (U.S.), Palo Alto Networks, Inc. (U.S.), IBM Corporation (U.S.), Check Point Software Technologies Ltd. (Israel), F5, Inc. (U.S.), Mandiant, Inc. (U.S.), Broadcom, Inc. (U.S.), Oracle Corporation (U.S.), Microsoft Corporation (U.S.), Intel Corporation (U.S.), Imperva, Inc. (U.S.), Cyberark Software Ltd. (U.S.), and RSA Security LLC (U.S.). |
Report overview
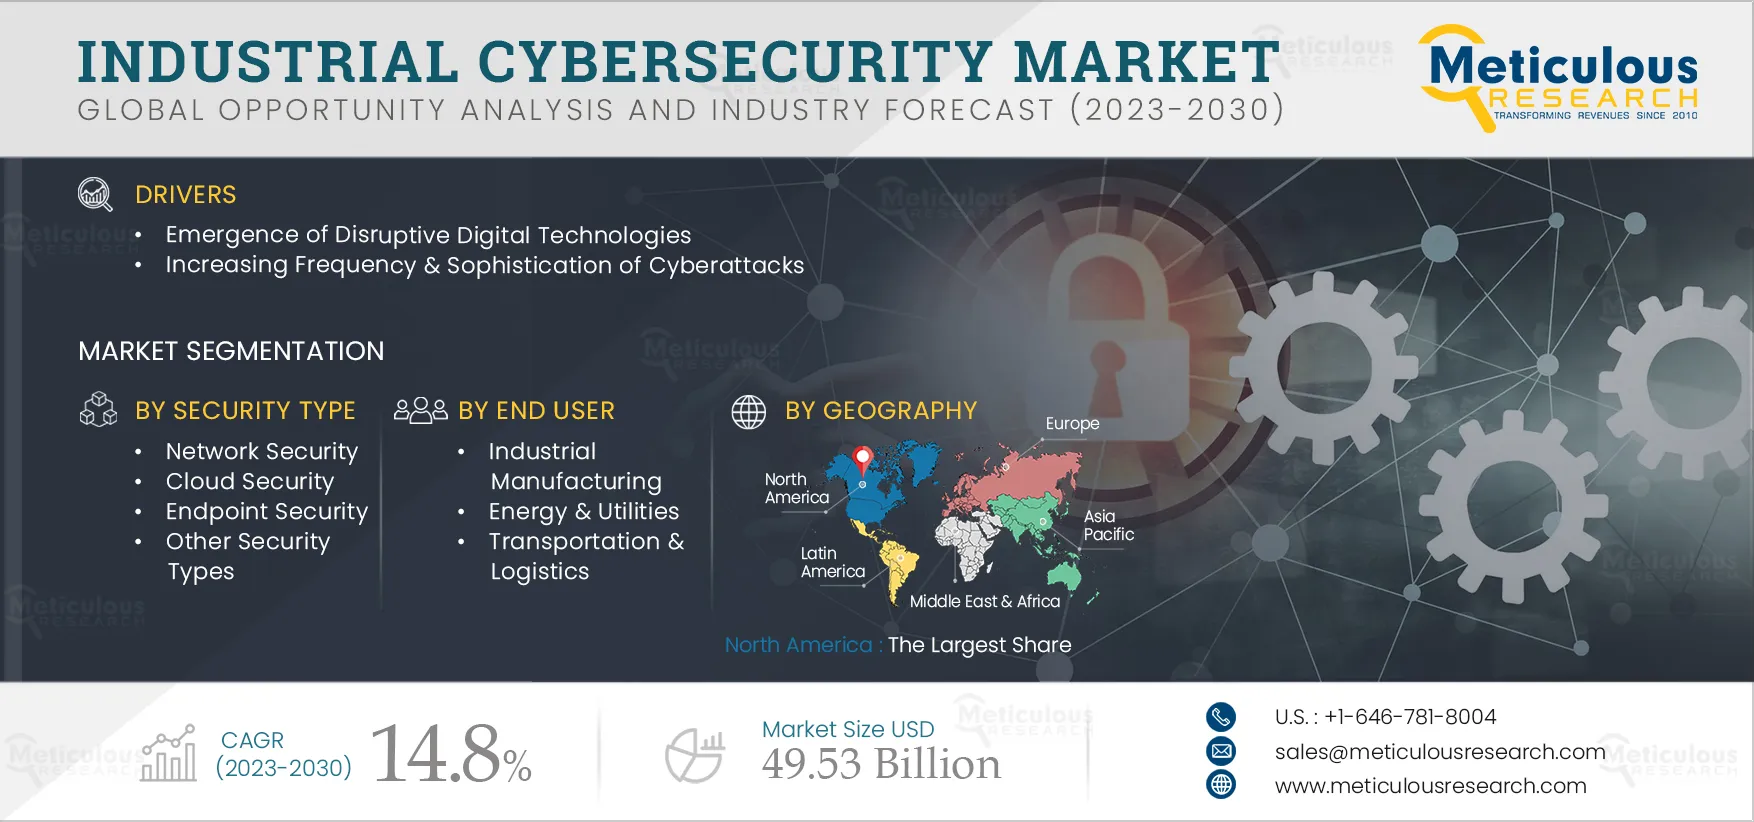
Segments covered: component, security type. Regions: North America, Europe, Asia-Pacific, Latin America.
Key factors driving the growth of this market include the rise of disruptive digital technologies, increasing frequency & sophistication of cyberattacks and cybersecurity regulations & industry compliance. However, the shortage of skilled professionals and complexity of securing of environments restrain this market’s growth.
The growing interest in cloud-based security solutions and AL & ML for threat detection is expected to generate market growth opportunities for the stakeholders operating in this market. Furthermore, the rising adoption of cloud technologies is a major trend in the industrial cybersecurity market.
Report infographic
Market dynamics
4 factors across 3 forcesThe Rise of Disruptive Digital Technologies
As industries across the globe continue to embrace digital transformation, the adoption of disruptive technologies has led to significant improvements in operational efficiency, productivity, and cost reductions. However, this rapid advancement has also introduced a greater number of cybersecurity challenges. The industrial sector, in particular, is becoming increasingly vulnerable to cyber threats due to the integration of advanced technologies such as the Industrial Internet of Things (IIoT), artificial intelligence (AI), machine learning (ML), data analytics, robotics, and cloud computing. While these technologies provide substantial benefits in terms of automation, real-time data analytics, and enhanced decision-making, they also increase the attack surface for cybercriminals, exposing critical infrastructure to a wide array of vulnerabilities.
Governments and organizations around the world have recognized this and are taking steps to facilitate the widespread adoption of Industry 4.0 technologies to drive innovation and efficiency. For example, in November 2024, ADNOC, the UAE's energy giant, announced plans to deploy highly autonomous agentic artificial intelligence (AI) in the energy sector for the first time. This initiative, in collaboration with G42, Microsoft, and AIQ, aims to enhance operational efficiencies, such as speeding up seismic surveys and improving production forecast accuracy.
The increasing frequency and sophistication of cyberattacks targeting the industrial sector have underscored the urgent need for robust cybersecurity measures. In recent reports, the number of cyber incidents in manufacturing environments continues to rise. For instance, a 2023 report by Ponemon Institute revealed that 53% of manufacturing organizations experienced a significant cyberattack, causing disruptions such as production halts, financial losses, and the theft of sensitive data. As industries continue to adopt advanced technologies like machine learning, robotics, and the Internet of Things (IoT), the attack surface grows larger, creating more vulnerabilities. The integration of these technologies into critical infrastructure increases the complexity of industrial environments, making traditional security systems inadequate in combating emerging threats. This shift has driven industries to adopt more sophisticated security strategies, including real-time threat monitoring, advanced access control protocols, and comprehensive surveillance systems to strengthen defense mechanisms and mitigate potential cyber risks.
In response, the industrial sector is adopting next-generation cybersecurity solutions that can proactively defend against the evolving threat landscape. AI and ML technologies, in particular, have become instrumental in detecting potential threats and providing real-time protection by analyzing vast amounts of data for anomalies. Additionally, new security frameworks, such as zero-trust architecture and network segmentation, are being implemented to safeguard sensitive operational systems from unauthorized access. Given the growing reliance on IIoT devices and connected infrastructure, comprehensive endpoint security solutions are essential to prevent cybercriminals from exploiting vulnerabilities in industrial networks.
Overall, the rise of disruptive digital technologies in the industrial sector has created an urgent need for advanced cybersecurity solutions. As these technologies continue to evolve, industries must prioritize securing their systems against a broad range of cyber threats to ensure the safety and continuity of their operations. The continued development of innovative security solutions, coupled with strategic industry partnerships and investment in specialized cybersecurity talent, will be critical in safeguarding the digital future of the industrial sector.
Increasing Frequency & Sophistication of Cyberattacks
The increasing frequency and sophistication of cyberattacks targeting the industrial sector is a primary driver of the growing demand for industrial cybersecurity solutions. The industrial sector, which includes critical infrastructure, manufacturing, energy, utilities, and transportation, has become a prime target for cybercriminals due to the high value of operational technologies (OT) and the potential for widespread disruptions. In 2023, the Cost of a Data Breach report by IBM revealed that industrial organizations face some of the highest data breach costs globally, averaging USD 4.5 million per incident. These breaches not only result in financial losses but also lead to significant disruptions, such as production downtime, loss of intellectual property, and reputational damage. The need for enhanced cybersecurity is further underscored by high-profile attacks like the 2021 ransomware attack on Colonial Pipeline, which resulted in fuel shortages and widespread operational disruptions, costing the company millions of dollars.
As industrial operations increasingly adopt technologies like IoT, AI, robotics, and machine learning, the attack surface expands, introducing new vulnerabilities. According to a 2023 Check Point Software Technologies survey, 72% of manufacturing and energy organizations reported an uptick in cyberattacks, with multi-vector threats targeting both IT and OT systems. Traditional security solutions are often ill-equipped to handle the complexity of modern industrial networks, making it essential to invest in integrated security frameworks. The rise in sophisticated attacks, such as the manipulation of physical systems seen in past incidents like the Stuxnet worm, highlights the need for specialized OT security solutions capable of defending against evolving threats.
This increasing frequency of cyberattacks is propelling the industrial cybersecurity market. Several factors contribute to this growth, including the increasing investment in OT security solutions that integrate both IT and OT systems. The rise of AI-driven cybersecurity tools is also fueling market demand, as these tools offer real-time threat detection and advanced monitoring capabilities. Additionally, heightened regulatory pressures, such as the EU’s Network and Information Systems (NIS) Directive and the U.S. Executive Order 14028, are compelling organizations to adopt more robust cybersecurity practices, further driving the market for compliant solutions. Smaller industrial companies are increasingly turning to cybersecurity-as-a-service (CaaS) models, which provide scalable, expert-driven protection while helping to address budget and resource limitations. The widespread adoption of IoT and edge computing technologies also requires specialized security solutions, as these technologies create new attack vectors. The integration of advanced security measures for these connected devices is another key driver of the industrial cybersecurity market.
Overall, the rising sophistication of cyberattacks on industrial organizations is reshaping the cybersecurity landscape, with increasing investments in advanced security technologies. The industrial cybersecurity market is expected to grow rapidly, driven by the need for integrated, AI-powered solutions, compliance with evolving regulations, and the protection of critical infrastructure and connected systems. As cyber threats continue to evolve, both established players and newcomers to the cybersecurity market must prioritize innovation and proactive threat management to safeguard industrial operations.
Table of contents
12 chapters · 143 sections · 300 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Component | Solutions | — |
| By Security Type | Endpoint Security | — |
| By Deployment Mode | Cloud-Based Deployment | — |
| By End-User | Industrial Manufacturing | — |
By Component
- The Solutions Segment to Dominate the Industrial Cybersecurity Market
- The solutions segment held the dominant share of 56.4%, reflecting its critical role in addressing the growing challenges of data security and privacy.
- The prominence of this segment can be attributed to the heightened concerns over cybersecurity risks in industrial operations, as well as the consistent efforts by industrial stakeholders to enhance operational efficiency, reduce costs, and ensure a resilient security framework.
- Moreover, this segment is also further projected to record a higher CAGR of 15.1% during the forecast period of 2025– 2032.
By Security Type
- The global industrial cybersecurity market categorized by security type into network security, application security, cloud security, endpoint security, and other security types.
- The endpoint security segment is expected to account for the larger share of 40.3% of the global industrial cybersecurity market.
- This segment’s large market share is attributed to the increasing need for organizations to protect their expanding network perimeters, which now include a wide variety of endpoints, such as computers, mobile devices, and IoT devices.
By Deployment Mode
- The cloud-based deployment segment is expected to account for the largest share of 54.7% of the global industrial cybersecurity market.
- This segment’s large market share is attributed to the rapid evolution of cloud technologies, which offer enhanced flexibility, scalability, and cost-efficiency.
- The affordability and superior scalability of cloud-based solutions, coupled with the increasing adoption of cloud platforms by small and medium-sized enterprises (SMEs), are key factors driving this segment's growth.
- Moreover, this segment is also further projected to register the highest CAGR during the forecast period of 2025–2032.
- The increasing reliance on cloud-based environments and the scalability offered by these platforms are expected to further drive this segment's dominance within the global industrial cybersecurity market.
By End-User
- The Industrial Manufacturing Segment to Dominate the Industrial Cybersecurity Market
- Industrial manufacturing is expected to account for the largest share of 65.4% of the global industrial cybersecurity market.
- This segment’s large market share is attributed to the growing demand for real-time security monitoring, rising cybersecurity incidents, and the increasing integration of smart devices and IoT technologies in manufacturing processes.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of 36.1% of the global industrial cybersecurity market. This market is projected to reach USD 8.58 billion in 2025. North America’s significant market share can be attributed to several key factors, including This dominant share can be attributed to several factors, including robust government initiatives to enhance cybersecurity, the rapid adoption of advanced technologies, and the rising number of cyberattacks targeting industrial sectors in the region.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is expected to register the highest growth rate, with a projected CAGR of 15.0% during the forecast period. The growth in this region is driven by the widespread integration of connected devices across industries, the rise of Industry 4.0 technologies, increasing cloud-based solution adoption, and the growing frequency of cyberattacks within the Asia-Pacific industrial sector.
Competitive landscape
- February 2025
Fortinet launched FortiGate 70G, FortiGate 50G, and FortiGate 30G, the latest G series of next-generation firewalls (NGFWs) designed to meet the technology and business demands of today’s distributed enterprises.
- November 2024
Cisco signed a Whole Portfolio Agreement (WPA) agreement with MGM Resorts International for 5.5 years. This provides MGM Resorts access to much of Cisco’s software portfolio and Customer Experience (CX) services to deliver next-generation guest experiences with automation, enhanced security, and innovation.
- August 2024
Juniper Networks partnered with Quantum Bridge Technologies for a strategic investment in Quantum Bridge to develop post-quantum cryptography (PQC) networks. This investment aims to advance quantum-safe communications by enabling Quantum Bridge to further scale its DSKE solution.
- June 2023
IBM Security expanded its integration with Amazon Web Services (AWS) to simplify cloud security. This helps security teams gain better visibility, respond faster to threats, and automate security across their AWS environment. The integrations aim to streamline security operations and improve overall cloud security posture.
- Fortinet, Inc. (U.S.)
- Cisco Systems, Inc. (U.S.)
- Juniper Networks, Inc. (U.S.)
- Palo Alto Networks, Inc. (U.S.)
- IBM Corporation (U.S.)
- Check Point Software Technologies Ltd. · Israel
- F5, Inc. (U.S.)
- Mandiant, Inc. (U.S.)
- Broadcom, Inc. (U.S.)
- Oracle Corporation (U.S.)
- Microsoft Corporation (U.S.)
- Intel Corporation (U.S.)
- Imperva, Inc. (U.S.)
- Cyberark Software Ltd. (U.S.)
- RSA Security LLC (U.S.)
Frequently asked questions
The Industrial Cybersecurity market study focuses on market assessment and opportunity analysis through sales of industrial cybersecurity solutions and services across different regions and countries. This study is also focused on competitive analysis for industrial cybersecurity based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2025). Industrial Cybersecurity Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRICT - 104630). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/industrial-cybersecurity-market-5316