Satellite Imaging Market (2024-2031)
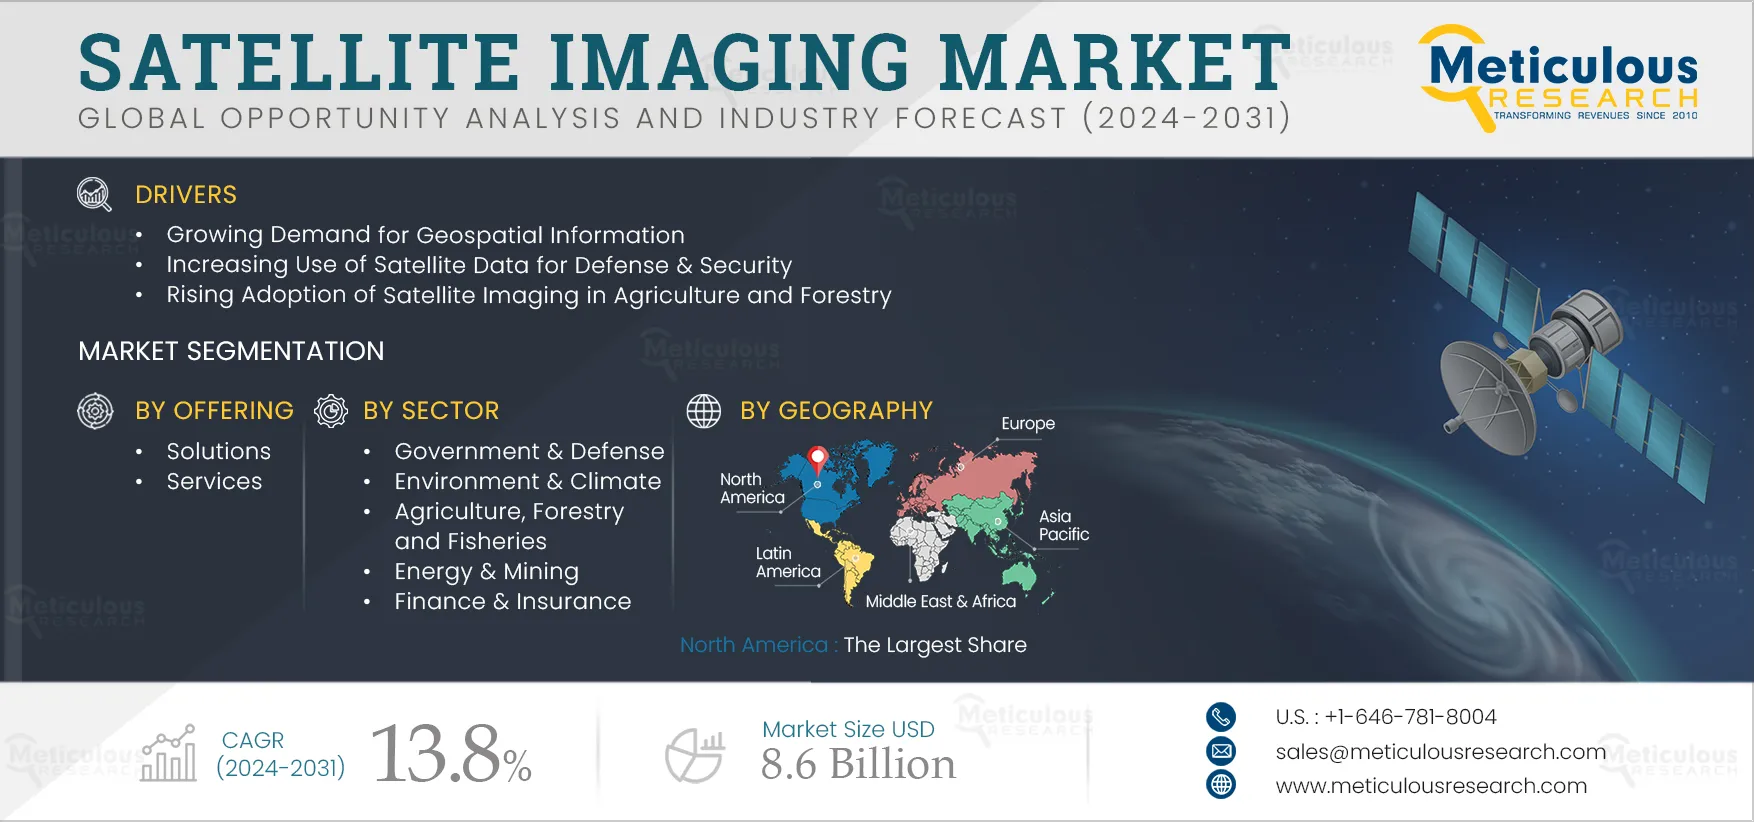
The Satellite Imaging Market was valued at $3.1 billion in 2023. This market is expected to reach $8.6 billion by 2031 from an estimated $3.5 billion in 2024, at a CAGR of 13.8% during the forecast period from 2024 to 2031. Satellite Imaging Market Size & Forecast The growth of this market is driven
- Published
- Aug 2024
- Pages
- 177
- Format
- PDF + Excel
- Report ID
- MR-1058
- Base year
- 2023
- 2023 · BASELINE
- $3.10B
- 2031
- $8.60B
- CAGR 2024–2031
- 13.8%
2023 baseline · 2024–2031 forecast at 13.8% CAGR · hover a bar for the value
Key highlights
The Solutions Segment to Dominate the Satellite Imaging Market in 2024
The Surveillance & Reconnaissance Segment to Dominate the Satellite Imaging Market in 2024
The Government & Defense Segment to Dominate the Satellite Imaging Market in 2024
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 177 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 13.8% |
| Market Size (Value) | USD 8.6 Billion by 2031 |
| Segments Covered | By Offering · Solutions · Services · By Application · Surveillance & Reconnaissance · Environmental Conservation & Research · Infrastructure Planning & Monitoring · Agricultural Planning · Weather Forecasting · Disaster Response & Aid Planning · Forestry Monitoring & Management · Navigation · Other Applications · By Sector · Government & Defense · Environment & Climate · Agriculture, Forestry and Fisheries · Energy & Mining · Finance & Insurance · Transportation & Logistics · Other Sectors |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., Italy, Spain, Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Rest of Asia-Pacific), Latin America Middle East & Africa |
| Key Companies | Maxar Technologies Holdings Inc. (U.S.), Airbus SE (Netherlands), Lockheed Martin Corporation (U.S.), L3Harris Technologies, Inc. (U.S.), BlackSky Technology Inc. (U.S.), SpaceKnow, Inc. (U.S.), Satellite Imaging Corporation (U.S.), Capella Space Corp. (U.S.), EOS Data Analytics, Inc. (U.S.), Telespazio UK Ltd (U.K.), Arlula Pty Ltd (Australia), ICEYE (Finland), Remote Sensing Technology Center of Japan (RESTEC) (Japan), Shoghi Communications Ltd. (India), Planet Labs PBC (U.S.), European Space Imaging GmbH (Germany), EarthDaily Analytics Corp. (Canada), SatSure Analytics India Pvt Ltd (India), RMSI Pvt. Ltd. (India), Trimble Inc. (U.S.), Satellogic Inc. (U.S.), and Spire Global, Inc. (U.S.). |
Report overview
Segments covered: offering, application, sector. Regions: North America, Europe, Asia-Pacific.
The growth of this market is driven by the rising demand for geospatial information, the expanding use of satellite data for defense and security, the increased application of satellite imaging in agriculture and forestry, the growing adoption of satellite imaging in urban planning, and the increased utilization of satellite imaging in airport mapping. However, stringent regulatory frameworks are expected to restrain the growth of this market.
The growing use of satellite imaging for environmental monitoring and the increasing adoption of satellite imagery in wildlife conservation and ecology applications are anticipated to create significant market growth opportunities. However, data security concerns and atmospheric interference are significant challenges for players operating in this market.
Market dynamics
4 factors across 3 forcesIncreasing Use of Satellite Data for Defense & Security
Satellite photography, leveraging advanced Geographic Information System (GIS) technologies, plays a critical role in military and defense applications by enabling precise geospatial analysis through high-resolution images. These capabilities enhance mission planning, target identification, and strategic location monitoring. GIS tools facilitate the integration of multiple data layers, allowing defense personnel to gain a comprehensive understanding of their operational environment. Additionally, geospatial intelligence derived from satellites aids in risk assessments, tracking troop movements, and evaluating terrain characteristics in dynamic security contexts. The synergy between GIS and satellite imagery provides military decision-makers with essential insights that ensure a strategic advantage and effective response capabilities.
Several players in the market offer satellite imaging services specifically for the defense and security sector, which is anticipated to drive market growth. For example, Satellite Imaging Corporation (SIC) (U.S.) provides geospatial products and services to government agencies and defense contractors for a range of applications in defense and security mapping.
Rising Adoption of Satellite Imaging in Urban Planning
Rapid urban development is placing increased pressure on the environment, including green spaces and urban parks. Satellite imaging has become an essential tool for urban planning, enabling the mapping and monitoring of changes in land use, infrastructure development, and urban growth. GIS specialists utilize high-resolution imagery to assess the environmental impacts of urban expansion, identify high-density areas, and analyze spatial trends. Satellite imagery facilitates the creation of accurate and up-to-date maps, significantly contributing to disaster risk assessment by identifying vulnerable regions and improving emergency response preparedness. This information empowers city planners to make informed decisions regarding zoning, transit networks, and infrastructure development.
Governments in various countries are partnering with satellite image providers to enhance urban management. For example, in August 2024, Bahrain’s Survey and Land Registration Bureau (SLRB) collaborated with Aetosky (Singapore) and Planet (U.S.) to transform urban planning in the country. By utilizing SkySat's 50 cm high-resolution satellite imagery, this partnership has introduced an advanced urban planning system covering 850 square kilometers, which improves municipal operations and environmental monitoring. As a result, the use of satellite imagery in sustainable urban planning and development is increasing, driving growth in this market.
Table of contents
11 chapters · 108 sections · 177 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Offering | Solutions | — |
| By Application | Surveillance & Reconnaissance | — |
| By Sector | Government & Defense | Environment & climate |
By Offering
- The Solutions Segment to Dominate the Satellite Imaging Market in 2024
- The solutions segment is expected to account for a larger share of 60.8% of the global satellite imaging market.
- The large market share of this segment is attributed to the increasing use of satellite data to enhance agricultural productivity, the growing adoption of satellite imaging solutions across various industries, and the rising integration of AI technologies to improve data analysis and insights.
- Satellite imaging solutions provide significant advantages across multiple sectors, including government and defense, environmental and climate monitoring, energy and mining, marine applications, and agriculture, facilitating informed decision-making.
- These sectors increasingly depend on satellite imaging for effective environmental monitoring and management.
- For example, in September 2022, the U.S. National Geospatial-Intelligence Agency (NGA) awarded Maxar Technologies Holdings Inc. a contract renewal for Option Year 3 of the Global Enhanced GEOINT Delivery (G-EGD) program.
- However, the services segment is projected to register a higher CAGR during the forecast period.
- This growth is attributed to the rising utilization of satellite imagery for various monitoring applications and the increasing collaborations among market stakeholders to enhance service capabilities.
- Key providers offer customized services tailored to specific customer needs, including vegetation monitoring, environmental assessments, flood risk evaluations, and infrastructure oversight.
- These services empower organizations to make informed decisions by providing detailed insights into monitored sites.
- For example, in February 2023, the Guyana Ministry of Natural Resources (MNR) signed a three-year contract with Maxar Technologies Holdings Inc. (U.S.) for environmental monitoring services encompassing both offshore and terrestrial areas.
By Application
- The surveillance & reconnaissance segment is expected to account for the largest share of 30.0% of the global satellite imaging market.
- The large market share of this segment is attributed to the growing development of satellites for military applications and the increasing use of satellite imagery for surveillance and reconnaissance purposes.
- Various key market players are actively focusing on developing satellites for diverse military applications.
- For instance, in November 2023, Tata Advanced Systems Limited (India) established a facility in collaboration with Satellogic Inc. (U.S.), an earth observation satellite specialist, to manufacture high-resolution imaging satellites.
- These satellites will be used for military purposes, including surveillance, reconnaissance, and target identification, thereby enhancing India's capacity to monitor its borders and deter potential threats.
- However, the disaster response & aid planning segment is projected to register a higher CAGR during the forecast period.
- This growth is driven by the rising adoption of satellite imaging solutions for analyzing and monitoring natural disasters such as hurricanes, tornadoes, volcanoes, and earthquakes, as well as the increasing utilization of satellite imagery by governments to deploy disaster management teams and provide targeted assistance in affected areas.
- Several stakeholders have provided satellite imagery data to support disaster management efforts.
- For example, in May 2024, NASA assisted the U.S. Space Force and Air Force during a flood disaster in Brazil by supplying data and imagery that helped on-the-ground responders assess the impact of the disaster and coordinate aid deployment.
By Sector
- The government & defense segment is expected to account for the largest share of 41.2% of the global satellite imaging market.
- The large market share of this segment is attributed to the increasing adoption of satellite imaging by government agencies to monitor environmental changes such as deforestation, natural disasters, and climate change.
- Additionally, there is rising use of maps and imagery for land use, infrastructure development, and population growth in urban planning, as well as an increasing reliance on satellite imaging by defense agencies to track military activities, troop movements, and potential threats.
- Several companies are partnering with governments worldwide to enhance their satellite imaging data offerings.
- For instance, in August 2024, Planet Labs PBC (U.S.) signed an agreement with NATO’s Communications and Information Agency (NCIA) to provide access to satellite images.
- The tasking capabilities of Planet Labs will empower NCIA decision-makers by offering images for detailed tracking and analysis of foreign military capabilities and activities, monitoring military infrastructure, and detecting movements.
- However, the environment & climate segment is expected to register the highest CAGR during the forecast period.
- This growth is driven by the increasing adoption of satellite imaging to monitor sea surface temperature, atmospheric temperature, and weather patterns and the rising use of satellite imagery by government agencies to analyze the effects of urbanization on local climates and ecosystems.
- Several market players are forming partnerships with government agencies to provide precise, high-resolution imaging aimed at reducing the loss of life and infrastructure.
- For example, in May 2024, the African Union Commission (AUC) (East Africa) signed an agreement with the European Organisation for the Exploitation of Meteorological Satellites (Germany), Europe’s meteorological satellite agency, to enhance their collaboration on Earth observation.
- This agreement will facilitate access to accurate, high-resolution data for users in Africa to develop space, meteorological, and climate strategies.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 42.6% of the global satellite imaging market, followed by Asia-Pacific, Europe, Latin America, and the Middle East & Africa. The growth of the satellite imaging market in North America is driven by the high adoption of data-driven methods in business operations, an increasing demand for high-resolution imagery services, and the rapid integration of advanced analytics, AI, and machine learning. Additionally, rising government initiatives, the presence of prominent players in the region, and the growing demand for geospatial information further support this growth. North American businesses are increasingly advocating for the incorporation of satellite imaging solutions and services. For example, in May 2022, Maxar Technologies Holdings Inc. (U.S.) announced that the National Oceanic and Atmospheric Administration (NOAA) had modified its remote sensing license to enable non-Earth imaging (NEI) capabilities for both its existing satellite constellation and the next-generation WorldView Legion satellites. North America to Dominate the Satellite Imaging Market in 2024
Asia-Pacific
Fastest growthHowever, the Asia-Pacific region is projected to record the highest CAGR of 15.0% during the forecast period. The growth of this market is primarily driven by rapid advancements in satellite technology, an increasing demand for satellite imaging across various applications, including urban planning and infrastructure development, and a rising need for satellite services in smart agriculture.
Competitive landscape
- June 2024
NEC Corporation (Japan) and Ursa Space Systems Inc. (U.S.) partnered to offer satellite image data analysis services. By integrating their services and technologies, the two companies aim to provide enterprise solutions across various applications.
- January 2024
EOS Data Analytics, Inc. (U.S.) launched EOS SAT-1, the first satellite in the EOS SAT constellation, designed specifically for agriculture, into low Earth orbit using SpaceX’s Falcon 9 rocket from the Cape Canaveral Space Force Station in Florida. EOS SAT aims to support sustainable agricultural practices and environmental monitoring of forestlands by providing high-quality data for analysis. Additionally, it will assist agribusinesses in monitoring crop growth and identifying issues such as heat stress, cold stress, water stress, weed proliferation, pest attacks, and other threats to crops.
- April 2023
Bluesky International (U.K.), a prominent aerial survey and geographic data company, partnered with Berlin-based UP42, a leading geospatial developer platform and marketplace. As part of this agreement, Bluesky will provide UP42 with its accurate, high-resolution aerial imagery covering Great Britain and the Republic of Ireland, along with other geospatial datasets.
- Maxar Technologies Holdings Inc. (U.S.)
- Airbus SE · Netherlands
- Lockheed Martin Corporation (U.S.)
- L3Harris Technologies, Inc. (U.S.)
- BlackSky Technology Inc. (U.S.)
- SpaceKnow, Inc. (U.S.)
- Satellite Imaging Corporation (U.S.)
- Capella Space Corp. (U.S.)
- EOS Data Analytics, Inc. (U.S.)
- Telespazio UK Ltd (U.K.)
- Arlula Pty Ltd · Australia
- ICEYE · Finland
- Remote Sensing Technology Center of Japan (RESTEC) · Japan
- Shoghi Communications Ltd. · India
- Planet Labs PBC (U.S.)
- European Space Imaging GmbH · Germany
- EarthDaily Analytics Corp. · Canada
- SatSure Analytics India Pvt Ltd · India
- RMSI Pvt. Ltd. · India
- Trimble Inc. (U.S.)
- Satellogic Inc. (U.S.)
- Spire Global, Inc. (U.S.)
Frequently asked questions
This study focuses on market assessment and opportunity analysis by analyzing the sales of satellite imaging solutions & services across various regions and countries. This study also offers a competitive analysis of the satellite imaging market based on an extensive assessment of the leading players' product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2024). Satellite Imaging Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MR-1058). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/satellite-imaging-market-5741