Africa IVD Market (2025-2032)
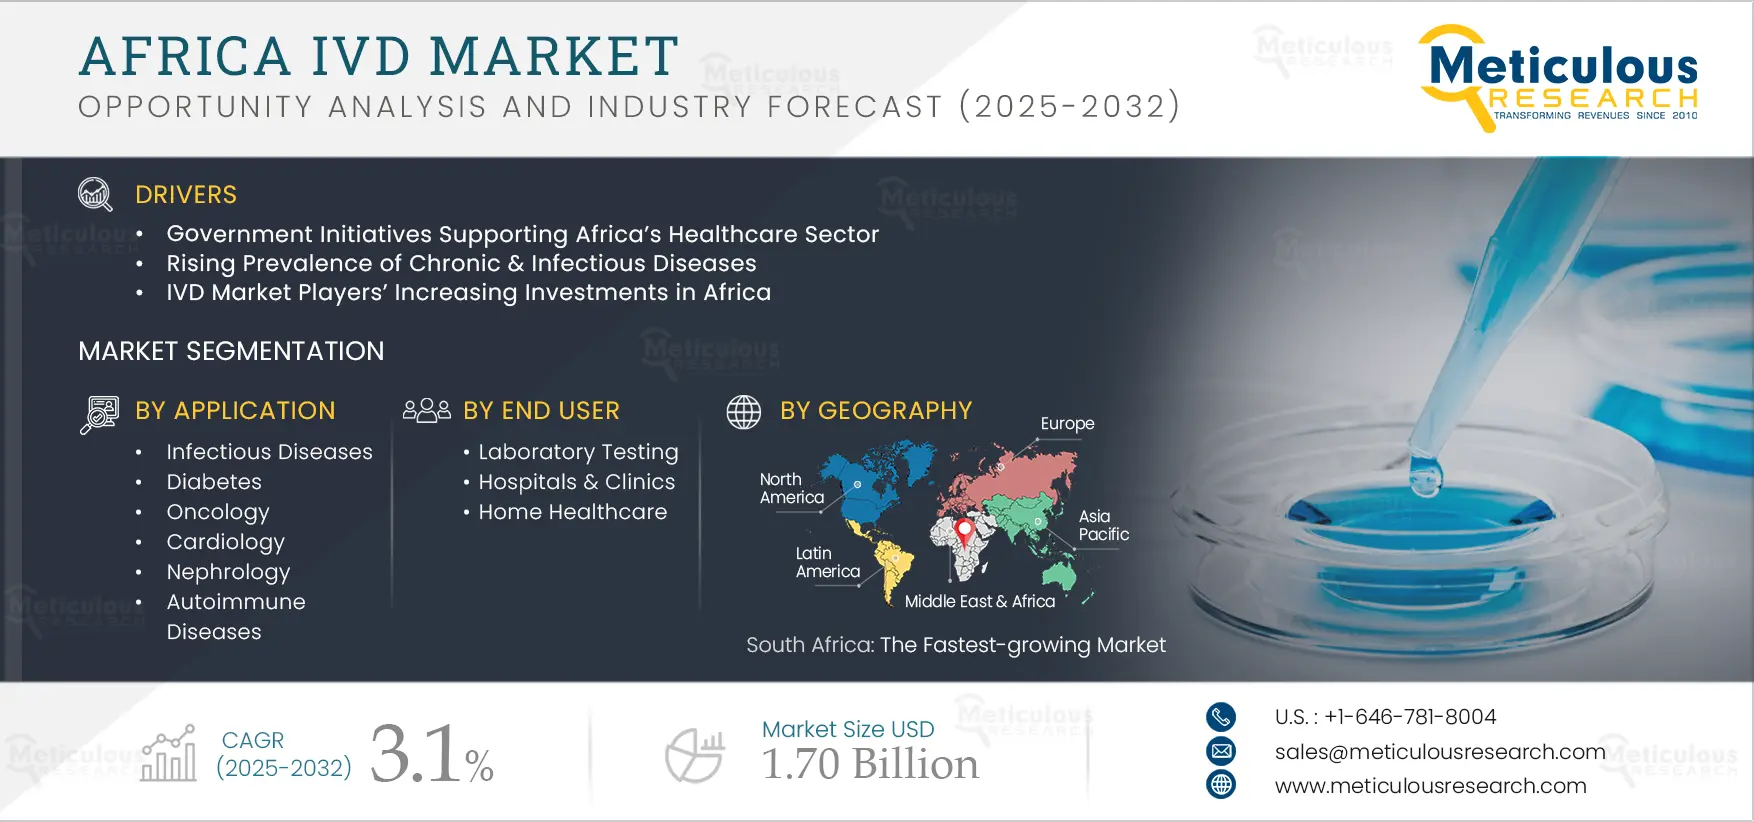
The Africa IVD market was valued at $1.33 billion in 2024. This market is expected to reach $1.70 billion by 2032 from an estimated $1.37 billion in 2025, at a CAGR of 3.1% during the forecast period of 2025–2032.
- Published
- Apr 2025
- Pages
- 242
- Format
- PDF + Excel
- Report ID
- MR-731
- Base year
- 2023
- 2024 · HISTORICAL
- $1.33B
- 2032
- $1.70B
- CAGR 2025–2032
- 3.1%
2023–2024 baseline · 2025–2032 forecast at 3.1% CAGR · hover a bar for the value
Key highlights
The Africa IVD market was valued at $1.33 billion in 2024.
This market is expected to reach $1.70 billion by 2032 from an estimated $1.37 billion in 2025, at a CAGR of 3.1% during the forecast period of 2025–2032.
Similarly, the kits & reagents segment is projected to witness the highest growth rate of 3.3% during the forecast period of 2024–2031.
In 2024, South Africa is expected to account for the largest share of 30.4% of the Africa IVD market. The high prevalence of chronic and infectious diseases coupled with good access to healthcare and high healthcare expenditure in South Africa compared to other countries of Africa drives the market.
Report summary
| Particulars | Details |
|---|---|
| Page No | 242 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2023 |
| CAGR | 3.1% |
| Market Size (Value) | $1.70 billion by 2032 |
| Segments Covered | By Offering · Reagents & Kits · Instruments · Software & Services · By Technology · Immunoassay/Immunochemistry · Whole Blood Glucose Monitoring · Molecular Diagnostics · Point-of-care Diagnostics · Biochemistry/Clinical Chemistry · Microbiology · Hematology · Coagulation & Hemostasis · Other IVD Technologies · (Note: Other IVD Technologies include hybridization and loop-mediated amplification) · By Application · Infectious Diseases · Diabetes · Oncology · Cardiology · Nephrology · Autoimmune Diseases · Other Applications · (Note: Other applications include toxicology, gastroenterology, neonatal, genetic, and neurological disorders) · By Diagnostic Approach · Diagnostic Laboratories · Point-of-care Testing · OTC/Self-testing · By End User · Laboratory Testing · Hospitals & Clinics · Home Healthcare · Other End Users · (Note: Other end-users segment includes long-term care facilities, academic & research institutes, ambulatory care centers, and transfusion laboratories) |
| Countries Covered | South Africa, Algeria, Nigeria, Kenya, Morocco, Tunisia, Tanzania, Egypt, Côte d’Ivoire, Cameroon, and the Rest of Africa |
| Key Companies | Abbott Laboratories (U.S.), Becton, Dickinson and Company (U.S.), bioMérieux SA (France), Danaher Corporation (U.S.), F. Hoffmann-La Roche Ltd (Switzerland), QIAGEN N.V. (Netherlands), Siemens Healthineers AG (Germany), Thermo Fisher Scientific Inc. (U.S.), Bio-Rad Laboratories, Inc., (U.S.), Illumina, Inc. (U.S.), and Shenzhen Mindray Bio-Medical Electronics Co., Ltd (China). |
Report overview
Segments covered: offering.
The Africa IVD market expenditure and the rising prevalence of chronic & infectious diseases, IVD market players’ increasing investments in Africa, the growing demand for Point-of-care (POC) & rapid diagnostics, the rising geriatric population, government initiatives supporting Africa's healthcare sector, rising healthcare expenditure, and increasing R&D expenditure.
Moreover, increasing awareness regarding the importance of early diagnosis, advances in genomics & proteomics, and the increasing adoption of personalized medicine are expected to generate growth opportunities for the players operating in the Africa IVD market.
In Africa, chronic illnesses caused by infectious diseases, premature deaths, and loss of productivity are hampering the region's economic growth.
Infectious diseases account for over 227 million years of health life lost and an annual productivity loss of over USD 800 billion.
Furthermore, of the estimated 10 million deaths per annum due to infectious diseases, the majority of them occur in Africa.
This high burden, along with the growing adoption of point-of-care testing, is favored by the use of test kits to obtain rapid results, driving the segment growth.
In April 2024, the Africa Centres for Disease Control and Prevention (Africa CDC) launched two projects, namely the Integrated Genomic Surveillance and Data Sharing Platform (IGS) and Integrated Genomic Surveillance for Outbreak Detection (DETECT), co-funded by the European Union.
These initiatives are expected to strengthen the Africa Pathogen Genomics Initiative (Africa PGI 2.0), enhancing the member states’ capacity for the molecular detection of outbreaks, timely data sharing across Africa, and AMR genomic surveillance.
However, the point-of-care testing segment is expected to grow at a faster CAGR during the forecast period.
The segment’s growth can be attributed to the affordability, ease of use, and rapid results offered by the POCT, high burden of hepatitis, syphilis, and HIV coupled with POCT as the preferred option for testing these diseases, and favorable initiatives to expand the access of POCT in the region.
Efforts to enhance patient care are underway, with African countries and key players working to expand access to POCT.
For example, in February 2022, Siemens Healthineers partnered with UNICEF to optimize POCT networks in Africa.
Market dynamics
4 factors across 3 forcesRising Prevalence of Chronic & Infectious Diseases
Chronic diseases such as cancer, diabetes, and cardiovascular diseases are gradually becoming the major causes of mortality in Africa. According to the WHO, in 2022, 24 million adults in Africa had diabetes, and this number is expected to reach 55 million by 2045. Chronic diseases have endangered the health and lives of millions of Africans, accounting for more than one-third of all deaths in the region.
Moreover, frequent endemic disease outbreaks in African countries also contribute to the high demand for IVD products. For instance, according to the United Nations Africa Renewal digital magazine published in July 2022, the risk of outbreaks caused by zoonotic pathogens such as the Ebola & monkeypox viruses that originate in animals and infect humans is on the rise. There has been a 63.0% increase in the number of zoonotic disease outbreaks in Africa during 2012–2022 compared to 2001–2011 (Source: WHO). Also, in July 2022, the Ministry of Health of the Democratic Republic of the Congo declared the end of the 14th Ebola outbreak since 1976. Thus, the rising disease prevalence has boosted the demand for IVD products in Africa.
Government Initiatives Supporting Africa’s Healthcare Sector
Governments in Africa are undertaking initiatives to expand and modernize Africa’s healthcare sector largely in collaboration with developed countries and global organizations. Africa’s healthcare sector is witnessing a consistent expansion due to frequent infectious disease outbreaks, technological advancements, and the rising need for the early diagnosis of chronic diseases. For instance, in March 2024, three health Team Europe Initiatives (TEIs) were launched during the European Union (EU) – African Union (AU) Partnership on Global Health for Equitable Access event in Brussels. The TEIs aim to strengthen health security, support public health institutes in Africa, and boost digital health. The collaboration between the Africa CDC and ECDC, which started in 2021, will receive USD 145.5 million (EUR 123 million) from the EU budget during 2022–2027.
In addition, governments in Africa have been collaborating with international organizations and agencies to tackle the burden of diseases and develop & support health facilities. For instance, in June 2022, the U.S. Embassy in Nairobi (Kenya) announced the approval of USD 345 million in funding through the United States President’s Emergency Plan for an AIDS Relief program (PEPFAR) to support Kenya’s HIV response. These funds were used to support critical solutions required to maintain epidemic control in Kenya. Such initiatives supporting Africa’s healthcare sector are boosting the demand for IVD products in Africa.
Table of contents
13 chapters · 110 sections · 242 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Offering | Kits & reagents | — |
| Other segments | — | Kits & reagents |
| By Technology | Immunoassay/immunochemistry | — |
| By Application | Infectious diseases | — |
| By Diagnostic Approach | Laboratory testing | — |
| By End User | Hospitals & clinics | — |
By Offering
- The Africa IVD market is segmented into reagents & kits, instruments, and software & services.
- The kits & reagents segment is expected to account for the largest share of 83.1% of the Africa IVD market.
- The large market share of this segment is attributed to the recurring use of assays & kits in the detection of various chronic diseases, the commercial availability of a diverse range of reagents & consumables for the diagnosis of various diseases, and the increase in the volume of testing for infectious diseases such as COVID-19 and influenza.
Other segments
- Similarly, the kits & reagents segment is projected to witness the highest growth rate of 3.3% during the forecast period of 2024–2031.
- The growth of this segment is driven by the emerging threats of infectious diseases such as malaria, tuberculosis, and other neglected tropical diseases, increasing test volumes for infectious diseases, and favorable initiatives to improve diagnosis, treatment, and healthcare access.
- However, the molecular diagnostics segment is expected to grow at the highest CAGR of 3.8% during the forecast period of 2024-2031.
- The segment’s growth is attributed to the high prevalence of infectious diseases, the increasing penetration of advanced molecular diagnostic tests, higher accuracy offered by molecular diagnostics compared to other techniques, and favorable initiatives to enhance molecular detection capabilities in the region.
- However, the cardiology segment is expected to grow at the highest CAGR during the forecast period of 2024 to 2031.
- The growing cardiac disease burden, coupled with advancements in cardiac disease diagnostic testing and the growing awareness of point-of-care and rapid cardiac tests among healthcare providers, including physicians and cardiologists, is expected to drive the segment’s growth.
- Similarly, the hospitals & clinics segment is expected to grow at the highest CAGR during the forecast period of 2024 to 2031.
- With the frequent outbreaks of infectious diseases and the increasing prevalence of chronic diseases, the number of hospital visits is expected to increase, which is expected to support the segment's growth in the future.
- African countries are also significantly investing in hospital infrastructure to treat patients from across the world.
- For instance, in February 2024, Roha Medical Campus, backed by U.S. investors, invested USD 400 million to open a hospital complex, which is expected to be operational in 2025.
- Such initiatives, coupled with the rising prevalence of diseases, growing number of hospitals, and rising demand for diagnostic testing, drive the segment growth.
By Technology
- The Africa IVD market is segmented into immunoassay/immunochemistry, whole blood glucose monitoring, molecular diagnostics, point-of-care diagnostics, biochemistry/clinical chemistry, microbiology, hematology, coagulation & hemostasis, and other IVD technologies.
- The immunoassay/immunochemistry segment is expected to account for the largest share of 34.5% of the Africa IVD market.
- The segment’s large share is attributed to the benefits of immunoassay technologies, such as efficient, convenient, and accurate research tools for the detection and quantitation of targets, continuous development of new biomarkers, and cost-effectiveness, coupled with the growing adoption of automated platforms for ELISA.
By Application
- The Africa IVD market is segmented into infectious diseases, diabetes, oncology, cardiology, nephrology, autoimmune diseases, and other applications.
- The infectious diseases segment is expected to account for the largest share of the Africa IVD market.
- This segment’s large market share can be attributed to the high prevalence of infectious diseases like COVID-19, dengue, and HIV in the region, increasing awareness about diagnostic testing, and the growing availability of low-cost rapid test kits.
By Diagnostic Approach
- The Africa IVD market is categorized into laboratory testing, point-of-care testing, and OTC/self-testing.
- The laboratory testing segment is expected to account for the largest share of the Africa IVD market.
- The large market share of this segment is attributed to the availability of several IVD tests and the higher accuracy of laboratory testing.
- In Africa, the laboratory testing landscape is evolving.
- Investments in diagnostic tests are primarily directed toward larger markets such as Egypt, Nigeria, and South Africa.
- According to the Prosper Africa Healthcare Report 2023, Egypt secured USD 109 million across three deals for diagnostic services.
- Similarly, Nigeria saw a deal value of USD 36 million through four deals.
By End User
- The Africa IVD market is segmented into diagnostic laboratories, hospitals & clinics, home healthcare, and other end users, which include nursing homes, academic & research institutes, ambulatory care centers, and transfusion laboratories.
- The hospitals & clinics segment is expected to account for the largest share of the Africa IVD market.
- The largest share of the segment is attributed to the increase in the number of hospitals & clinics, the rising patient population, the increasing prevalence of infectious diseases, and the rise in funding for the expansion of hospital infrastructure.
Geographic analysis
Middle East & Africa
Largest shareIn 2024, South Africa is expected to account for the largest share of 30.4% of the Africa IVD market. The high prevalence of chronic and infectious diseases coupled with good access to healthcare and high healthcare expenditure in South Africa compared to other countries of Africa drives the market. Similarly, growing healthcare expenditure, growing availability due to partnerships and collaborations between diagnostic test providers and distributors, favorable government initiatives, and growing healthcare infrastructure and access in South Africa drive market growth. The market in South Africa is expected to grow at the highest CAGR of 3.9% during the forecast period of 2024 to 2031.
Competitive landscape
- 2024
Abbott Laboratories Inc. (U.S.) received U.S. FDA approval for a whole blood rapid test to diagnose mild traumatic brain injury. This test runs on Abbott’s portable i-STAT Alinity instrument.
- January 2024
Becton Dickinson, and Company (U.S.) collaborated with the government of Kenya through the National Cancer Institute-Kenya to expand access to critical cancer diagnosis for women in Kenya.
- September 2022
Siemens Healthineers AG (Germany) launched its PCR tests, FTD SARS-CoV2/FluA/FluB/HRSV Assay and CLINITEST Rapid COVID-19 + Influenza A/B Antigen Test, to allow effectual management of seasonal respiratory testing.
- Abbott Laboratories (U.S.)
- Becton
- Dickinson and Company (U.S.)
- Danaher Corporation (U.S.)
- F. Hoffmann-La Roche Ltd · Switzerland
- QIAGEN N.V. · Netherlands
- Siemens Healthineers AG · Germany
- Thermo Fisher Scientific Inc. (U.S.)
- Bio-Rad Laboratories, Inc.
- (U.S.)
- Illumina, Inc. (U.S.)
- Shenzhen Mindray Bio-Medical Electronics Co., Ltd · China
Frequently asked questions
The Africa IVD market covers the market sizes & forecasts by offering, technology, application, diagnostic approach, and end user. The Africa IVD market studied in this report involves the value analysis of various segments and sub-segments of the Africa IVD market at regional and country levels.
Cite this report
Meticulous Research. (2025). Africa IVD Market - Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MR-731). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/africa-ivd-market-5415